Carlsmed's Q3 Test: Can Growth Clear A Seasonal Lull After Four Straight Guidance Raises?
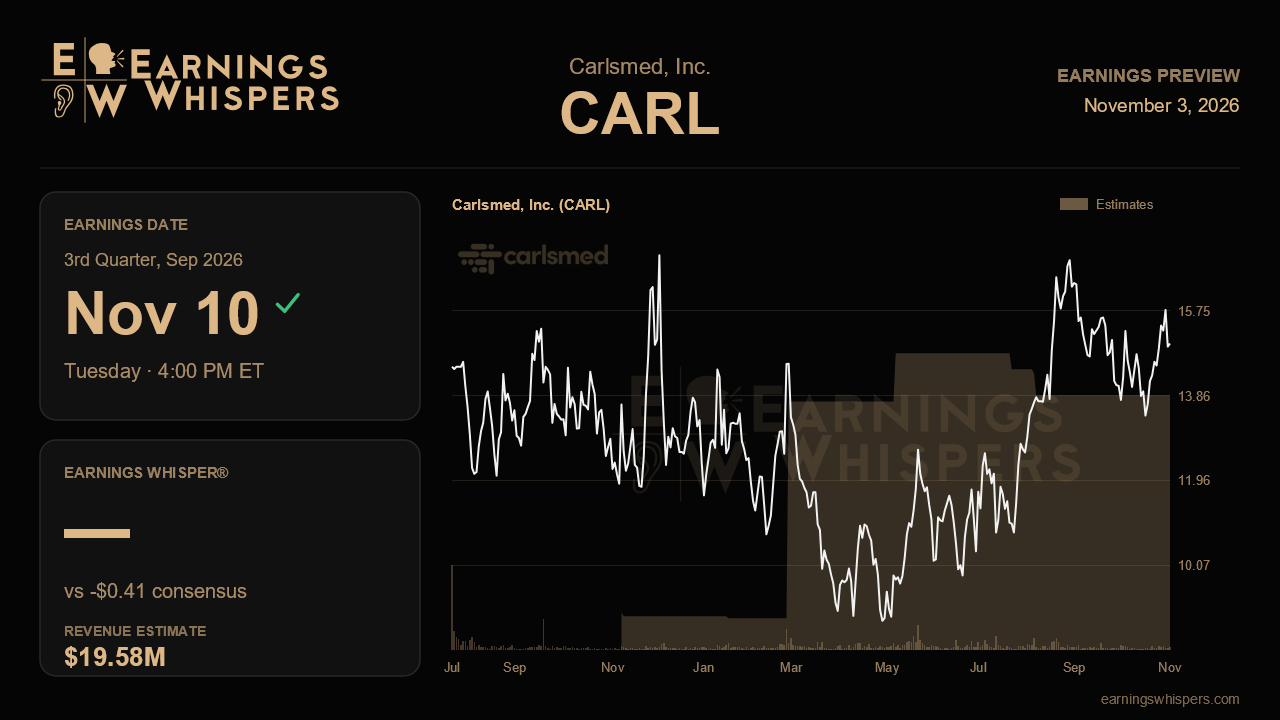
Carlsmed heads into its third-quarter report with an awkward kind of problem: management has spent a year telling investors that demand for its personalized spine implants keeps outrunning forecasts, and the Street has largely taken that at its word. Revenue guidance has climbed four times in a row, the full-year analyst estimate already sits near the top of the company's range, and the shares have outperformed the broader market since the last report. That makes the September quarter, which management itself flagged as seasonally softer, a real test of whether the ramp can keep pace with rising expectations.
Analysts are looking for revenue of about $19.6 million, roughly 50% above the $13.1 million posted a year earlier, and a loss of $0.41 a share, slightly wider than both the year-ago $0.40 and last quarter's $0.39. The revenue figure implies only modest sequential growth from the second quarter's $18.9 million, a far gentler step than the jump from $16.1 million in the first quarter. That restraint looks deliberate. Carlsmed reaffirmed its 2026 outlook of $74 million to $78 million, but consensus of $76.9 million lands well above the midpoint. With first-half sales of about $35 million, the Street is effectively asking for roughly $42 million in the back half, closer to 48% growth than the roughly 45% management's midpoint implies. A third quarter near or above $19.6 million would keep that gap credible; a print that slips toward $19 million would make the high end of the range look ambitious unless the fourth quarter carries a lot of weight.
The operating details matter as much as the headline. Last quarter, cervical products reached about a tenth of revenue only months after launch, and the surgeon user base was growing around 60% a year. Evidence that both trends held through a slow summer would support management's argument that the guided slowdown reflects prudence rather than fading demand. Gross margin is the other tell. It has hovered in the high 70s, at 76.8% last quarter, and management lifted its longer-term ambition to the low 80s within two years. Because cervical carries a much lower average selling price than lumbar, roughly $18,000 versus $29,000, a growing cervical mix could pressure the average even as volumes rise, so steady margins alongside rising cervical share would be a quietly strong signal.
Investors should also listen for progress on the catalysts management lined up for the fourth quarter: the CORA cervical plating launch, which should lift cervical pricing, the Aprivo bilateral lumbar system aimed at a roughly 30,000-procedure market, and enrollment in the new cervical registry. The finalized hospital reimbursement rule creating three premium lumbar payment groups took effect October 1, so it will not show up in these numbers, but early commentary on hospital access would help frame 2027. On the other side of the ledger, losses widened to $10.5 million last quarter, cash fell to $89.3 million, and rivals have begun announcing custom-implant plans. Any sign that burn is reaccelerating or that competition is surfacing in surgeon conversations would challenge the bullish tone.
Sentiment has warmed noticeably, with the reading easing to only slightly bearish from a more pessimistic stance before the prior report, and the stock is up about 8% since then while the S&P 500 slipped. At around $15, shares trade comfortably above their 200-day average but sit in the middle of their post-earnings range, well below the $17.23 high, so the market has rewarded the story without fully pricing in another upside surprise.
The central question is whether Carlsmed can absorb seasonal softness and still keep the Street's above-midpoint full-year forecast intact. A fifth guidance raise, or even a reaffirmation backed by firm surgeon growth and stable margins, would preserve the narrative. A soft quarter paired with wider losses would suggest the ramp is leaning harder on 2027 reimbursement than investors have assumed.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-27 | |
| Oct-14 | |
| Oct-02 | |
| Oct-01 | |
| Sep-29 | |
| Sep-28 | |
| Sep-15 | |
| Sep-08 | |
| Aug-06 | |
| Aug-05 | |
| Aug-03 | |
| Jul-27 | |
| Jul-22 | |
| May-05 |
