Aptiv Clears A Lowered Bar, But A Flat 2027 Preview Shows Auto Headwinds Outlasting The Beat
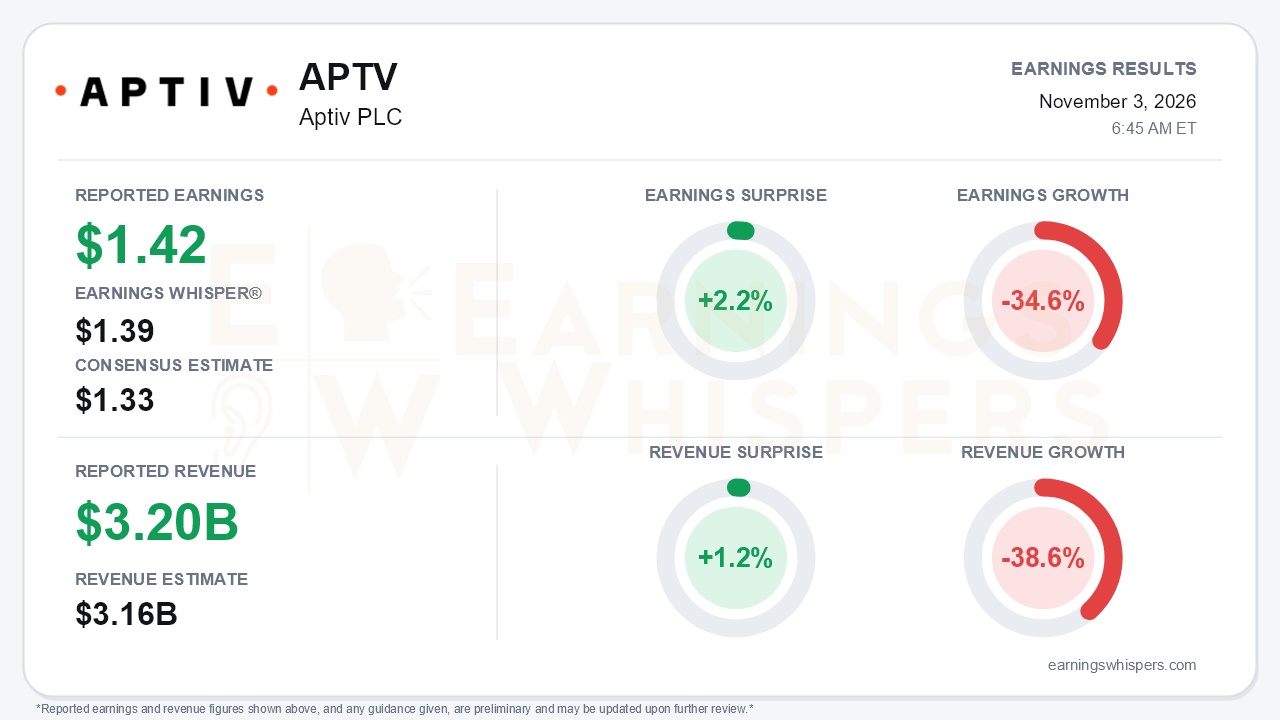
Aptiv (NYSE: APTV) beat third-quarter expectations, reporting earnings of $1.42 per share on revenue of $3.199 billion. That topped the $1.33 consensus and the $1.39 Earnings Whisper number by 2.2%, while revenue came in 1.2% above the $3.16 billion consensus. The beat matters less than what came with it. Management kept a twice-cut 2026 guide intact, trimmed free cash flow again, and issued a deliberately conservative 2027 preview that implies roughly flat organic growth. That is well below the 4-7% long-term framework the company reaffirmed as recently as the first quarter. That is the central tension: Aptiv cleared a bar it had already lowered, but its route back to growth has moved out another year.
The year-over-year comparisons need context. On Earnings Whispers' normalized basis, earnings fell 34.6% and revenue fell 38.6%. On the call, management described revenue as up 2% on an adjusted basis and EPS as down $0.06 from the prior year. The gap appears to reflect a much different comparison base. The call referenced spin-related cash drag, which suggests the company's perimeter has changed. Either way, the operating picture was soft beneath the beat. Adjusted EBITDA margin fell 140 basis points to 18%, a sharp turn from the 10-basis-point gain in the second quarter. Intelligent Systems was the weak spot, with revenue down 3% and margin down 240 basis points. Software and services revenue fell 11%. In the second quarter, management had called that a timing dip and promised a fourth-quarter rebound to high-single or double-digit growth. Instead, it now expects another year-over-year decline in Q4. That reversal deserves scrutiny because software was meant to be a key part of the mix-improvement story.
The guidance path explains why management's tone shifted from "momentum accelerating" in the first quarter to an explicitly "more cautious posture." The 2026 revenue guide started at $12.8-13.2 billion and was cut in Q2 to $12.6-12.8 billion. It was held at the midpoint this quarter with a narrower range. The free-cash-flow midpoint has slipped from $750 million to $675 million and now to $650 million. Over the same period, the estimated spin and inventory drag rose from $450 million to $500 million.
The 2027 preview is weighed down by several headwinds:
- **Memory and semiconductor inflation:** roughly $700 million, which management expects to pass through as revenue recoveries that dilute margins and tie up working capital. On the Q4 FY25 call, memory was described as having minimal impact.
- **German luxury OEMs:** a $250-300 million Intelligent Systems headwind lasting through the end of 2027.
- **Production assumptions:** flat vehicle production at best and down 2% at the low end, plus extra conservatism layered on top.
- **Supply and award timing:** management also flagged intermittent OEM production disruptions and the possibility that award cycles lengthen while price pass-throughs are negotiated.
The call did preserve a credible diversification story. Non-auto revenue grew 11%. Engineered Components grew 6% and expanded margin by 100 basis points. Q3 bookings of about $4 billion lifted the year-to-date total above $13 billion, and management reaffirmed its $20 billion full-year target. Non-auto bookings reached $3.8 billion year to date, more than double the prior-year pace. China bookings rose 30%, with more than 20% tied to export programs. The China export-platform share of Intelligent Systems revenue is expected to rise from about 10% to the mid-teens in 2027. Newer wins include:
- an expanded NVIDIA partnership in physical AI;
- a Samsung AI-RAN partnership through Wind River;
- a humanoid robot award in China;
- data center and energy-storage interconnect awards;
- an ADAS conquest win.
Capital return is the most concrete offset. Aptiv raised its target to 100% of free cash flow through at least the end of 2027, up from about 50% in Q2, with at least $650 million of buybacks in 2026. A portfolio composition review is due in the first quarter of 2027.
The market had already priced in much of the caution. As of the pre-report snapshot, shares stood at $44.23, down 12.3% since the open after the August report. That left them 25.8% below the 200-day moving average of $59.63. The stock set a 52-week low of $41.88 on October 23 and entered earnings only 5.6% above it, near the bottom of its inter-earnings range. Investor sentiment nonetheless improved modestly, from 0.14 to 0.23, and remained mildly positive. That suggests some investors were leaning toward capital return and the non-auto story. Earnings Whispers trend signals remain mostly negative, with sequential growth, momentum and AVWAP all deteriorating.
The bottom line is that Aptiv delivered a modest beat but a weaker forward narrative. Margins are compressing, software is still contracting, cash flow keeps getting trimmed, and the 2027 preview pushes reacceleration toward 2028. Bulls can point to doubled non-auto bookings, China export momentum, and a pledge to return all free cash flow. Bears have legitimate ammunition in a guide that keeps moving the wrong way. With the stock already near its lows, the debate now hinges on whether capital return and the portfolio review can bridge a flat year.
Read our earnings preview for Aptiv PLC: https://www.earningswhispers.com/article/APTV/21458
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 5 hours | |
| Oct-29 | |
| Oct-26 | |
| Oct-21 | |
| Oct-20 | |
| Oct-08 | |
| Oct-07 | |
| Oct-06 | |
| Sep-29 | |
| Sep-15 | |
| Sep-14 | |
| Sep-08 | |
| Sep-04 | |
| Aug-31 |
