Gevo's Canadian Credit Windfall Arrives, But Investors Want Proof The Core Can Carry 2027
Gevo enters its third-quarter report with an unusual problem: the quarter that should look like its best in years may also be the one investors trust least. Management said last time that roughly $17 million of banked Canadian Clean Fuel Regulation credits, already sold, would be recognized this quarter. That one-time boost should flatter the numbers. The real question is what remains once it is stripped out, because management has already conceded that 2027 adjusted EBITDA should be roughly flat with 2026 on that basis.
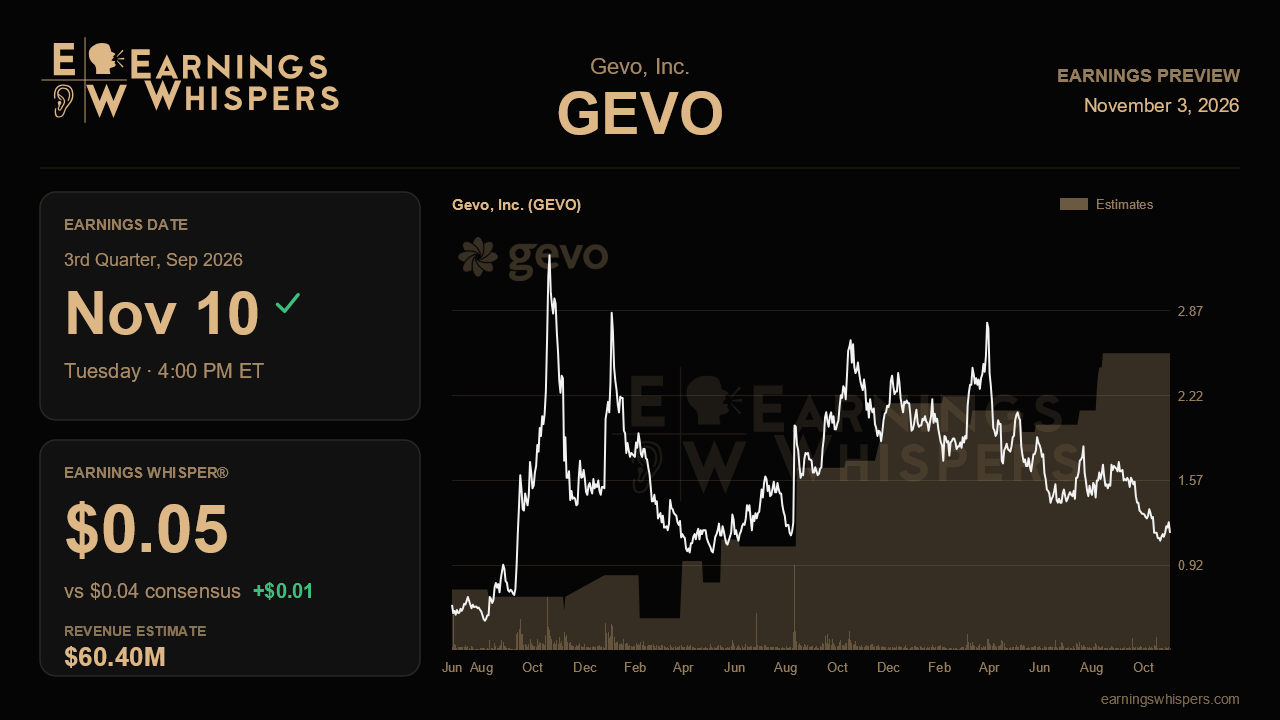
Wall Street expects earnings of $0.04 a share on revenue of $60.4 million. That would be a swing from a $0.03 loss a year ago and revenue growth of about 41%, a sharp step up from the $46.5 million reported last quarter. The Earnings Whisper of $0.05 sits a penny above consensus. That is a slight lean toward upside and not a meaningful raising of the bar. Much of the projected sequential jump appears tied to the Canadian credit sale, so a headline beat driven by that item alone would say little about the underlying business.
The more useful scorecard is management's own. Last quarter Gevo doubled its full-year adjusted EBITDA target to more than $60 million from about $30 million. The drivers were the newly approved Canadian pathway for low-carbon ethanol with carbon capture, 45Z tax credit monetization now expected above $70 million versus $52 million in 2025, a core carbon business run-rate lifted above $30 million a year, and cost cuts under its EBITDA Challenge program. Management also said it had sold $20 million of 45Z credits after the second quarter and collected about $16 million in cash. A reaffirmed or nudged-higher $60 million target, plus evidence that credit sales are tracking toward the $70 million mark, would validate the narrative. Any softening of that number just one quarter after doubling it would be damaging. Gross margin, which held near 43% in the first half, is another clean signal of whether the North Dakota core is strengthening on its own.
The growth projects deserve equal scrutiny. Debottlenecking the North Dakota plant to 75 million gallons a year was described as on time and on budget for year-end. The larger expansion to 150 million gallons, backed by Aura Energy financing, is targeted for completion in the second half of 2026. With the calendar running short, slippage would be hard to explain away. The same goes for the ATJ30 jet fuel project, whose estimated cost rose to $600 million from about $500 million. A final investment decision by year-end still depends on converting offtake term sheets into financeable contracts. Signed agreements would go a long way. Another quarter of the same gating language would reinforce doubts. Updates on the capital-light licensing model and on Verity, whose outside customer uptake management called slower than hoped, will help show whether new revenue streams are maturing.
The market has not given management much credit. Shares have fallen about 28% since the last report, against a 2.5% decline in the S&P 500. At $1.17, the stock trades well below its 200-day moving average of $1.72 and near the bottom of its post-earnings range of $1.09 to $1.76. That range has shifted noticeably lower than the prior quarter's. Sentiment has cooled as well, falling to a barely bullish 5.6% from 28.3% heading into the last report. That combination of a raised outlook and a sinking stock suggests investors are discounting the one-time nature of the gains and the funding risk around expansion.
The central issue is durability. Gevo can likely post a strong-looking quarter thanks to Canadian credits it has already sold. For the turnaround story to hold, management needs to show that recurring carbon revenue, 45Z monetization and plant expansions are on track to replace that windfall, and that ATJ30 financing is moving from talk to signatures.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Oct-29 | |
| Oct-28 | |
| Oct-22 | |
| Oct-14 | |
| Oct-08 | |
| Oct-01 | |
| Sep-16 | |
| Sep-14 | |
| Aug-26 | |
| Aug-06 | |
| Jul-22 | |
| Jul-16 | |
| Jul-15 | |
| Jun-23 |
