Compass Pathways Beats On A Warrant-Driven Loss As The COMP360 NDA Nears The Finish Line, While Launch Costs Climb And The Stock Has Fallen Nearly Half From Its September High
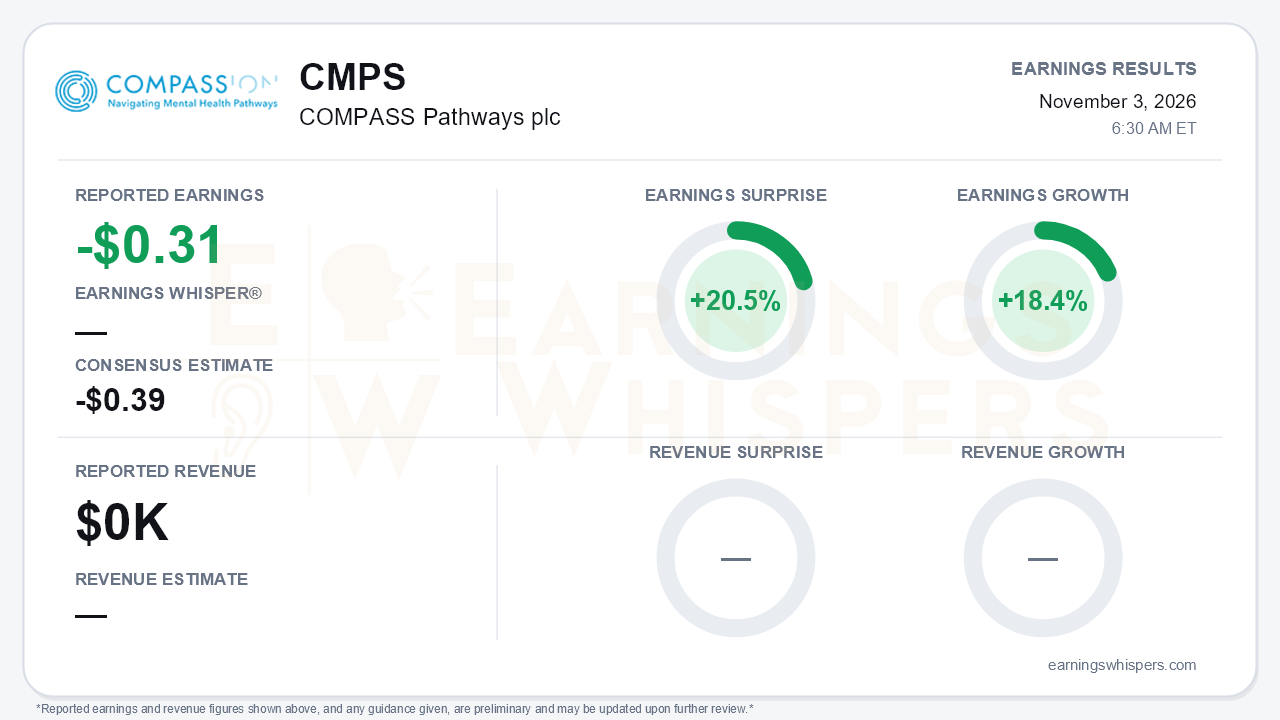
Compass Pathways reported a third-quarter diluted loss of $0.31 per share, ahead of the -$0.39 consensus. That is a 20.5% earnings surprise and 18.4% year-over-year earnings growth. Revenue was $0.0 million, as expected for a pre-commercial company.
The beat is the least important thing in this report. The quarter matters because COMP360's rolling NDA for treatment-resistant depression (TRD) is now about two weeks from completion. The National Priority Voucher carries a 1-2 month review target, which puts a potential approval much closer. The central tension is that the regulatory story keeps tightening while the stock moves the other way.
The quality of the earnings beat deserves scrutiny, because non-cash warrant accounting drives the bottom line almost entirely:
- **Net loss:** $9.8 million, versus $137.7 million a year ago.
- **Warrant effect:** a $40.8 million fair-value gain on warrant liabilities this quarter, against a $101.3 million loss in the prior-year period.
- **EPS gap:** basic EPS was -$0.07, while diluted EPS was -$0.31 once the warrant impact is adjusted for.
Beneath that noise, the operating picture went the other way:
- **Operating loss:** widened to $56.4 million from $40.5 million.
- **SG&A:** jumped to $33.0 million from $13.2 million as Compass built commercial infrastructure, market access, reimbursement capabilities and supply chain ahead of a potential launch.
- **R&D:** fell to $23.5 million from $27.3 million as Phase 3 TRD costs rolled off.
This is the expected cost profile of a company moving from clinical to commercial stage. But investors should not mistake a narrower net loss for a lower burn.
The balance sheet changed dramatically:
- **Cash:** $444.0 million, versus $149.6 million at year-end and $433 million at the end of the second quarter. Runway into 2028 was reaffirmed.
- **Share count:** rose to roughly 141.7 million from 96.1 million at year-end.
- **Debt:** climbed to $51.0 million from $31.6 million.
- **Warrant liabilities:** grew to $296.7 million.
The funding overhang is largely resolved, but existing shareholders paid for it in dilution.
The call showed steady execution rather than new guidance. The NDA timeline narrowed from "Q4" to "the next two weeks." Several launch-readiness markers improved:
- **Commercial team:** all non-field commercial roles are filled and field-force hiring is underway.
- **Treatment sites:** the interventional psychiatry network now exceeds 8,500 centers, up from over 8,000 in Q2 and roughly 7,300-7,500 in Q1.
- **State rescheduling:** commitments now cover more than 93% of the U.S. population.
Management's tone was more assertive. It cited market research suggesting about 90% of interventional psychiatrists would prescribe within the first year. It also argued that positioning in TRD gives Compass pricing and payer leverage over rivals aimed at major depressive disorder. Beyond PTSD, where a registration-enabling trial is enrolling, management named alcohol use disorder, bipolar II and OCD as expansion areas. It also committed to reporting launch KPIs in 2027. Launch guidance, however, stayed at the first half of 2027, the same as last quarter and later than the "launch ready end of 2026" framing from Q1.
Bears have legitimate ammunition:
- **Competition:** speculation about a competing psilocybin filing from Usona dominated Q&A. Management declined to comment, and analysts pressed on a two-player market and pricing.
- **Rescheduling:** DEA timing remains uncertain despite the White House executive order, and state actions must follow.
- **Reimbursement:** conversion from CPT Category 3 to Category 1 codes is expected to take 12-18 months, requiring patient support programs early in the launch.
- **REMS and buy-and-bill:** management described the REMS as complex and costly, label and REMS terms are not final, and buy-and-bill is not expected to be large at launch.
The market setup is more complicated than the surprise implies. Shares opened at $11.60 after the August report and hit a 52-week high of $15.87 on September 9. They then slid to an inter-earnings low of $7.54 on November 2 and sat at $8.41 on the eve of the report. That leaves the stock:
- down 27.5% since the prior post-earnings open;
- 47% below the September peak;
- about 19% below its $10.39 200-day moving average.
Investor sentiment improved meaningfully, from -0.30 to -0.10, but remains negative. The Earnings Whispers trend readings are mixed: momentum is positive, while sequential growth and AVWAP remain negative.
The bottom line is that Compass delivered what matters for a pre-revenue biotech: a nearly complete NDA, a potentially fast review path, a broader treatment-site network and cash into 2028. The EPS beat is mostly warrant accounting, and rising launch spending and heavy dilution are the real financial story. With the stock deeply off its highs, the next moves likely hinge on the NDA filing, FDA review timing, DEA rescheduling and clarity on any competing psilocybin entrant, not on reported losses.
Read our earnings preview for COMPASS Pathways plc: https://www.earningswhispers.com/article/CMPS/21663
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-14 | |
| Oct-02 | |
| Sep-30 | |
| Sep-16 | |
| Sep-15 | |
| Sep-10 |
