Cabot Beats On A Revenue Surge, But A Flat FY27 Outlook Exposes Tire-Contract Strain Beneath Performance Chemicals Strength
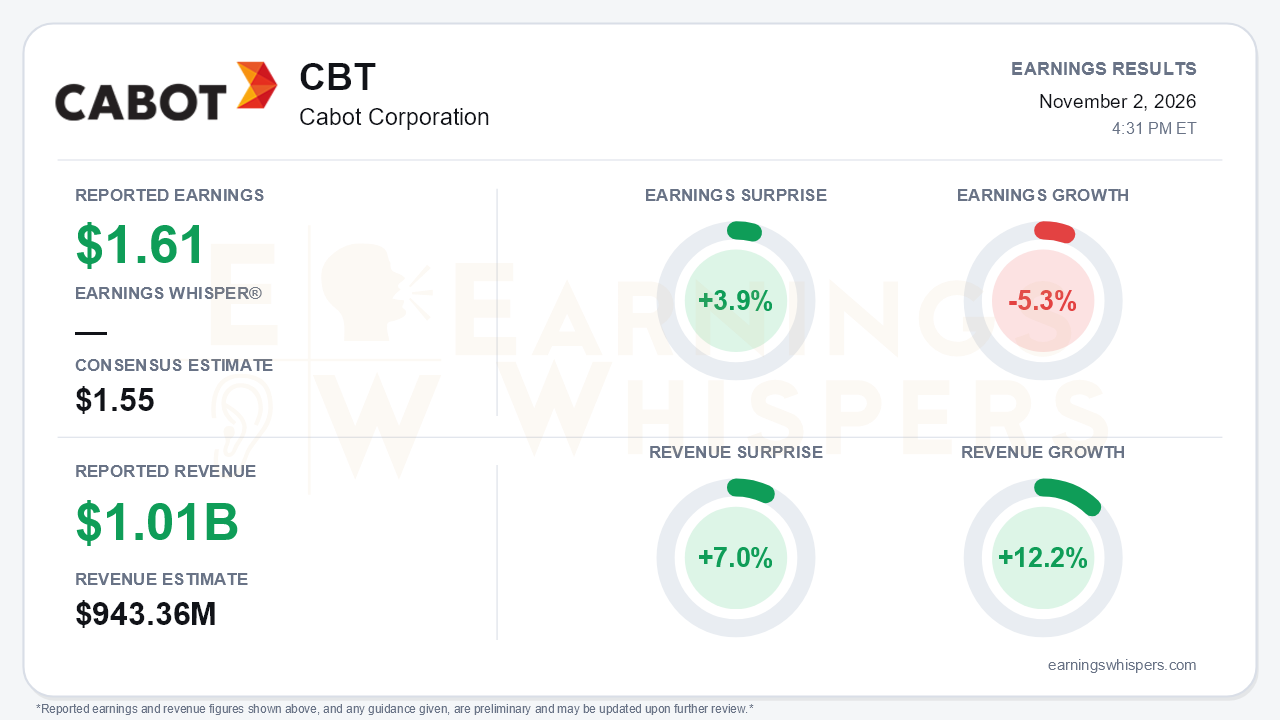
Cabot Corporation delivered a cleaner fiscal fourth quarter than expected. Adjusted EPS of $1.61 beat the $1.55 consensus by 3.9%, and revenue of $1.009 billion topped estimates by 7.0%, up 12.2% year over year. But adjusted earnings still fell 5.3% from a year ago. The first look at fiscal 2027, an Adjusted EPS range of $6.15 to $6.75, came in below estimates. Its $6.45 midpoint is essentially flat with the $6.42 the company just earned. That is the central tension: Cabot closed the year at the top of its guidance, yet management is effectively telling investors that 2027 is a year of treading water.
The quality of the beat deserves scrutiny. Revenue rose $110 million year over year, yet gross profit fell to $204 million from $220 million and operating income declined to $121 million from $137 million. Top-line strength did not translate into margin. Adjusted EPS also benefited from a share count that shrank to 51.9 million from 53.4 million after $146 million of fiscal-year buybacks. GAAP EPS of $1.25 rose sharply from $0.79, but that comparison mostly reflects a lighter load of certain items. Those items were $0.36 per share this quarter, mainly restructuring, versus $0.91 a year ago, which included heavy tax adjustments. For the full year, adjusted EPS fell to $6.42 from $7.25, and operating cash flow dropped to $421 million from $665 million as working capital absorbed cash.
The two segments are moving in opposite directions. Reinforcement Materials EBIT fell to $87 million from $119 million a year ago and from $97 million in the third quarter. Its EBITDA margin has slid every quarter of the fiscal year, from 23% to 18%. Volumes rose 5%, helped by Indonesian capacity and the Mexico acquisition. However, calendar 2026 customer agreements cut gross profit per ton, and the call confirmed lost European share behind a 7% EMEA volume decline. Performance Chemicals is the offset. Segment EBIT jumped 43% to $60 million, and EBITDA margin widened to 24% from 21% on favorable mix, lower costs and higher battery and specialty carbon volumes. Battery Materials finished at $43 million of EBITDA with a 26% margin, ahead of the roughly $40 million guided earlier in the year.
The forward picture explains why the beat did not settle the debate. Calendar 2027 tire contract negotiations are only about one-third complete. Management described outcomes as case-by-case, which accounts for the unusually wide $0.60 guidance range. First-quarter Reinforcement Materials EBIT is expected to be lower year over year. Performance Chemicals EBIT is guided down $6 to $8 million sequentially, and corporate costs and the tax rate are expected to rise. Battery Materials enters an investment year, with EBITDA guided only to the high-$40 millions as start-up costs absorb growth. On the positive side, the $50 million DOE grant is now finalized, reducing the net cost of the battery expansion, though the new capacity is not expected to drive more significant growth until fiscal 2028. Other potential tailwinds include:
- EU countervailing duties on Chinese tires due in December;
- AI-driven demand for fumed silica in electronics;
- the new CEO's explicit addition of M&A as a priority.
The macro backdrop is not helping. Global tire production is nearly flat, auto output is declining, and an interim CFO adds transition risk.
Investors had already turned cautious before this report, and sentiment deteriorated further. Earnings Whispers investor sentiment fell meaningfully, from -0.10 at the prior report to -0.46. The stock has been weak as well. At $75.72, shares are down 6.7% from the open following the August report and sit about 4.8% below the 200-day moving average of $79.52. The Earnings Whispers trend signals lean negative, with price, sequential growth and AVWAP readings all pointing lower. That fits a market that has been discounting Reinforcement Materials erosion more than rewarding Performance Chemicals gains.
Bears have legitimate ammunition here. Cabot's largest segment is losing margin and European share, and its most important pricing reset is still unresolved. The guidance range also leaves room for another down year at the low end. Bulls can point to disciplined execution, strong fourth-quarter cash generation of $143 million, $1.5 billion of liquidity and a funded battery growth runway. Their problem is that the payoff has slid largely into fiscal 2028.
The bottom line is that Cabot's fourth-quarter beat was real but narrow, driven by Performance Chemicals and buybacks while the tire-carbon franchise continued to erode. With fiscal 2027 guided flat and the outcome hinging on unfinished contract talks, the investment setup has shifted from execution to waiting. That leaves little in the guidance to reverse the souring sentiment until contract outcomes come into clearer view.
Read our earnings preview for Cabot Corporation: https://www.earningswhispers.com/article/CBT/21374
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-13 | |
| Sep-17 | |
| Sep-15 | |
| Sep-11 | |
| Aug-12 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-30 | |
| Jul-10 |
