KORU Medical Must Prove Its Margin Story Can Outrun A Slipping Revenue Ramp
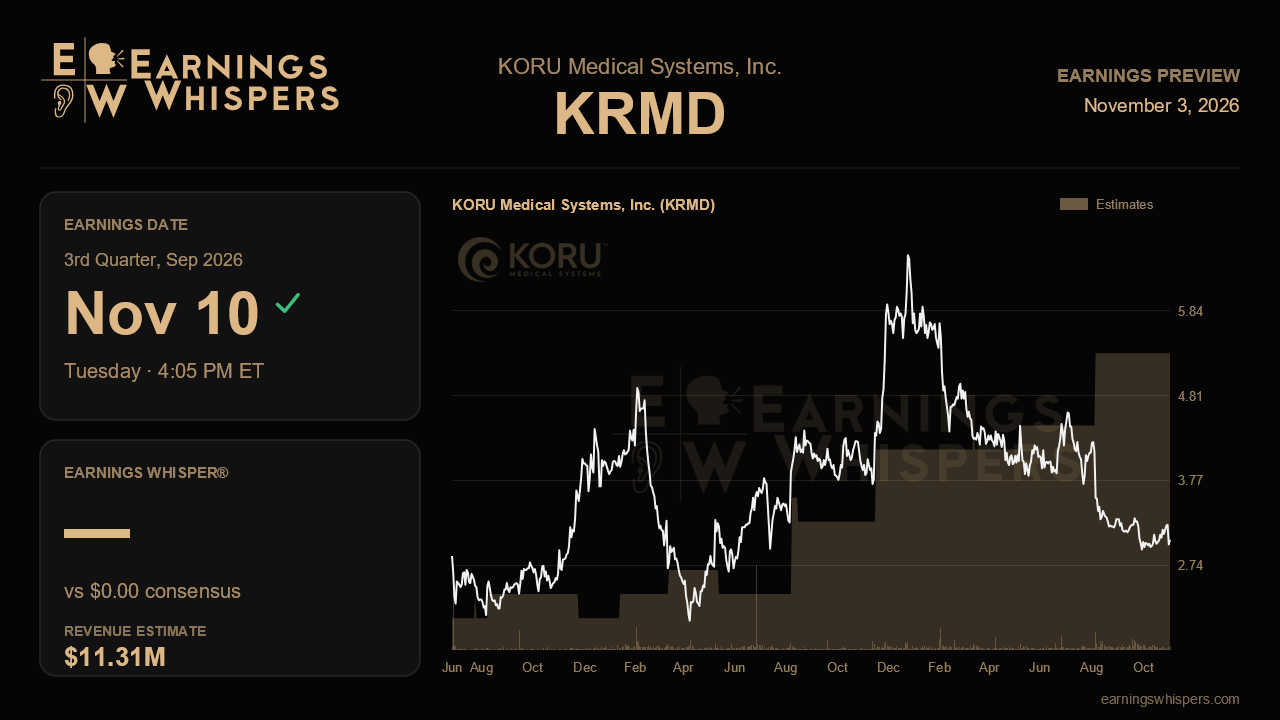
KORU Medical Systems heads into its third-quarter report with an awkward split personality. Last quarter the subcutaneous infusion specialist posted its first positive net income since 2019 and raised its gross margin outlook, yet it also trimmed its revenue range, pushed a key international opportunity into 2027 and withdrew its US filing for the oncology drug Fesgo. The stock has since fallen about 21%, so the question for Tuesday's after-the-bell release is whether the profitability gains are durable enough to offset a growth story that has lost some of its urgency.
The Street is looking for revenue of about $11.3 million, up 8.7% from $10.4 million a year ago, and roughly breakeven earnings per share. The headline 100% EPS growth figure simply reflects a move from a two-cent loss to zero, not a dramatic earnings surge. More telling is the sequential picture: the estimate sits below the $12.0 million KORU booked in the second quarter, which makes sense because management said international results that quarter were flattered by distributor stocking of pumps and consumables. A dip from Q2 would not by itself be alarming. A dip well below $11.3 million would raise doubts about how much of the recent strength was pull-forward.
Guidance adds an odd wrinkle. Management narrowed its 2026 revenue range to $47.5 million to $48.5 million from $47.5 million to $50.0 million, effectively lopping off the upper end. Full-year consensus of roughly $48.85 million still sits above that new ceiling, suggesting some estimates have not fully caught up to the reset. If KORU merely reaffirms its range, those figures may drift lower, and any hint that results are tracking toward the bottom of the range would be poorly received given how sentiment has soured.
The operating details matter more than the headline numbers. Domestic core revenue grew 12% in each of the first two quarters, ahead of a subcutaneous immunoglobulin market growing in the high single digits, and that recurring base of roughly 60,000 patients is the foundation of the bull case. Holding that pace would confirm KORU is still taking share. On margins, the company posted 65.1% in Q2 against a full-year guide of 62% to 64%, a target supported by a new multi-year supplier contract. Results near or above the top of that band, together with continued modest cash burn, would validate the idea that the business can self-fund. Year-end cash guidance of more than $7.5 million, lowered to reflect the connected-monitoring acquisition, is the line to check for erosion. The pharma services segment, which swung from a 166% gain in Q1 to a 35% decline in Q2, remains a wild card, especially with Biogen's acquisition of Apellis potentially disrupting trial timing.
Investors will also want clarity from new CEO Adam Kalbermatten on the catalysts that slipped. That means an update on alternative oncology molecules after the Fesgo withdrawal, progress on the pending deferoxamine 510(k), the timeline for secondary immunodeficiency trial endpoints expected within 12 to 18 months, and whether European prefilled-syringe conversions are genuinely on track for 2027 rather than drifting again.
The market is braced for disappointment. Sentiment has flipped from mildly bullish before the last report to firmly bearish, and shares at $3.05 sit well below the 200-day moving average of $4.01 and closer to the post-earnings low of $2.86 than the high of $3.89. That whole range sits beneath the prior quarter's trading band. Expectations are low, but credibility is the real issue. If domestic growth holds, margins stay elevated and management avoids another downward nudge to guidance or catalyst timing, the narrative of a steadier, profitable infusion franchise remains intact. Another round of slippage would make it hard to argue the reset is finished.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| Oct-20 | |
| Aug-06 | |
| Aug-05 | |
| Aug-04 | |
| Jul-29 | |
| Jul-15 | |
| May-18 | |
| May-06 | |
| Apr-16 | |
| Mar-13 | |
| Mar-12 | |
| Mar-12 | |
| Mar-12 | |
| Mar-11 |
