Madrigal Turns Its First Profit On Rezdiffra Strength, But Slowing Growth Rates And 2027 Pricing Pressure Keep The Debate Alive
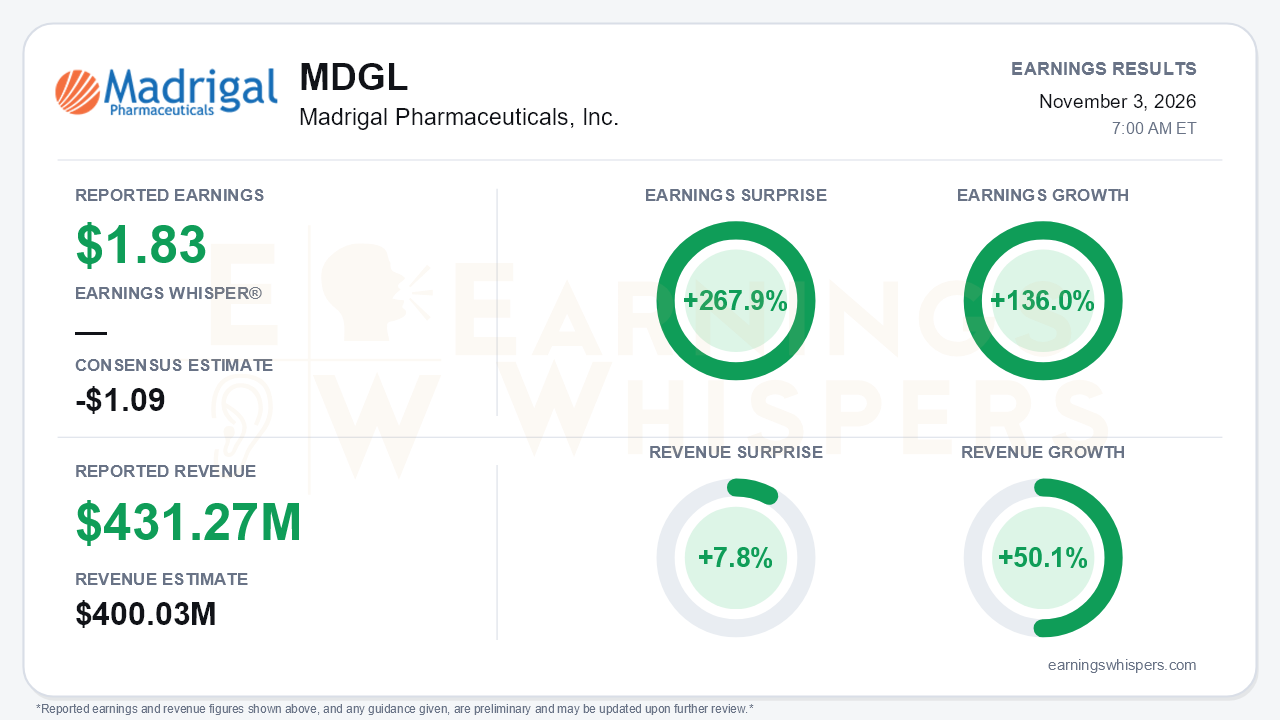
Madrigal Pharmaceuticals delivered the quarter that bulls have been waiting for. The company reported diluted earnings of $1.83 per share against a consensus estimate calling for a loss of $1.09, a 267.9% surprise. It was Madrigal's first profitable quarter. Revenue of $431.27 million beat the $400.03 million consensus by 7.8% and grew 50.1% year over year, all of it from Rezdiffra. Earnings grew 136.0% from a year-ago loss of $4.01 per share. Net income was $55.4 million, compared with a $57.9 million loss in the second quarter and a $94.4 million loss in the first. The central tension is that the profit arrived earlier than management itself had expected. Yet the year-over-year growth rate keeps slowing, and management openly cautioned that profitability may not stick.
The quality of the quarter is better than the comparison to last year might suggest, though it deserves context. Total operating expenses fell to $375.3 million from $401.2 million. However, the prior-year period carried a one-time $117.3 million upfront business development charge in R&D. SG&A rose 27% to $265.7 million as Madrigal funded its endocrinology field force expansion and a direct-to-consumer campaign. The profit therefore came from revenue outrunning a still-growing cost base, not from cost cuts, which is the healthier version of an inflection.
Royalty-driven cost of sales was $37.8 million, leaving product margins comfortably above 90%. Cash rose to $961.8 million from $838.9 million at the end of June, and operating cash flow has now been positive for two straight quarters. Trade receivables have climbed to $227.4 million from $134.5 million at year-end, roughly in step with the sales ramp but worth monitoring.
The call reinforced that demand is accelerating even as reported growth percentages decelerate. Year-over-year revenue growth has slowed from 127% in the first quarter to 71% in the second and 50% in the third, a function of tougher comparisons. Sequentially, the business sped up. Sales rose about 18% from $364.3 million in the second quarter, and the annualized run rate now exceeds $1.7 billion. Active patients reached 55,850, up from 49,000 in June and 36,250 at the end of 2025, with net additions holding steady at roughly 6,850.
Management also improved several key assumptions. It now expects 2026 gross-to-net at the low end of its mid-to-high 30s range, after starting the year at "high 30s." It trimmed R&D to "nominally lower" than 2025. It lifted its view of the diagnosed F2-F3 market to more than 530,000 patients, growing more than 30% this year, versus the "double-digit" framing on earlier calls. Notably, in the first quarter the CFO had said Madrigal would not be profitable in 2026.
The longer-term story centers on compensated cirrhosis (F4c). Management raised the addressable F4c population to 360,000 from 245,000. It narrowed the MAESTRO-NASH OUTCOMES readout to late 2027 and unveiled MAESTRO-CSPH, a second Phase 3 outcomes trial of more than 2,000 patients slated to start in the first half of 2027. Management also argued that competing F4c programs have been enlarged and delayed, with the earliest potential entrant not expected until 2030.
Bears still have legitimate ammunition. Gross-to-net is guided to worsen in 2027 toward the high end of the range as Medicare Part D contracts take effect. Fourth-quarter SG&A is guided higher, and the CSPH trial adds multi-year spending. Management flagged the usual first-quarter seasonal dip and said the company may move in and out of profitability. The F4c readout is event-driven, sits at the back end of 2027, and analysts continue to question whether placebo event-rate assumptions are achievable. Madrigal also provides no formal revenue guidance, although management said it is comfortable with 2027 consensus.
The market setup is more complicated than the surprise implies. Going into the report, shares were $431.16, down 14.7% from the open after the July report. The stock sat 13.7% below its 200-day moving average and just 1.4% above an inter-earnings low of $425 set on October 30, about 22% below the September 3 high of $552.08. Investors effectively sold the stock throughout a period of improving fundamentals.
Investor sentiment nonetheless became more positive, rising from roughly neutral at 0.04 to 0.18, a meaningful but not euphoric shift. The Earnings Whispers trend readings are mixed. Sequential growth and momentum are positive, while price and AVWAP trends remain negative, consistent with a stock whose operating results have improved faster than its chart.
The bottom line is that Madrigal crossed a genuine milestone: Rezdiffra is a blockbuster, the company is profitable ahead of its own timeline, and demand indicators are still building. The beat is real, but it does not resolve the questions that drove the stock lower: decelerating year-over-year growth, a 2027 gross-to-net headwind, uneven near-term profitability and a binary F4c readout more than a year away. The quarter strengthens the fundamental case, and the debate now shifts to whether execution can keep outrunning those concerns.
Read our earnings preview for Madrigal Pharmaceuticals, Inc.: https://www.earningswhispers.com/article/MDGL/21496
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 27 min | |
| 48 min | |
| 3 hours | |
| 4 hours | |
| 4 hours | |
| Oct-27 | |
| Oct-26 | |
| Oct-20 | |
| Oct-15 | |
| Oct-06 | |
| Sep-16 | |
| Sep-02 | |
| Aug-20 | |
| Aug-14 | |
| Aug-12 |
