GrowGeneration's Margin Turnaround Faces A Tougher Comparison As Tariff Refund Lands
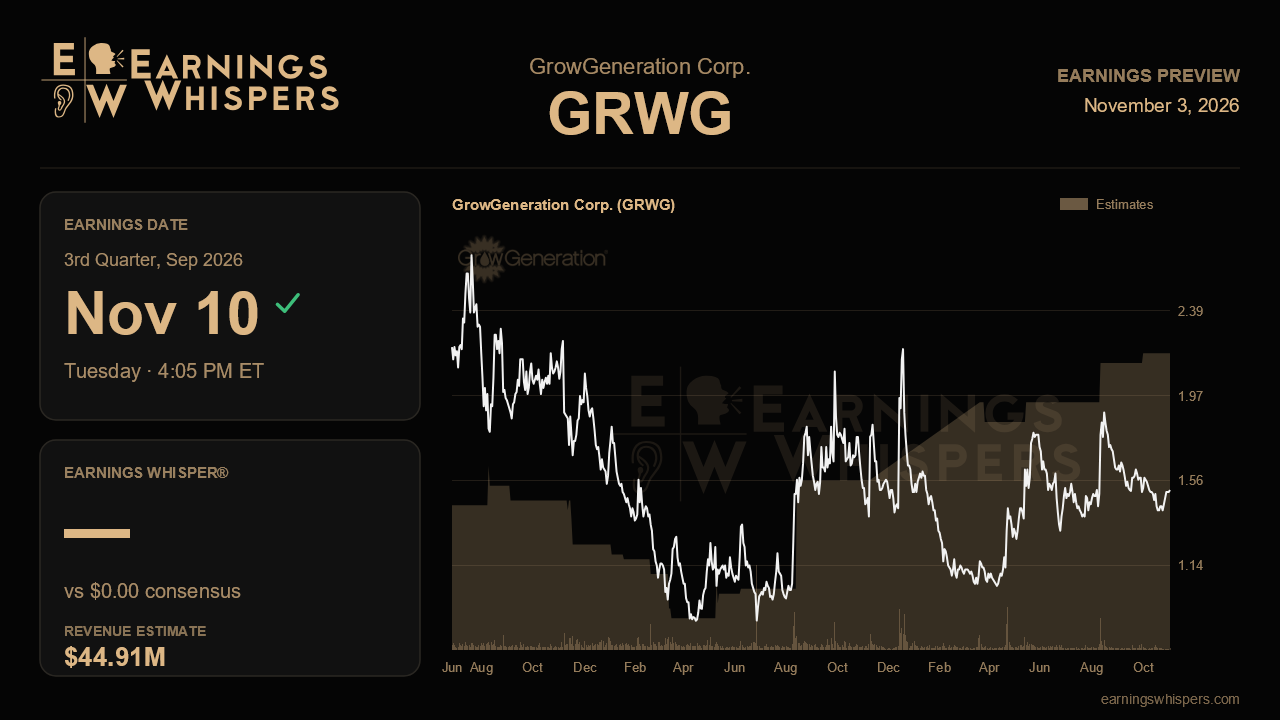
GrowGeneration enters its third-quarter report with an odd mix of momentum and doubt. Management raised its full-year adjusted EBITDA outlook last quarter for the first time in this turnaround, yet the stock has slipped since then. The coming release must show that a richer product mix and better margins can carry profits even as sales dip against a demanding year-ago quarter, and it must also show how much of the improvement comes from a one-time tariff refund.
The Street expects roughly breakeven earnings per share on revenue of about $44.9 million. That would be a solid improvement from the $0.04 loss a year ago, but revenue would fall about 5% from $47.3 million. The sales forecast sits just under the midpoint of management's reaffirmed $44 million to $46 million range. Estimates were once closer to $46.7 million, so analysts have moved down into the company's range rather than stretching above it. Management also kept its full-year revenue outlook at $162 million to $168 million, which leaves the fourth quarter carrying a meaningful share of the annual target.
The expected decline is the first test of last quarter's story. Revenue had grown year over year for three straight quarters. Management blamed the softer third-quarter guide on unusually lumpy sales of durable equipment in the prior-year period, not weaker demand. If that is right, the shortfall should trace to durables, while consumables and core cultivation sales hold steady or grow. A miss below $44 million, or signs of broader softness, would make the timing explanation harder to accept.
Margins matter even more. Gross margin jumped to 28.5% last quarter from 25.4% in the first quarter, helped by proprietary brands reaching nearly 40% of cultivation and gardening revenue. That level met the year-end goal six months early. Investors should look for evidence that the higher margin is durable rather than a one-quarter peak. With the brand target already reached, management's next step on mix becomes an open question. Two smaller items are also worth tracking. Rising transportation costs squeezed gross profit in the Storage Solutions business, and SG&A rose about 5% as the company added commercial sales staff. That spending needs to start producing revenue.
The tariff refund complicates the quarter. Management expects to book more than $2 million from it in the third quarter. That is large relative to a full-year EBITDA target of $2 million to $3 million and to the $1.3 million of adjusted EBITDA earned in last year's third quarter. A clean report would separate the refund from operating results and still show positive underlying EBITDA. If the beat depends mostly on the refund, the case for a lasting earnings recovery gets weaker. The company may also update investors on the pending Schedule III ruling and its buyback, which has used $1 million of a $10 million authorization at about $1.38 per share.
Sentiment has shifted sharply. Readings have moved from slightly bearish before the last report to clearly bullish now. The stock has not followed: shares have fallen 9.6% since the last report, trailing the S&P 500 by nearly 7 percentage points. At $1.51, the stock sits above its 200-day moving average of $1.41 but in the lower part of its post-earnings range of $1.39 to $1.98. That leaves room for a rerating if the numbers hold up, without suggesting the market has already priced in good news.
The key question is whether GrowGeneration can stay profitable on falling sales once the tariff refund is set aside. Steady gross margins near last quarter's level, a revenue decline clearly tied to durables, and a reaffirmed or higher EBITDA outlook would support the turnaround story. Margin slippage or a guidance raise that rests mainly on the refund would suggest the improvement depends more on one-time help than on lasting changes in the business.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Oct-28 | |
| Oct-08 | |
| Sep-02 | |
| Aug-17 | |
| Aug-12 | |
| Aug-11 | |
| Aug-11 | |
| Aug-10 | |
| Jul-28 | |
| Jul-07 | |
| Jun-23 | |
| Jun-22 | |
| May-27 | |
| May-13 |
