Keurig Dr Pepper Matches The Whisper As JDE Peet's And Refreshment Beverages Offset A Second Cut To Legacy Coffee Expectations
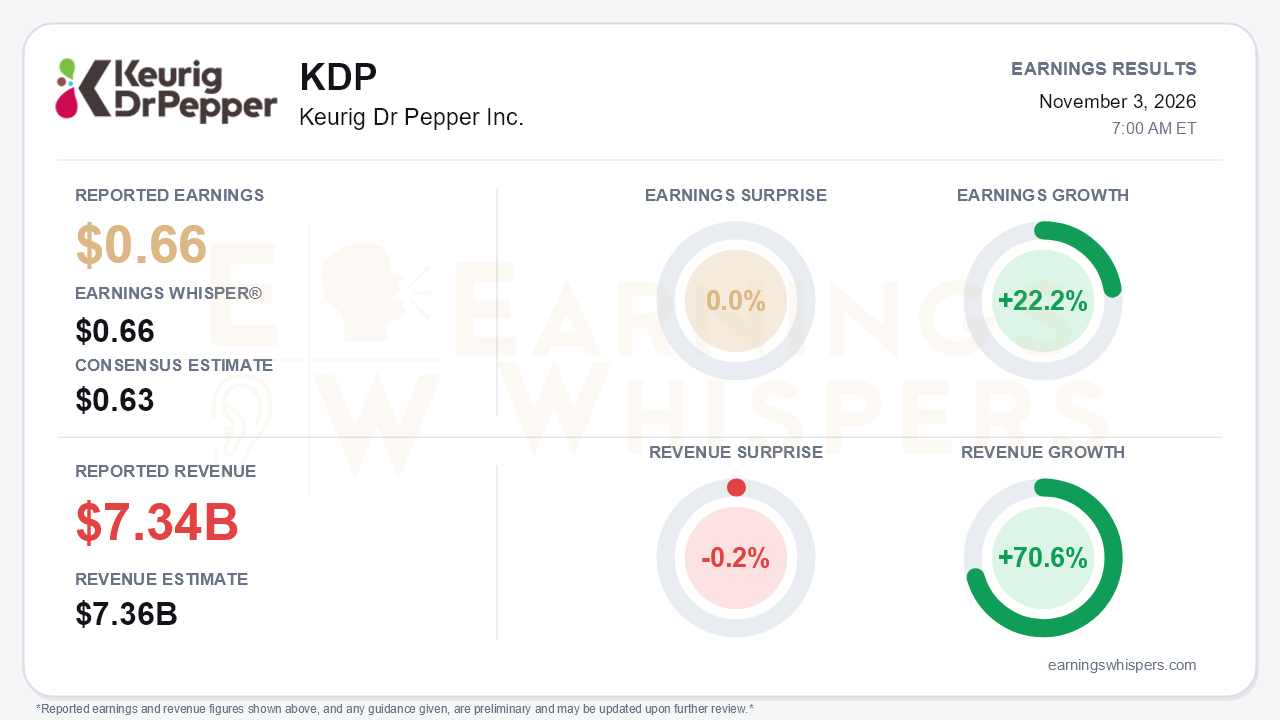
Keurig Dr Pepper delivered adjusted earnings of $0.66 per share in the third quarter. That was $0.03 above the $0.63 consensus and exactly matched the $0.66 Earnings Whisper number, so the result landed in line with what the market was actually looking for. Adjusted EPS grew 22.2% year over year. Revenue rose 70.6% to $7.344 billion, but that was 0.2% below the $7.36 billion consensus. Management reaffirmed full-year guidance for net sales of $25.9-$26.4 billion and low-double-digit constant-currency adjusted EPS growth. The headline is steady, but the composition of the outlook changed. JDE Peet's and refreshment beverages are now carrying more of the load, while the U.S. coffee recovery promised last quarter has slipped again.
The quality of the beat deserves scrutiny. A $99 million tariff refund, worth roughly 5 cents per share according to the call, flowed through both GAAP and adjusted operating income. Without it, adjusted EPS would have landed closer to the low $0.60s, below consensus. GAAP diluted EPS of $0.59 rose 20.4%. That figure absorbed heavy acquisition, integration and amortization costs, partly offset by a $400 million gain on the sale of an equity method investment tied to the Chobani transactions. The revenue surge is overwhelmingly acquisition-driven, since JDE Peet's contributed $2.6 billion of wholly incremental sales. The consolidated adjusted operating margin fell to 22.7% from 25.3%, mostly because JDE Peet's runs at an 18.1% margin. Interest expense more than doubled to $474 million on a GAAP basis, and the company is now also paying out to non-controlling interests and preferred investors. That explains why 52.5% adjusted operating income growth translated into only 22% EPS growth.
Beneath the consolidation noise, legacy KDP improved. Legacy net sales grew 8.6% versus 7.3% in the second quarter, with volume/mix of 6.5 points compared with 3.1 points last quarter. U.S. Refreshment Beverages posted a 10.9% sales gain, its eighth straight double-digit quarter. Energy share crossed 10% from 9% in Q2, GHOST became a $1 billion brand, and Dr Pepper Zero exceeded $1 billion in annualized retail sales. Even so, that segment's adjusted margin slipped to 29.1% from 29.8%, as heavier marketing and logistics pressure from energy and resin costs ate into the gains. JDE Peet's adjusted operating income climbed to $480 million from $414 million, which management had previously called the high-water mark. That improvement lifted the segment's EPS accretion forecast to 7-8 points from 6-7.
U.S. Coffee is where bears have legitimate ammunition. Segment sales turned positive at +2.7% after declines of 3.2% and 2.3% in the prior two quarters. Brewer shipments jumped 16.7%, and pods were up 0.3% after falling 11.6% in Q2. However, net price fell 4.2 points as moderating green coffee costs were reinvested in promotion. Management also described the single-serve category as softer than expected, with consumers trading to roast-and-ground, whole bean, instant and private label. Adjusted operating income was slightly down excluding the tariff refund. The second-half recovery that was framed as "significantly improved" in Q2 is now "more gradual." That forced a cut in legacy EPS growth guidance to 3-5% from the 4-6% held since late 2025. The JDE Peet's sales contribution was also trimmed to $8.3-$8.4 billion from $8.5-$8.7 billion on pass-through price cuts, and the expected currency tailwind was halved to about half a point.
The balance sheet story improved more decisively than the earnings story. Free cash flow reached $1.01 billion versus $714 million in Q2, and pro forma leverage fell to 4.1x from 4.4x at midyear. The Chobani monetization, about $925 million pre-tax including the Allentown facility sale, is earmarked for debt paydown. Management lowered its interest expense guidance to $1.09-$1.11 billion. The appointment of Russ Torres as future CEO of Global Coffee Co. advances the separation. However, management now explicitly caveats the timing as subject to market conditions.
The market setup is more demanding than the in-line print implies. Shares entered the report at $36.82, up 13.3% from the open after the August report and 22.6% above the 200-day moving average. The stock had rallied about 28.5% from its August 11 low to sit within 0.4% of a 52-week high set the day before earnings. Investor sentiment improved from -0.09 to -0.02 but remains essentially neutral. That suggests the rally ran ahead of any genuine shift in conviction. Price and sequential-growth trend readings are positive, while momentum is neutral.
The bottom line is that KDP delivered what the whisper required and held its full-year targets, but it did so with help from a one-time tariff refund and a stronger JDE Peet's contribution that masked another downgrade in U.S. coffee. Refreshment beverages, cash flow and deleveraging give the separation thesis a credible foundation. With the stock pressing against its highs, however, investors will need evidence that single-serve coffee can recover without further price reinvestment.
Read our earnings preview for Keurig Dr Pepper Inc.: https://www.earningswhispers.com/article/KDP/21490
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 4 hours | |
| 4 hours | |
| Oct-29 | |
| Oct-26 | |
| Oct-22 | |
| Oct-16 | |
| Oct-16 | |
| Oct-14 | |
| Oct-12 | |
| Oct-12 | |
| Oct-10 | |
| Oct-09 | |
| Oct-08 | |
| Oct-08 |
