AH Realty Trust Beats On FFO And Raises Guidance Again, But Rising Interest Costs And Thin Dividend Coverage Cloud Its Cleaner Story
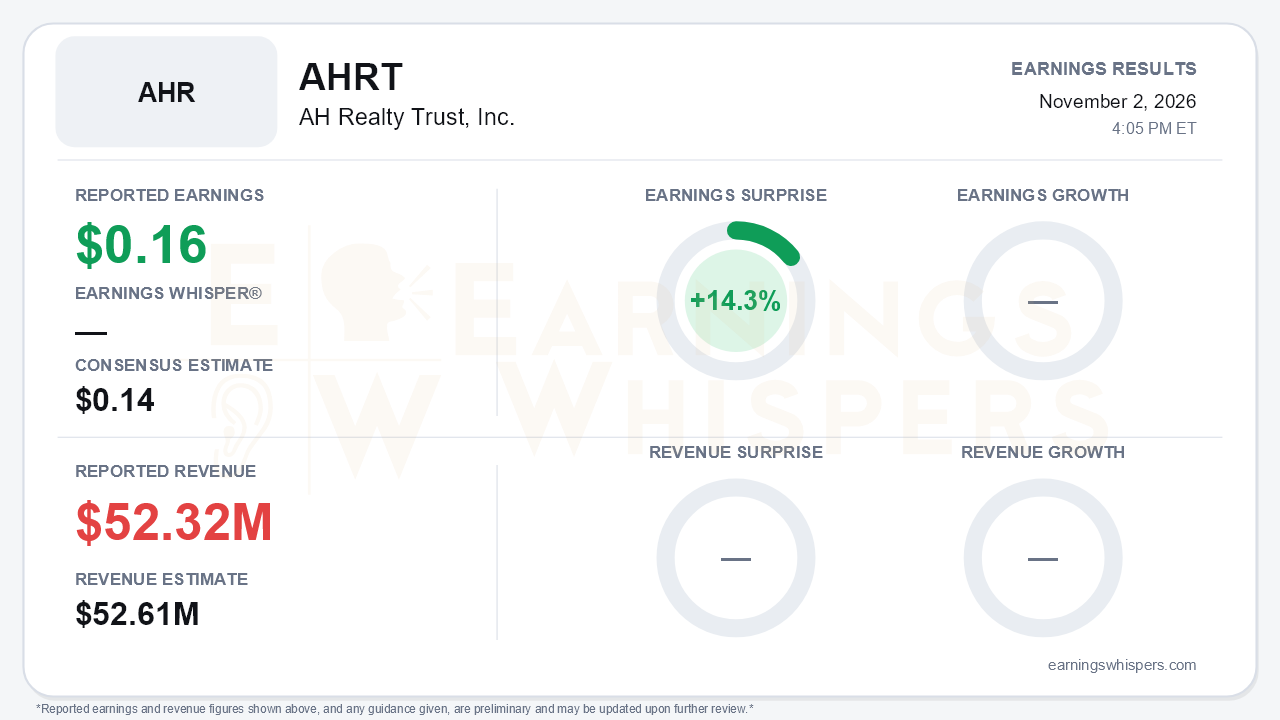
AH Realty Trust delivered the quarter a newly simplified REIT needed to show. FFO, as adjusted, came in at $0.16 per share, 14.3% above the $0.14 consensus. Management raised full-year 2026 guidance for the third straight quarter, to $0.57 to $0.59. The progression across the year is clear: the range opened at $0.51 to $0.55, moved to $0.53 to $0.57 after the second quarter, and now sits 11.5% above the original outlook. Revenue of $52.32 million missed consensus by 0.5%, a small miss that largely reflects a smaller asset base after this year's sales. The central tension is that the operating portfolio and balance sheet are clearly stronger, while the cash earnings that fund the dividend moved the other way.
The quality of the beat holds up better at the property level than at the per-share level. Same-store cash NOI rose 6.8% in retail and 5.2% in office, a blended 6.1%, up from 5.3% in the second quarter. New-lease cash spreads were strong, at 16.5% in retail and 23.3% in office. Several sources of upside are less repeatable, however:
- percentage rent;
- real estate tax appeal savings;
- lower-than-expected bad debt;
- a share count that fell to 97.3 million from 102.1 million a year ago.
FFO, as adjusted, improved sequentially from $0.14 in Q2 and $0.15 in Q1, but it remained below the $0.17 posted in the year-ago quarter, partly because of lower termination fees and higher stock compensation and IT costs. On a GAAP basis, the company lost $0.07 per share versus a $0.04 loss a year earlier. That loss included a $3.4 million impairment on its Gainesville multifamily assets, which investors should view as cleanup rather than core erosion.
The call reinforced that the transformation is essentially done. Eleven of 13 multifamily sales have closed, the real estate financing book has been exited, and general contracting is gone. The October refinancing and credit-facility recast pushed weighted average debt maturity from about 2.0 years to roughly 4.4 years, with no material maturities until 2029. Management said debt will be fully fixed or hedged once the remaining dispositions close. Leverage of 7.1x, down from 8.3x in Q1, is guided to about 6.4x by year-end, inside the 5.5x to 6.5x target. Management's message shifted from execution to organic growth, pointing to about $6.5 million of signed-not-occupied rent, mostly expected by mid-2027, plus 12 identified redevelopment and outparcel opportunities.
Bears have legitimate ammunition, though, and most of it sits below FFO.
- **Dividend coverage:** AFFO per share slid from $0.19 to $0.18 to $0.15 over the year, pushing the payout ratio from 72% to roughly 97.5%.
- **Interest costs:** Refinancing low-rate debt at around 6.4% lifted the weighted average interest rate to 5.2% from 4.3%. That headwind carries into 2027.
- **Renewal spreads:** Office renewal cash spreads collapsed to 1.5% from 21.6% in Q2, and retail renewals eased to 5.8%.
- **Property soft spots:** Town Center retail NOI fell 10%, One City Center occupancy dropped to 67%, and about 25,000 square feet of office move-outs is known for 2027.
- **Q4 outlook:** Full-year same-store guidance of 2.5% to 3.5% for retail and 3% to 4% for office implies a step-down from the third-quarter pace. Management attributed that to a tough comparison and a conservative bad-debt reserve for entertainment tenants at the Interlock.
- **Buybacks:** Repurchases slowed to 0.8 million shares as deleveraging takes priority.
The market setup is more complicated than the surprise implies. Investor sentiment remained positive but weakened sharply, falling from 0.83 at the prior report to 0.13. That suggests the enthusiasm around the restructuring had largely drained before this release. Shares entered the report at $6.40, down 7.9% from the $6.95 opening after the August report and about 3.6% below the $6.64 200-day moving average. The trend readings are mixed: momentum is positive, but AVWAP remains negative, consistent with a stock that has drifted lower even as guidance rose.
The bottom line is that AH Realty Trust has delivered on the hard parts of its transformation: exiting non-core businesses, extending maturities and hedging rate risk, while its core portfolio keeps posting mid-single-digit cash NOI growth and a third guidance raise. What investors now own, however, is a smaller, more expensively financed REIT whose AFFO barely covers the dividend. Its next leg depends on converting signed leases into rent before higher interest costs and 2027 move-outs offset them. The beat was real, but the burden of proof has shifted to 2027 organic growth.
Read our earnings preview for AH Realty Trust, Inc.: https://www.earningswhispers.com/article/AHRT/21365
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Oct-30 | |
| Oct-26 | |
| Oct-01 | |
| Sep-17 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-01 | |
| May-21 | |
| May-14 | |
| May-12 |
