Angel Oak Mortgage REIT Misses As A Rate-And-Spread Shock Cuts Book Value 11.5%, While Credit Holds And Dividend Coverage Thins
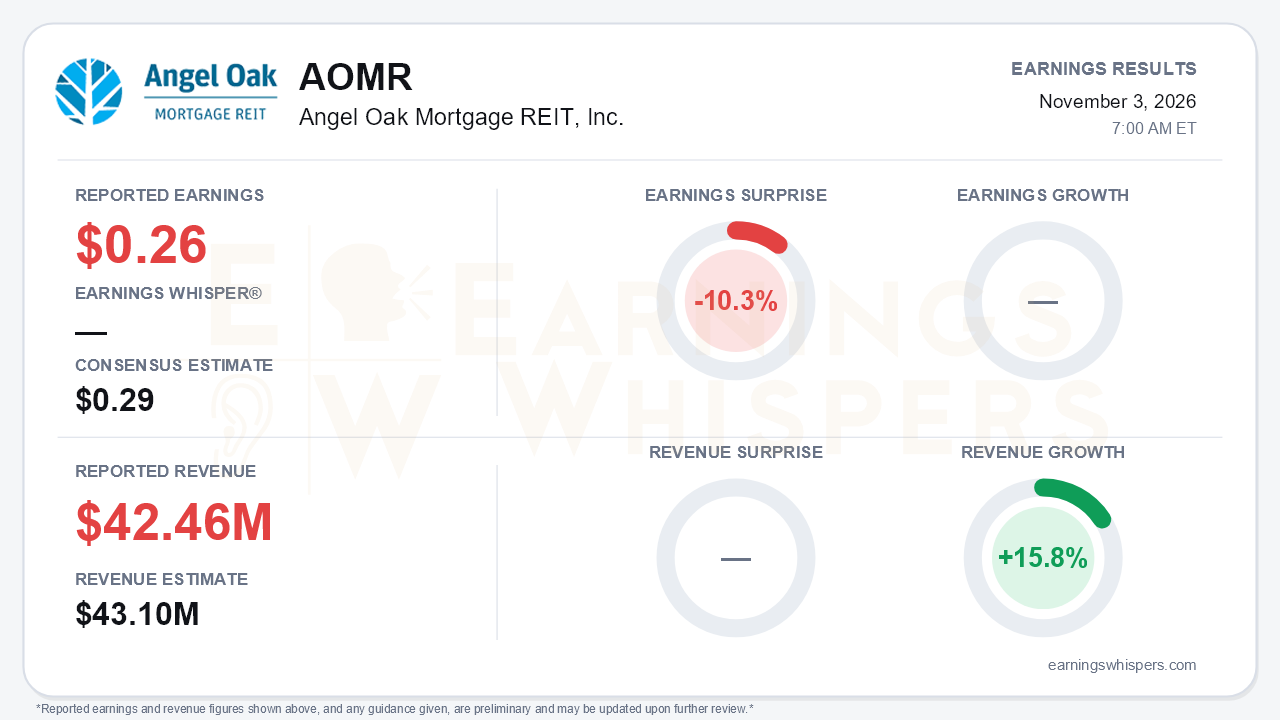
Angel Oak Mortgage REIT (NYSE: AOMR) reported third-quarter earnings of $0.26 per share, missing the $0.29 consensus by 10.3%. Revenue, measured as interest income, rose 15.8% year over year to $42.46 million but fell 1.5% short of the $43.1 million estimate. The earnings miss is the smaller story. The bigger one is the balance sheet. A rise in rates and wider spreads produced a GAAP net loss of $16.7 million, or $(0.72) per share, and cut GAAP book value 11.5% in one quarter to $8.97. For a mortgage REIT, that erosion matters more than a three-cent shortfall. It also raises the central tension of the quarter: credit performance held up while capital did not.
The figures need some reconciliation. The company reported Distributable Earnings of $6.4 million, or $0.28 per diluted share, slightly above the $0.26 normalized figure used for the consensus comparison. On either measure, earnings fall short of the newly declared $0.32 dividend. Distributable Earnings rose sharply from just $529,000 a year ago, but they fell from $9.0 million in the second quarter. Net interest income was $10.2 million, essentially flat year over year. Sequentially it kept sliding, from $12.1 million in Q1 to $10.7 million in Q2.
Interest income is growing, but interest expense is rising almost as fast, reaching $32.2 million versus $26.5 million a year earlier. Expenses also climbed:
- Total operating expenses nearly doubled to $6.0 million.
- That total includes $1.8 million of securitization costs.
- The bulk of the GAAP loss came from $22.6 million of net unrealized losses.
The call kept the operating machinery looking intact, even as the tone turned defensive. Loan purchases increased to $233.1 million from $204 million in Q2, at a 7.29% weighted average coupon and a 758 credit score. Ninety-plus-day delinquencies were about 2.1%, versus roughly 2.8% cited last quarter. Management also completed three securitizations across Q3 and October:
- 2026-3
- HB1
- AOMT 2026-6 ($250 million unpaid principal balance, 7.25% coupon)
The October deal cut recourse debt-to-equity to about 1.2x from 2.0x at quarter-end, and undrawn financing capacity is roughly $1 billion. CEO Sreeni Prabhu framed the damage as valuation pressure rather than credit deterioration, and the delinquency data support that view. Still, the tone has shifted noticeably. Late last year management was optimistic about a steepening curve. In Q2 it emphasized stable book value. Now it is explaining away mark-to-market losses.
The forward case depends on rates cooperating. Management expects new locks near 7.9% to 8% to restore its 15% to 20% securitized ROE target within about a month if rates hold. It also estimates book value has recovered about two points quarter-to-date. Both are management expectations, not reported results.
Bears have legitimate ammunition:
- AAA securitization spreads widened from 130 basis points on the 2026-3 deal to 160 basis points on 2026-6. That reverses Q2 commentary that spreads were tight and unreactive to rate volatility.
- Book value and retained bonds are not hedged against spread moves.
- Current returns on new investments sit near the dividend yield.
- Industry non-QM volumes are declining.
- HELOC purchasing was paused.
On the positive side, weaker competitors pricing wider and loan tapes trading at discounts could thin out the field.
The market had largely priced in a difficult quarter. Shares entered the report at $7.15, down 22.2% from the $9.19 open after the August report. They sat 15.4% below the 200-day moving average and just 2.7% above the $6.96 52-week low set on October 14. The stock had peaked on the day of the last report and declined almost steadily since. At $7.15, it trades at a meaningful discount even to the reduced $8.97 GAAP book value. Investor sentiment remained negative but improved modestly, from -0.25 to -0.18, suggesting expectations were already subdued. The Earnings Whispers trend readings are mixed, with price and AVWAP trends negative while sequential growth registers positively.
The bottom line is that Angel Oak's quarter was a market-driven setback rather than a credit event, but the damage is real. Book value has declined for four straight quarters. Net interest income keeps shrinking, and distributable earnings no longer cover the $0.32 dividend. The securitization pipeline, lower leverage and higher-coupon originations give management a credible path to better returns. That path depends heavily on rates and spreads stabilizing. With shares near their lows and below book, the setup rewards patience only if the promised Q4 recovery in returns and book value actually shows up.
Read our earnings preview for Angel Oak Mortgage REIT, Inc.: https://www.earningswhispers.com/article/AOMR/21456
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-02 | |
| Oct-26 | |
| Oct-20 | |
| Aug-11 | |
| Aug-04 | |
| Aug-04 | |
| Jul-24 | |
| Jul-21 | |
| May-05 | |
| Apr-21 | |
| Feb-26 | |
| Feb-25 | |
| Feb-25 |
