Sonos Faces A Margin Test As Memory Costs Threaten To Overshadow Its Growth Revival
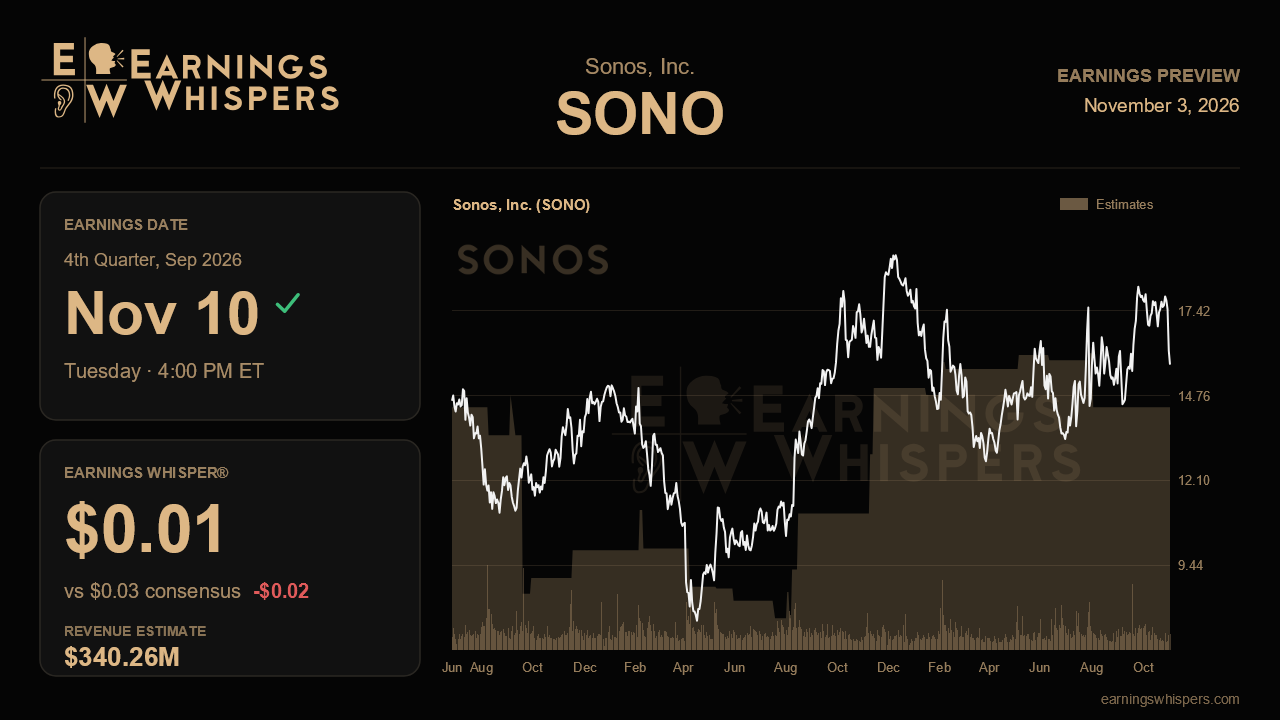
Sonos heads into its fiscal fourth-quarter report with a story that has quietly split in two. The top line is finally doing what management promised, with fiscal 2026 framed as the year the company returned to growth. Underneath that recovery, though, rising memory chip prices are eating into the gross margin that made this year's profit rebound so striking. The report due after the close on November 10 will show which half of that story deserves more weight heading into fiscal 2027.
Wall Street expects revenue of about $340.3 million, up roughly 18% from the $287.9 million Sonos posted a year ago. That is the fastest growth rate of the year on paper, but it needs context. The quarter includes an extra week, and it captures the first weeks of AMP Multi, the installer-focused amplifier that launched in late August. Management has already tempered expectations, describing the trend as momentum rather than ongoing acceleration. A figure near consensus would therefore confirm the recovery without proving that underlying demand is speeding up. The more useful signal will be whether the geographic expansion markets that posted double-digit growth earlier in the year, led by Asia-Pacific and EMEA, kept pace once the calendar boost is set aside.
Profit expectations are thin. Consensus calls for earnings of $0.03 per share, and the whisper number sits at $0.01. Two cents sounds trivial, but on a base this small it suggests the market is leaning toward a softer margin result. That would still be a big improvement on last year's loss of $0.20, though well short of the $0.14 earned last quarter. The gap reflects the main warning from the prior call. Memory costs were already a headwind of about 400 basis points year over year, and management said that pressure would grow into the fourth quarter. Its comments pointed to fiscal 2027 non-GAAP gross margin near 40%, roughly the low end of the fourth-quarter range and well below the 46% reached in the fiscal second quarter. A margin at or above the middle of that range would suggest Sonos is absorbing the hit better than feared. A print near 40% or below, without offsetting pricing or cost actions, would make the fiscal 2027 earnings outlook harder to defend.
Several other items will shape the reaction. The September launch event introduced Sonos's push into conversational computing and predictive intelligence, built on its base of 53 million connected devices in 17 million homes. Investors will want early detail on how these AI products will be priced and when they will ship, and whether they lift revenue per household or simply add spending at a time when AI labs are circling the same home hardware turf. Management's earlier pledge to hold operating expenses roughly flat in fiscal 2027 also matters more now, since cost discipline is the main buffer against weaker gross margins. Any update on the potential tariff refund of about $40 million, and on the handoff from departing CFO Saori Casey, could affect how much credibility the outlook carries.
The market has not given Sonos much credit for its beat-and-raise quarter. Shares are down 2.7% since the last report, while the S&P 500 is up 2.2%. At $15.73, the stock sits just above its 200-day moving average. That leaves it near the middle of its post-earnings range of $14.02 to $18.35, well short of any breakout. Sentiment remains modestly bearish, only slightly less negative than before the last report, which suggests skepticism has eased a little but not gone away.
The core question is whether Sonos can show that its revenue recovery is durable enough to outrun the memory-cost squeeze. Solid underlying growth, a gross margin that holds above the feared floor, and a credible fiscal 2027 framework with flat expenses would keep the turnaround narrative intact. Growth that leans mostly on the extra week, paired with margins sliding toward 40%, would shift the debate from recovery to profitability.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Oct-20 | |
| Sep-14 | |
| Sep-08 | |
| Sep-01 | |
| Sep-01 | |
| Aug-04 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-15 | |
| Jul-15 | |
| Jul-14 | |
| Jul-14 |
