Broadridge Tops A Low Bar As Recurring Growth Accelerates, But A Lower Tax Rate Flattered The Beat And Margins Fell 200 Basis Points
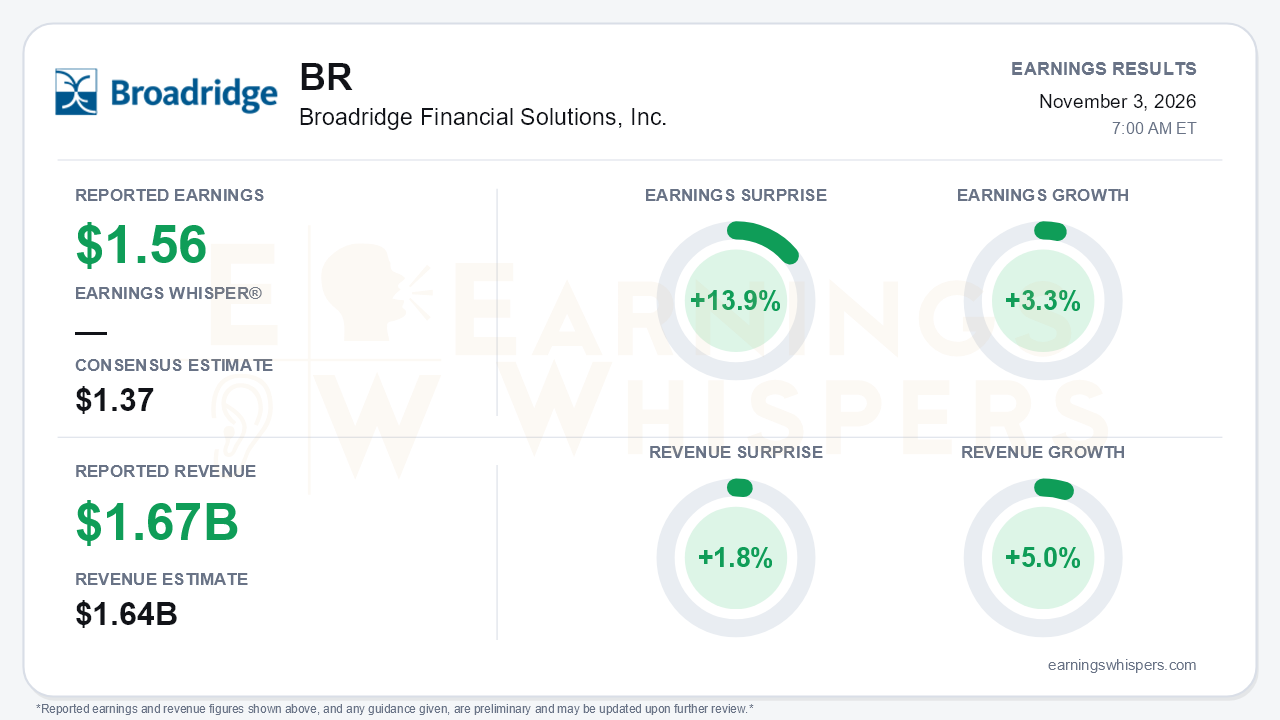
Broadridge Financial Solutions opened fiscal 2027 with a headline beat that looks larger than the underlying earnings improvement. Adjusted EPS of $1.56 topped the $1.37 consensus by 13.9% and grew 3.3% from a year ago. Revenue of $1.669 billion beat the $1.64 billion estimate by 1.8% and rose 5.0%. The more important signal is in the revenue mix. Recurring revenue grew 11% in constant currency, including 9% organic growth. That is up from 8% in the fourth quarter of fiscal 2026 and 6% in the third quarter. The central tension is that this top-line acceleration came alongside lower margins, flat adjusted net earnings, and an EPS gain that depended on taxes and buybacks.
The quality of the beat deserves scrutiny. Consensus had effectively penciled in a year-over-year decline from last year's $1.51, so the bar was low. Adjusted net earnings were flat at $178 million. The 3% per-share gain came from a roughly 3% lower diluted share count and an effective tax rate of 13.6%, down from 22.4%, which the company attributed to discrete tax benefits. Adjusted operating income fell 9% to $230 million, and adjusted operating margin compressed 200 basis points to 13.8%. GAAP results looked considerably worse. Diluted EPS fell 41% to $0.83 because of a $40 million non-cash mark-to-market loss on Canton digital asset holdings, which compares with a $46 million gain a year ago. A $15 million restructuring charge tied to AI and productivity-related workforce actions added to the GAAP decline. The main drag on profit was event-driven revenue, which fell 41% to $67 million as mutual fund proxy revenue dropped 63% against a record prior-year quarter. That pushed ICS pre-tax earnings down 18%.
The segment detail shows where the business is actually gaining strength. GTO pre-tax earnings jumped 47% to $99 million, and segment pre-tax margin widened to 19.1% from 14.6%. Capital Markets recurring revenue rose 17%, compared with 7% last quarter. That figure needs context, however: it includes 4 points from term licenses and 5 points from the CQG acquisition. On the ICS side, Regulatory revenue rose 17% on strong position growth:
- Mutual fund/ETF positions grew 16%, versus 2% a year ago.
- Equity revenue positions grew 11%, versus 7% a year ago.
Management raised its fiscal 2027 fund-position outlook to high single digits, from the mid-single-digit pace it had guided for the first half. Closed sales rose 10% to $36 million, and free cash flow improved to $76 million from $13 million. The CEO said the quarter made him "incrementally better" about the year.
Bears still have legitimate ammunition:
- **Trade volumes:** Internal trade volume growth slowed to 7%, from 15% and 16% in the prior two quarters.
- **Wealth:** Wealth and Investment Management grew 6% in constant currency, half of it from license revenue.
- **Data-driven fund solutions:** Organic growth was only 4%.
- **Margins:** Management expects similar margin pressure in the second quarter as event-driven comparisons and investment spending continue to weigh.
- **Regulation:** The ICI is pushing back on fees in connection with the SEC's e-delivery default proposal, a regulatory overhang for the core communications franchise.
Despite the stronger start, every fiscal 2027 target was simply reaffirmed:
- 6-8% recurring revenue growth
- About 21% adjusted operating margin
- 8-12% adjusted EPS growth
- $290-$330 million in closed sales
The forward catalysts are substantive. Broadridge agreed to provide the governance layer and digital transfer agency for NYSE's planned tokenized equity marketplace. It also added Kraken/Payward and is supporting a DTCC tokenization initiative, joining Ondo, Alpaca, and Galaxy from earlier calls. Other wins included a Korea Securities Depository proxy MOU, a global brokerage front-office mandate aided by CQG, and another Tier 1 wealth manager for its AI voting engine. U.S. 23x5 trading launches December 6. Management also expects interest rates to shift from headwind to tailwind in the second half. The December 8 Investor Day, where new fiscal 2027-2029 objectives will be presented, is the next clear test of whether the accelerating recurring growth translates into higher multi-year targets.
The market setup is more complicated than the surprise implies, because investors had already moved ahead of the report. Earnings Whispers investor sentiment improved from roughly neutral (-0.017) to modestly positive (0.12), a meaningful but not euphoric shift. Shares closed at $184.22 the day before the report. That was up 9.5% from the open following the August report and 11% above the 200-day moving average. The stock had rebounded 18.3% from its October 5 low and sat just 1.4% below its August inter-earnings high of $186.91. Price, momentum, and AVWAP trend readings are positive, while sequential growth is neutral. That pattern fits a stock that has rallied on expectations while near-term earnings growth remains modest.
The bottom line is that Broadridge delivered a better business quarter than an earnings quarter. Recurring revenue is accelerating, position growth and the tokenization pipeline are strengthening, and cash flow rebounded. However, the EPS beat rested on a low consensus bar, a sharply lower tax rate, and buybacks, while margins contracted and trade volumes cooled. With guidance only reaffirmed and shares entering the report near the top of their recent range, the burden shifts to the December Investor Day to show that the revenue acceleration can produce higher earnings growth.
Read our earnings preview for Broadridge Financial Solutions, Inc.: https://www.earningswhispers.com/article/BR/21464
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 7 hours | |
| 9 hours | |
| 9 hours | |
| 12 hours | |
| Nov-02 | |
| Oct-29 | |
| Oct-26 | |
| Oct-22 | |
| Oct-20 | |
| Oct-20 | |
| Oct-08 | |
| Oct-01 | |
| Oct-01 | |
| Sep-29 |
