Hillman Holds The Line On EPS And EBITDA, But A Negative Core Volume Turn Forces A Sales Guidance Cut
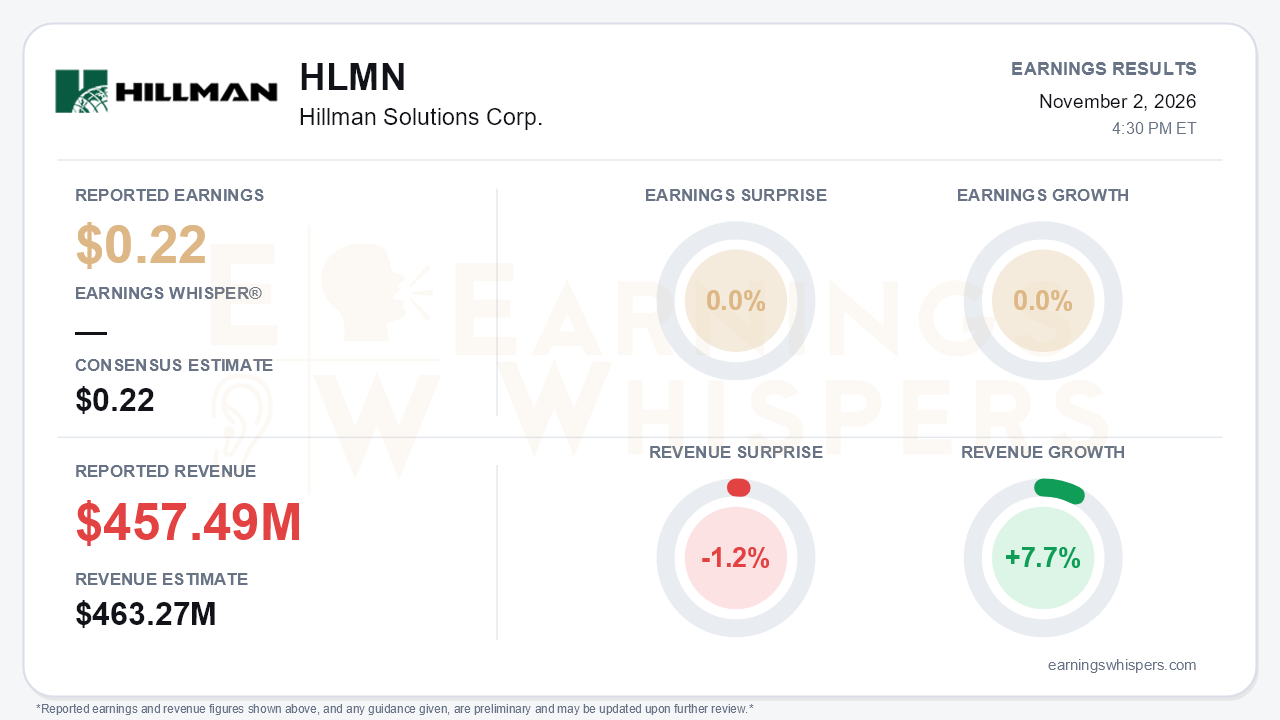
Hillman Solutions delivered adjusted earnings of $0.22 per share for the third quarter, matching the consensus estimate and flat year over year. Revenue rose 7.7% to a record $457.5 million but missed the $463.3 million consensus by 1.2%, and management narrowed full-year net sales guidance to $1.66-$1.68 billion from $1.67-$1.72 billion. The central tension is that the quarter's headline growth, record EBITDA, and reaffirmed profit guidance increasingly depend on acquisitions and margin repair. The organic business went backward. Core performance swung from +2% in the second quarter to -2% in the third, and total sales growth slowed from roughly 10% to 8%.
The quality of the quarter deserves scrutiny on two fronts. On a GAAP basis, net income fell to $6.3 million, or $0.03 per share, from $23.2 million, or $0.12. The gap reflects $13.5 million of refinancing costs and $8.6 million of transaction and integration expense tied to the Kanebridge deal and the earlier Campbell and Delaney acquisitions. Those items are reasonably classified as non-recurring, and adjusted EBITDA edged up to $90.2 million from $88.0 million. Even so, adjusted EBITDA margin of 19.7% was about 100 basis points below the prior year, and adjusted gross margin was down roughly 90 basis points. Free cash flow was the standout at $51.1 million versus $9.1 million a year ago. Part of that strength came from working capital: inventories released $62 million of cash year to date after consuming $54 million in the same period of 2025. That is a healthy normalization of tariff-era stock, but it is not an unlimited source of cash.
The call preserved a credible growth story beneath the soft volume picture. Sequentially, margins kept recovering as higher-cost tariff inventory worked through. Adjusted gross margin climbed from 45.6% in Q1 to 47.1% in Q2 and 50.8% in Q3, and management now expects about 48% for the year, above its original 46-47% outlook. Robotics and Digital Solutions was the clear bright spot. Growth accelerated from +6% to +11% to +19% over the three quarters, segment gross margin reached 79%, and the Minikey 3.5 rollout grew to about 4,800 machines, with completion at the top two customers slated for the fourth quarter. Pro new business added about 1.5 points to growth, and Canada grew 9% on new wins. On the soft side, Protective Solutions stayed weak on reduced promotional activity.
The guidance math is less reassuring than the reaffirmation suggests. Second-half market volumes came in below the modest improvement management had assumed in August. The roughly $285 million EBITDA target holds largely because Kanebridge is offsetting weaker organic volume. Kanebridge is the deal management described on the call as "Cambridge," a roughly $315 million purchase adding about $29-30 million of EBITDA that management says is outperforming. The price tailwind is also fading as 2025 tariff-driven increases lap, and Section 232 steel tariff adjustments are eating into tariff refunds. Management's preliminary 2027 framework calls for 8-12% growth. About 3-4 points of that would come from annualizing M&A and roughly 4 points or more from new business wins, with management explicitly assuming no macro help.
The balance sheet changed meaningfully. Net debt rose to $932.6 million from $665.8 million at year-end 2025. Reported leverage reached 3.4x trailing adjusted EBITDA, or about 3.1x pro forma for Kanebridge's full-year contribution, up from 2.4x. Management signaled that this limits near-term buybacks after $28 million of repurchases year to date, including shares bought at an average of $7.75 in the quarter. The refinancing pushes term-loan maturities to 2033, which reduces near-term refinancing risk.
Investor expectations were already subdued heading into the print. Earnings Whispers sentiment improved slightly from -0.42 to -0.37, a modest move that leaves it firmly negative. Shares at $8.39 are down 6.8% from the $9.00 open after the August report and sit only about 3% above the 200-day moving average of $8.12. The trend readings are mixed: price trend is negative while momentum and AVWAP are positive, consistent with a stock that has drifted lower but has not broken down.
The bottom line is that Hillman delivered an in-line quarter that looks better on profitability and cash than on demand. Margin recovery, accelerating robotics growth, pro wins, and an outperforming acquisition give bulls a real foundation. Bears have legitimate ammunition in the negative core trend, a lowered sales outlook, fading price, and leverage that has risen above 3x. The next leg depends less on tariff-margin repair, which is largely done, and more on whether new business wins can offset a market management itself expects to stay soft.
Read our earnings preview for Hillman Solutions Corp.: https://www.earningswhispers.com/article/HLMN/21396
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Nov-02 | |
| Oct-26 | |
| Oct-23 | |
| Oct-07 | |
| Sep-03 | |
| Aug-19 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Aug-03 | |
| Jul-22 | |
| Jul-13 | |
| Jun-17 | |
| Apr-29 |
