Vivo's Margin Momentum Faces A Skeptical Market As Light Plans Test Pricing Power
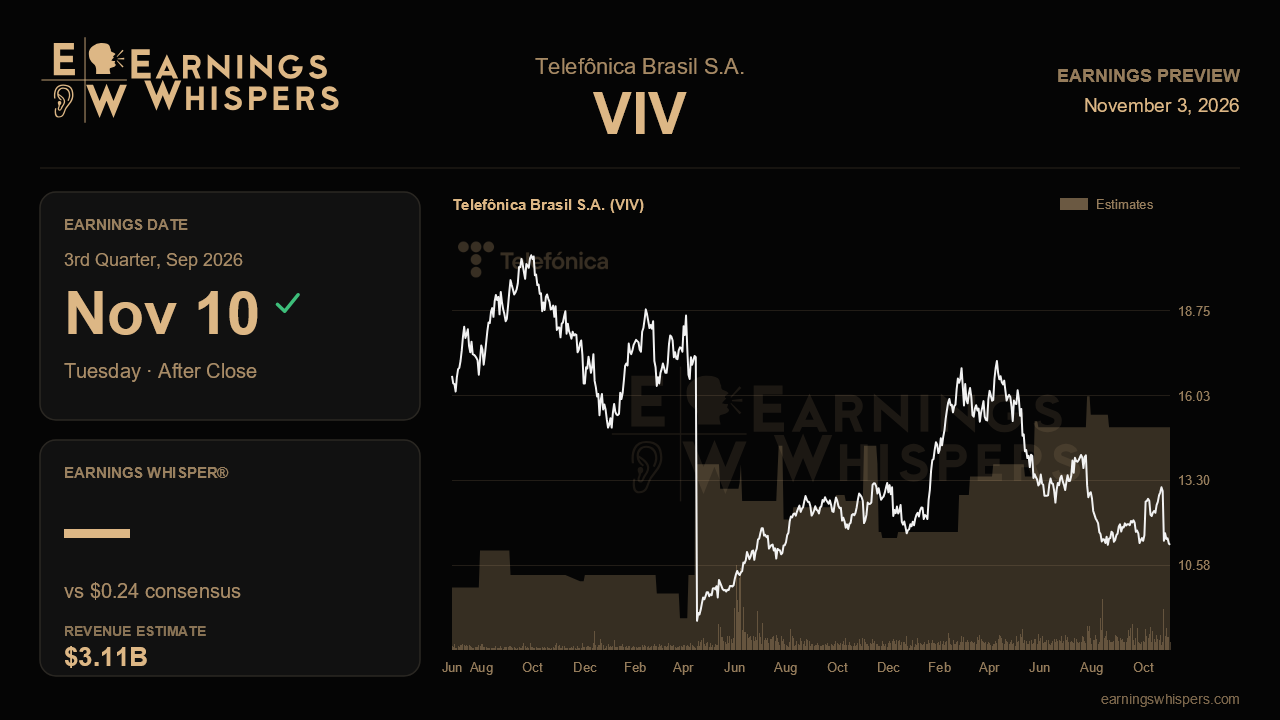
Telefônica Brasil enters its third-quarter report with an unusual disconnect. Last quarter, the company formerly known as Telesp delivered its first double-digit EBITDA growth in 11 quarters, a record mobile ARPU and its strongest first-half net income in three years. Since then, the stock has fallen about 20%, while the S&P 500 is up roughly 1%. The market appears to doubt that the profitability inflection can survive a more crowded, cheaper mobile market. Results due after the close on November 10 should show which view is closer to the truth.
The Street expects earnings of $0.24 per share on revenue of about $3.11 billion. That would be EPS growth of roughly 9% and revenue growth of about 13% from a year ago. The revenue figure deserves a caveat. In local currency, management was reporting top-line growth in the 7% range last quarter, so the faster dollar growth probably reflects currency translation as much as operating acceleration. Revenue is also expected to be roughly flat with the second quarter's $3.12 billion. The more useful test is whether EPS climbs from the prior quarter's $0.19, and whether margins and local-currency growth keep moving in the right direction. Management did not issue explicit numerical targets. It reaffirmed its commitment to distribute at least 100% of net income and to keep capex intensity improving gradually each year.
The core question is pricing power. Last quarter, EBITDA grew 10.9% and margin widened to 41.8% from 40.2%, helped by mobile ARPU reaching R$32.5. Since then, rivals have rolled out light plans priced between R$30 and R$45 a month. Vivo answered with its own Vivo Easy Light, a credit-card-based plan that management framed as a tool for converting prepaid customers with no bad-debt risk. The bull case holds that these plans pull customers up from prepaid rather than down from hybrid. Stable or rising ARPU and churn holding near 1.0% would support that view. A dip in ARPU or a jump in churn would suggest cannibalization, and could explain the stock's slide. Management also noted that front-book prices on control plans had not yet been raised and that someone in the industry would need to move first. Any sign of price discipline would be a meaningful positive.
Postpaid volume is the second checkpoint. Net adds slowed to 14.1% growth in the second quarter from 22.7% in the first. That rate is healthy but past its peak. A further slowdown would be tolerable if ARPU held firm. A slowdown combined with softer pricing would not. Fiber should be the steadier engine. FTTH revenue grew 10.7% last quarter and fiber churn hit a historic low of 1.4%, so continued double-digit fiber growth would confirm that the fixed business can cushion mobile noise. Handset and electronics sales grew nearly 28%, which lifts revenue but carries thinner margins. A heavy retail mix could therefore weigh on the margin story.
Below the operating line, asset sales are a swing factor for net income and shareholder payouts. Copper sales rose from R$86 million in the first quarter to R$201 million in the second. The company has also listed 47 properties worth roughly R$600 million and pointed to faster monetization in the second half. Management cautioned that timing can be lumpy, so a quiet quarter here would not break the thesis, though it could cloud the EPS comparison.
Sentiment has soured, with bearish readings roughly doubling from the prior quarter. The stock sits well below its 200-day moving average of $13.77 and near the bottom of its post-earnings range. That positioning lowers the bar somewhat. Still, the report will be judged on one issue. If Vivo shows that ARPU and margins held up as light plans spread, the profitability narrative remains intact and the selloff looks overdone. If pricing slipped, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Jul-28 | |
| Jul-28 | |
| Jul-27 | |
| May-12 | |
| May-11 | |
| May-11 | |
| Mar-08 | |
| Mar-06 | |
| Mar-05 | |
| Mar-04 | |
| Mar-03 | |
| Feb-26 | |
| Feb-26 | |
| Feb-25 |
