CVG's Revenue Surge Outruns Profit Conversion: A Penny Miss, Trimmed EBITDA Ceiling And CEO Change Overshadow A Third Revenue Raise
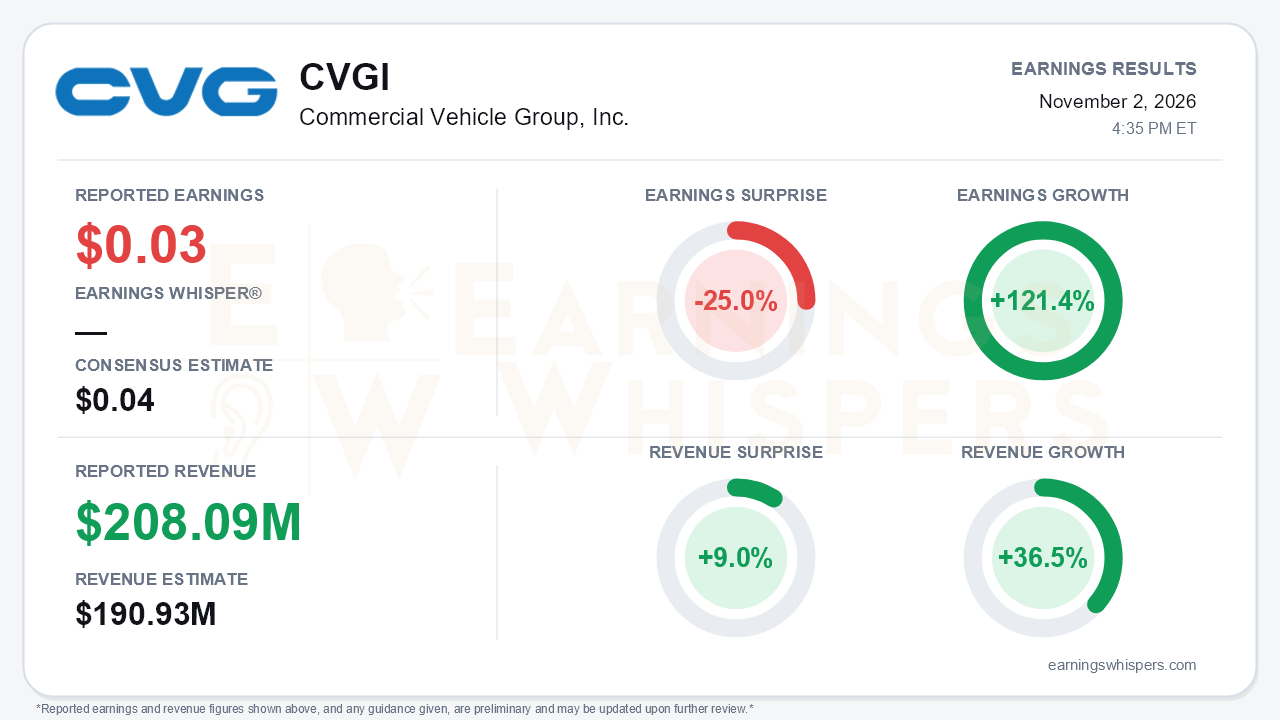
Commercial Vehicle Group delivered the kind of top-line quarter turnaround investors had been waiting for, but not the earnings leverage to go with it. Adjusted EPS of $0.03 missed the $0.04 consensus by 25.0%, even as revenue of $208.09 million beat expectations by 9.0% and grew 36.5% year over year. Earnings grew 121.4% from a year ago, a swing from an adjusted loss of $0.14 per share to the company's first positive adjusted and GAAP EPS since early 2024. That is the central tension. CVG is now growing quickly, yet roughly $56 million of incremental revenue produced only about $4 million of additional adjusted EBITDA. Management also lowered the top of its full-year EBITDA range while raising revenue guidance for a third time.
The quality of the quarter deserves scrutiny. GAAP EPS of $0.14 looks far better than the adjusted figure, but it was lifted by a $4.1 million warrant revaluation benefit and a $3.1 million gain on asset sales. Strip those out and the business earned $1.2 million. The improvement beneath that figure is still real. Adjusted gross margin reached 13.8%, up from 12.1% a year ago, 12.9% in Q2 and 10.3% in Q4 2025, and is the best level since 2023. Adjusted EBITDA rose to $8.5 million, a 4.1% margin, versus 2.8% in each of the first two quarters. The leak is below gross profit. SG&A climbed to $23.5 million from $17.1 million, and corporate costs more than doubled to $5.4 million. The drivers were share-based compensation (up to $3.1 million from $1.0 million), performance-based incentive pay and CEO search costs.
Operationally, the acceleration is broad. Trim Systems revenue jumped 71.9% after declining 13.9% in Q1, and its adjusted operating margin moved to 4.5% from negative territory on stronger Class 8 builds and new launches. Electrical Systems growth sped up to 30.2% from 15.8% in Q2 and 13.9% in Q1, with a 5.7% segment margin, helped by program ramps and construction demand. Seating grew 23.3% while absorbing footprint consolidation in China, the U.S. and the U.K. Management raised its construction outlook to high-single-digit growth, from mid-single digits last quarter. It lifted 2026 revenue guidance to $755-$775 million from $725-$755 million. Net leverage fell to 2.7x from 4.1x at year-end 2025.
The forward picture is more mixed than the revenue raise suggests. Adjusted EBITDA guidance was narrowed to $26-$29 million from $26-$31 million, a lower midpoint. Management attributed the cut to succession costs, higher incentive compensation and the cost of supporting ramps. The guide implies fourth-quarter revenue below Q3's level. Management also expects Trim to be flat to down sequentially, and ACT trimmed its 2026 Class 8 forecast to +8%. Execution frictions persist, including:
- premium freight and overtime;
- lagging recovery of commodity, freight and tariff costs;
- a Zoox ramp running slower than planned.
Cash conversion is a legitimate concern. Free cash flow was just $0.6 million, and that depended on $4.1 million of asset-sale proceeds. Receivables and inventory have swelled since year-end, and capex rose to $5.1 million. On the positive side, Zoox has signaled potential added volume in 2027, and the Alabama plant becomes fully dedicated to it from Q1 2027. Management also expects incentive-compensation headwinds to ease next year, which should improve incremental margins. Customers possibly working through the holidays offers a modest Q4 upside path.
The leadership change adds another variable. James Ray, who refinanced the balance sheet and restructured the operating model, steps down on November 9. Incoming CEO David Ruppel, a Littelfuse commercial-vehicle and transportation executive, has not yet weighed in on guidance. His background fits CVG's electrical and truck exposure. Still, new leadership often brings a fresh look at targets, and the current outlook carries an implicit asterisk until he speaks to it.
The market had already turned skeptical. Shares have fallen 34.0% since the open after the August report, from $4.80 to $3.17. The stock sits about 9.8% below its 200-day moving average of $3.51. Earnings Whispers investor sentiment slipped from essentially neutral to modestly negative, a meaningful move but not a capitulation. Price and AVWAP trend readings remain negative, while momentum is positive. That leaves a stock priced for disappointment despite accelerating sales.
The bottom line is that CVG has proven it can grow again. Revenue, gross margin, leverage and segment profitability are all moving in the right direction, and the revenue outlook keeps rising. What it has not yet proven is that growth will convert into earnings and cash. Rising compensation costs, ramp inefficiencies, weak free cash flow and a softer Q4 setup leave bears with legitimate ammunition. A CEO handoff adds uncertainty. The 2027 story depends on incentive-cost relief and the Zoox and construction ramps translating into the margin leverage this quarter only partially delivered.
Read our earnings preview for Commercial Vehicle Group, Inc.: https://www.earningswhispers.com/article/CVGI/21470
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-20 | |
| Aug-10 | |
| Aug-07 | |
| Aug-03 | |
| Aug-03 | |
| Jul-21 | |
| Jun-23 | |
| May-28 | |
| May-05 | |
| May-05 | |
| Apr-22 |
