Enpro Accelerates On Every Line And Raises Guidance A Third Time, Even As The Stock Slid Into The Report
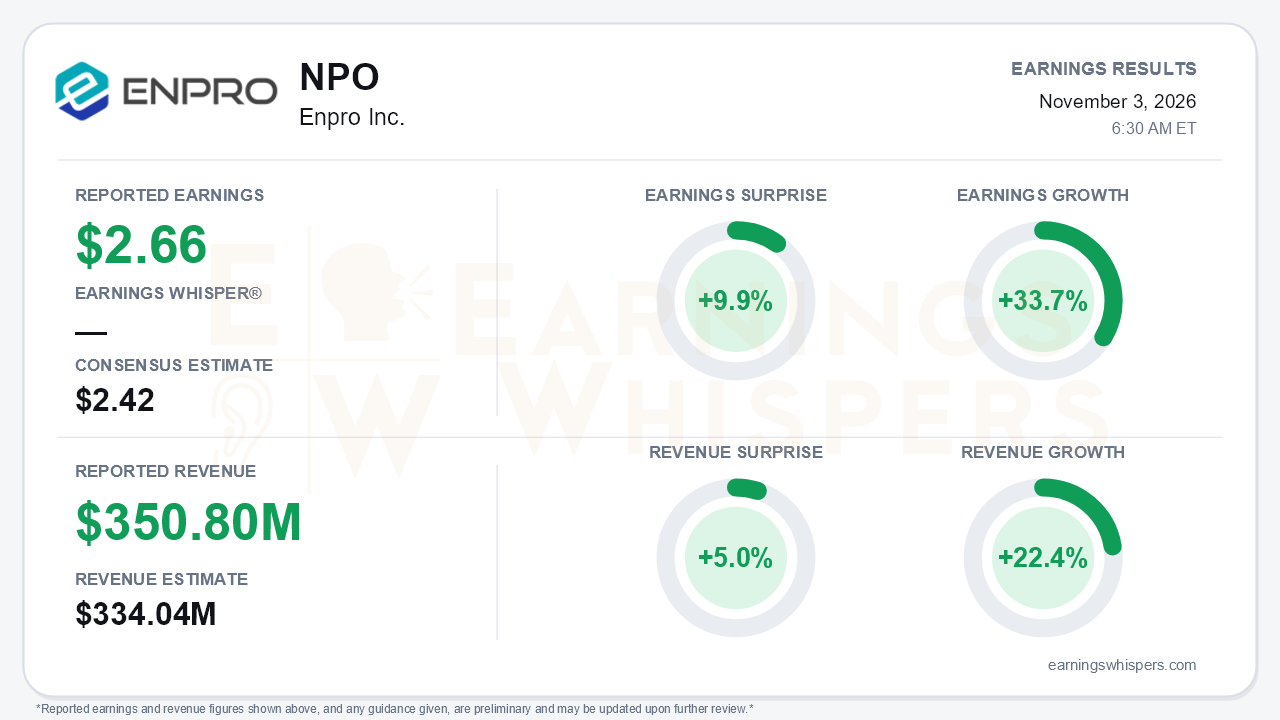
Enpro delivered one of its cleanest quarters in some time. Adjusted EPS came in at $2.66, beating the $2.42 consensus by 9.9% and rising 33.7% from a year ago. Revenue of $350.8 million beat expectations by 5.0% and grew 22.4%. More important than the size of the beat is the direction of travel. Revenue growth has stepped up from roughly 11% in the first quarter to 17.6% in the second and 22.4% now. Management also raised full-year guidance for the third consecutive time. That is the central tension in the setup: the fundamentals are accelerating, while the stock spent the inter-earnings period moving in the opposite direction.
The quality of the quarter holds up under scrutiny. Excluding foreign exchange and the AlpHa Measurement Solutions and Overlook Industries acquisitions, sales still grew 16.9%. Acquisitions do not inflate the AST growth at all, because that segment's 25.8% increase was entirely organic. GAAP diluted EPS of $1.88 nearly doubled from $1.01. Most of the gap to the adjusted figure reflects $20.2 million of acquisition-related intangible amortization rather than recurring operating charges. Adjusted EBITDA margin expanded 180 basis points to 26.0%, and GAAP operating margin rose 370 basis points to 18.0%. There are blemishes:
- Corporate expense climbed to $13.5 million from $10.2 million on higher incentive accruals and restructuring.
- Nine-month free cash flow rose to $129.2 million from $104.9 million, but lower cash taxes helped that figure.
- The company absorbed a sizable build in receivables and inventory to support demand.
The operating story is about breadth. AST margin has moved from 23.3% in the first quarter to 23.9% in the second and 25.1% in the third, a 500-basis-point gain year over year. Management cited incremental margins of at least 40% on AST volume. Its fourth-quarter AST framing now calls for revenue growth and margin both above 25%, an upgrade from the earlier 'approaching 25% exiting the year' language. Sealing Technologies may be the bigger surprise. Organic growth more than doubled to 11.6% from 5% in the second quarter, helped by mid-teens domestic general industrial growth, aerospace strength and pricing. Commercial vehicle OEM revenue rose more than 8% after soft first and second quarters, and management expects that improvement to continue into 2027. Sealing margin of 32.6% marked an 11th straight quarter above 30%, although it slipped from 33.2% in the second quarter.
The guidance progression tells its own story. Adjusted EPS guidance has moved from $8.50-$9.20 in February to $9.70-$9.95 now. Revenue growth guidance has risen from 8%-12% to 16%-17%, and the narrower ranges suggest rising visibility. Several other developments strengthen the forward case:
- AST capacity expansions in Arizona, California, Taiwan and Singapore are tied to firm customer commitments and new wins.
- Management claims visibility through 2027 and partly into 2028-29.
- Net leverage has fallen to 1.4x from 2.0x at year-end after $135 million of revolver paydown this year.
- A replacement $50 million buyback has been authorized.
Bears still have some ammunition:
- 2027 capex will likely run above the 3.5%-4.5% of revenue plan as AST investments are pulled forward.
- Sealing margin is guided lower sequentially in the fourth quarter.
- European industrial and food/biopharma demand remain soft.
- AST depends on a small, geographically concentrated customer base, including exposure to Taiwan-related geopolitical risk.
The market setup is more complicated than the surprise implies. Heading into the report, shares were at $268.98. That is 17.1% below the open following the August report and 23.1% below the $349.67 inter-earnings high set in mid-August. The stock was only 3.7% above the October 23 low and about 9.2% under its 200-day moving average. Investor sentiment slipped from roughly neutral (0.04) to modestly negative (-0.20). That is a meaningful cooling, though not capitulation. Price and AVWAP trend readings were negative, while momentum readings were more constructive. The pattern points to a stock de-rated on worries about the durability of semiconductor and industrial demand, not on any deterioration in Enpro's own reported numbers.
That disconnect is what the quarter puts in question. Investors who sold the stock through the autumn were not positioned for acceleration in both segments, a commercial vehicle inflection and another guidance raise. Still, the fourth-quarter EPS range implied by full-year guidance does not suggest a dramatic step up from the third quarter. The upside case therefore leans heavily on 2027 capacity coming online as planned.
The bottom line is that Enpro's results and outlook improved on nearly every measurable dimension, with AST leverage and a broadening Sealing recovery doing the work. The stock entered the report near its lows with souring sentiment, so the fundamental evidence now runs well ahead of how the market had been treating the shares. Elevated capex, concentrated AST exposure and pockets of European weakness are the key things to watch.
Read our earnings preview for Enpro Inc.: https://www.earningswhispers.com/article/NPO/21500
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 7 hours | |
| 9 hours | |
| Oct-28 | |
| Oct-26 | |
| Oct-20 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Jul-30 | |
| Jul-21 | |
| May-05 | |
| May-05 | |
| Apr-30 | |
| Apr-29 |
