Sportradar's Prediction-Market Reacceleration Beats Estimates, But Reaffirmed Lower Guidance And A Brazil Overhang Keep The Debate Open
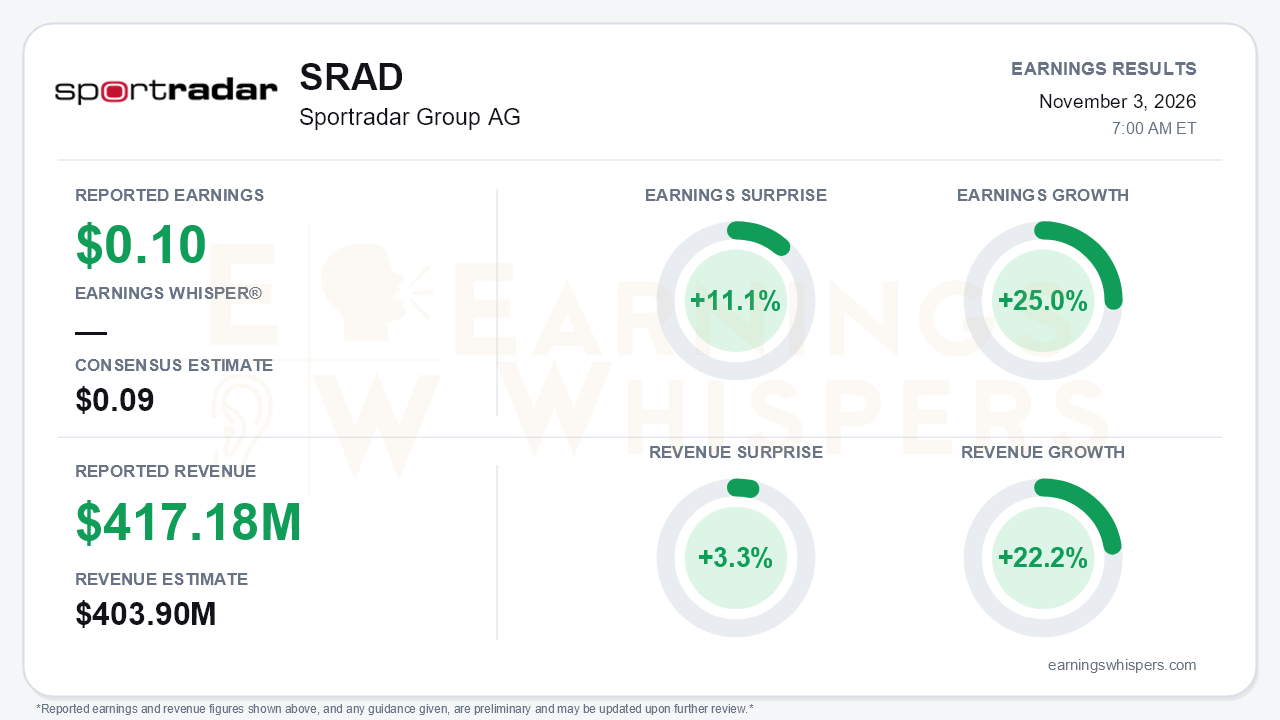
Sportradar delivered the reacceleration that skeptics were not positioned for, but it did not raise the bar. The company earned $0.10 per share, beating the $0.09 consensus by 11.1%, on revenue of $417.18 million that topped estimates by 3.3%. Earnings grew 25.0% year over year and revenue rose 22.2% on Earnings Whispers' dollar basis. In its euro reporting currency, revenue climbed 24% to €363 million. That is the fastest pace in at least four quarters, up from 19% in Q2 and 11% in Q1. The central tension is that full-year guidance was only reaffirmed at the levels cut in Q2, which sit below Street expectations. The quarter proved demand is improving. It did not prove the original 2026 plan is back.
The growth mix shifted sharply. Betting & Gaming Content jumped 37%, up from 27% in Q2 and 20% in Q1, on IMG ARENA rights and new prediction-market customers. U.S. revenue surged 47% and now makes up 27% of the total, compared with 23% a year ago. Not everything improved:
- **Managed Betting Services** fell 3% on unfavorable sport outcomes.
- **Sports Performance** declined 8%.
- **Adjusted EBITDA** rose 21% to €102 million, but margin slipped to 28.2% from 29.0%. Sport rights expenses climbed to €111.7 million from €72.5 million as IMG costs flowed through, partly offset by lower adjusted personnel costs.
- **IFRS profit** rose 20% to €27 million despite a €6 million currency loss, higher financing costs, €4.5 million of restructuring charges and a €2.8 million impairment.
The quality of the per-share beat also deserves scrutiny. Weighted Class A shares fell to roughly 203 million from 222 million, so aggressive buybacks did some of the lifting.
The call's most important development was prediction markets turning from optionality into revenue. Earlier in the year, management framed the opportunity as having limited impact or tens of millions of upside. This quarter it described a real contributor:
- Polymarket expanded to more than 20 leagues.
- Kalshi takes the full product suite, and Novig was added as a third exchange.
- Robinhood signed as the first broker, alongside roughly 10 market-maker contracts.
- The NBA's requirement for official data in authorized prediction markets begins contributing in Q4.
Management said IMG revenue synergies are now "definitely above" the 25% target. It guided to Q4 and full-year margin expansion of 70 to 100 basis points, and to "significant" margin expansion in 2027. The tone was clearly more confident than in Q2.
Bears still have legitimate ammunition:
- **Guidance gap:** Reaffirmed guidance of 19%-21% constant-currency revenue growth and 24%-27% adjusted EBITDA growth (€360-€368 million) compares with original targets of 23%-25% and 34%-37%.
- **Brazil:** The provisional halt on sports betting puts roughly $60 million of annual revenue at risk, including about $15 million in Q4, and cost reductions will lag.
- **Other risks:** A likely 2027 MLB lockout and state-level prediction-market bans add uncertainty.
- **Market growth:** The CFO conceded growth is running below investor-day assumptions.
- **Cash flow:** Management expects negative Q4 free cash flow on rights and prediction-market timing. Nine-month free cash flow still rose 18% to €177 million at 72% conversion.
- **Divestiture:** The $170 million Atrium Sports sale brings cash at a double-digit EBITDA multiple. However, it removes higher-margin revenue that guidance does not yet reflect.
- **Balance sheet:** Cash fell to €190 million from €365 million at year-end after €352 million of 2026 repurchases. The company carries no debt and has €440 million of total liquidity. A $50 million IMG payment is due in Q4.
Investors were not leaning bullish into the print. Earnings Whispers sentiment stayed negative and weakened modestly, falling from -0.117 to -0.192. The stock set a 52-week low of $11.39 on October 1. It recovered to $12.87 on the day before the report, up 9.4% from the open after the August release and 13.0% above that low. Shares still sat 8.5% below the inter-earnings high of $14.06 and 13.6% below the $14.90 200-day moving average. Momentum and AVWAP trend readings remain negative, reflecting a stock still working off the Q2 guidance cut rather than rewarding the recovery.
The bottom line is that Sportradar's third quarter changed the fundamental conversation more than the guidance changed the numbers. Accelerating growth, a credible prediction-market ramp and a 2027 margin story give the company a stronger narrative than it had in August. The unchanged, below-consensus outlook, the Brazil exposure and a thinner cash cushion explain why sentiment remains cautious. The next test is whether Q4 prediction-market and NBA contributions can offset Brazil and turn reacceleration into upward estimate revisions.
Read our earnings preview for Sportradar Group AG: https://www.earningswhispers.com/article/SRAD/21515
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-22 | |
| Oct-07 | |
| Sep-03 | |
| Aug-27 | |
| Aug-27 | |
| Aug-26 | |
| Aug-24 | |
| Aug-12 | |
| Aug-03 | |
| Aug-03 | |
| Aug-03 |
