ReNew Delivers Accelerating Growth And Raises EBITDA Guidance, But The $7.02 Take-Private Caps The Stock
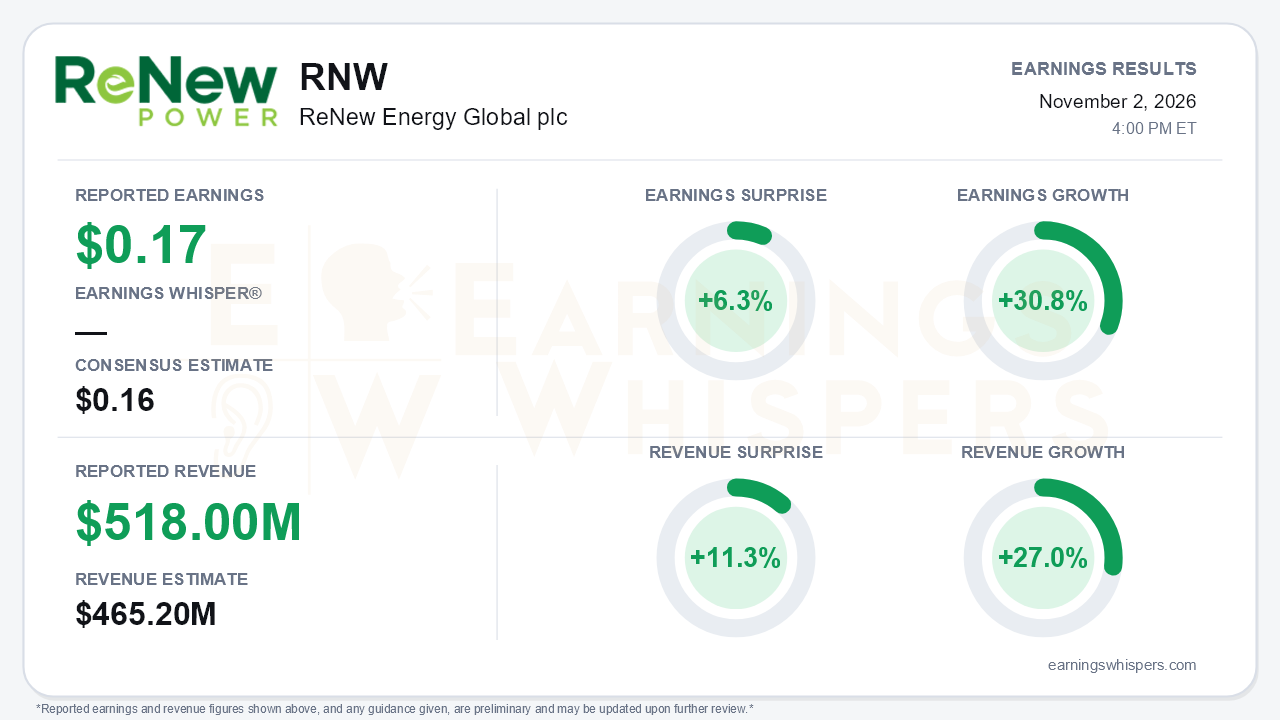
ReNew Energy Global (NASDAQ: RNW) posted its strongest growth quarter in recent memory, though the take-private deal now largely determines what the stock can do. For the fiscal second quarter ended September 2026, the company reported earnings of $0.17 per share against a $0.16 consensus, a 6.3% beat. Revenue of $518.0 million topped the $465.2 million estimate by 11.3%. Earnings grew 30.8% year over year and revenue rose 27.0%. Management also raised FY27 Adjusted EBITDA guidance. In most cases that combination would reset the investment debate. Here, the shares sit at $6.85, just below the $7.02 per-share take-private price, and the quarter matters more for what it says about the business than for any near-term rerating.
Growth clearly accelerated. Q2 Adjusted EBITDA rose 28% to INR 33.6 billion, more than double the roughly 12% growth posted in Q1 on INR 30.4 billion. Net profit climbed 37% to INR 6.4 billion, compared with 16% growth in the prior quarter. The core power business drove much of the gain. Revenue from the sale of power reached INR 33.8 billion, up from INR 26.1 billion a year ago. Commissioned capacity rose 19.5% to about 13.7 GW, and the consolidated Adjusted EBITDA margin widened to 69.0% from 66.1% in Q1. Management credited strong Indian power demand, which grew about 10% in H1 and 21% year over year in October, with peak deficits adding value to storage and round-the-clock offerings.
The quality of the beat holds up better than the manufacturing headline suggests, but it is not flawless. Manufacturing is cooling sequentially. External manufacturing revenue fell to roughly INR 12.5 billion from INR 16.4 billion in Q1. Manufacturing EBITDA dropped to INR 4.1 billion from INR 5.7 billion, although it remains above last year's INR 3.3 billion. Management still expects margins to moderate in the second half as more cell capacity comes online, and module margins have already compressed significantly. Even so, the external order book tripled to about 3.3 GW from 1.1 GW, and full-year manufacturing EBITDA guidance rose to INR 12–14 billion from INR 10–12 billion. Management had hinted at that upgrade last quarter and followed through.
The guidance change deserves a closer look. Consolidated EBITDA guidance moved only at the low end, to INR 105–109 billion from INR 103–109 billion. The manufacturing range, by contrast, rose by INR 2 billion at both ends. That implies limited upgrades elsewhere, and curtailment is the obvious drag. Solar transmission curtailment cost about $9–10 million in Q2 and $18–19 million in H1, with no compensation mechanism agreed. The IPP margin, excluding 3E, slipped to 82.9% from 86%, partly from curtailment and mix. Management only reaffirmed its targets for capacity construction (1.6–2.4 GW), cash flow to equity (INR 18–22 billion) and run-rate EBITDA. A weaker monsoon added further noise.
The balance sheet is where the story improved most decisively. Net debt to trailing EBITDA for operating projects fell to 5.3x from 5.7x, and IPP receivable days dropped to a record-low 63 from 71. Moody's revised its Ba2 outlook to positive from negative, and CARE also moved to a positive outlook. Capital recycling now totals about $300 million, combining the roughly $84 million 3E stake sale with the roughly $190 million 1 GW asset sale. Refinancing visibility widened to $1.25 billion of about $1.7 billion in maturities. About $0.45 billion, due mid-2027, remains uncommitted. The 4 GW TOPCon cell line is on track for first cells around January 2027. The release's boilerplate cites "Q4 FY26" for that expansion, which appears to be a stale reference.
The market setup is more complicated than the surprise implies. ReNew has filed its take-private scheme with the SEC and expects it to become effective in Q1 CY2027. Jera and an ADIA affiliate, representing about 51.1% of scheme votes, have irrevocably committed. That explains why the stock is up just 0.3% since the open following the August report, even as fundamentals strengthened. Shares trade about 14.9% above their 200-day moving average of $5.96, and the Earnings Whispers price and AVWAP trends are positive. Upside, however, is effectively anchored to the deal price. Investor sentiment improved meaningfully, from -0.45 to -0.24, but remains negative. That reading likely reflects frustration with the buyout terms and reduced future public-market visibility as much as doubt about operations.
The bottom line is that ReNew delivered accelerating EBITDA and profit growth, a manufacturing guidance raise and real credit improvement. Curtailment and softening manufacturing margins are legitimate but manageable offsets. For public shareholders, the stronger business mostly validates the asset's value inside a $7.02 take-private rather than opening a path to a standalone rerating.
Read our earnings preview for ReNew Energy Global plc: https://www.earningswhispers.com/article/RNW/21661
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Nov-02 | |
| Oct-27 | |
| Aug-18 | |
| Aug-13 | |
| Aug-12 | |
| May-18 | |
| May-11 | |
| Apr-15 | |
| Mar-16 | |
| Feb-21 | |
| Feb-16 | |
| Feb-16 | |
| Feb-16 | |
| Feb-15 |
