Ferrari Beats And Raises Again, But Mix And Pricing, Not Volume, Drove The Quarter
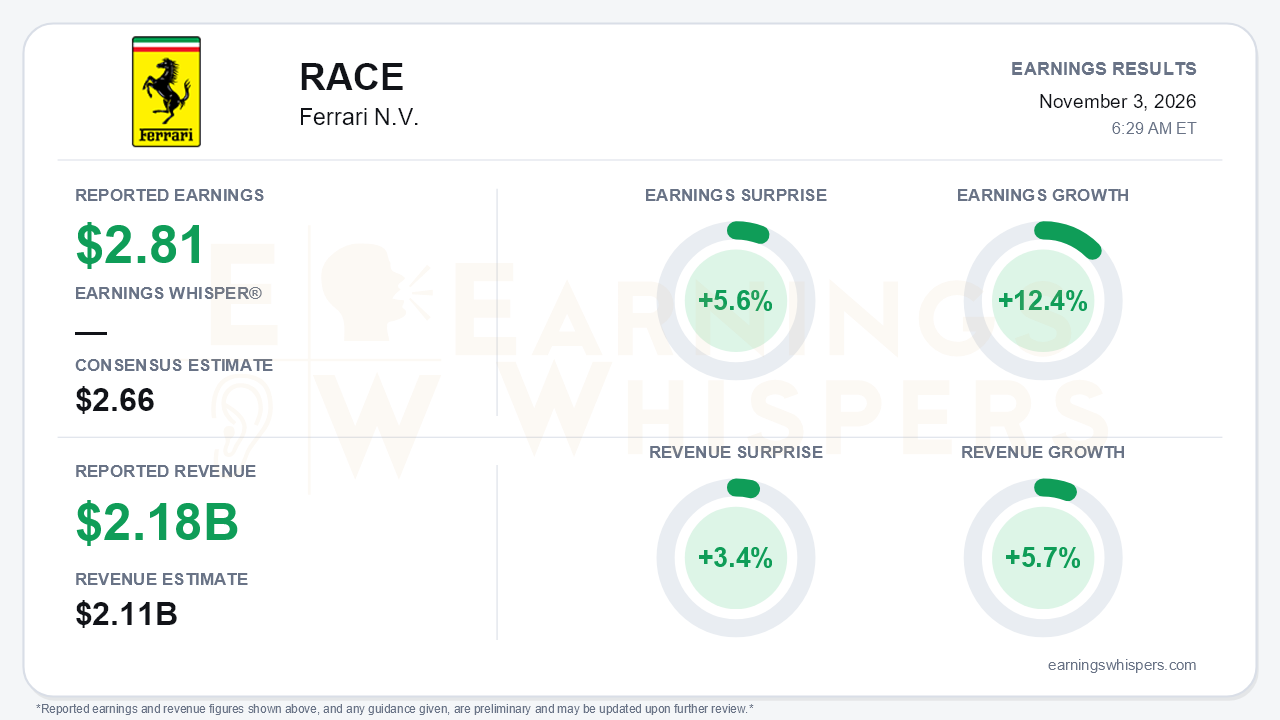
Ferrari (NYSE: RACE) beat expectations in the third quarter, though the source of the strength deserves attention. Earnings of $2.81 per share topped the $2.66 consensus by 5.6%, and revenue of $2.182 billion beat the $2.11 billion estimate by 3.4%. Earnings grew 12.4% year over year, roughly double the 5.7% revenue growth. That gap is the story. Ferrari shipped fewer cars than a year ago and still expanded margins, because each car carried more value. Management raised full-year guidance for the second consecutive quarter. The open question is how much of the quarter's richness can repeat.
In euros, net revenues rose 7% to €1,896 million, or 10% at constant currency. Operating profit (EBIT) grew 12% to €563 million, and 23% at constant currency. EBIT margin widened to 29.7% from 28.4%, and EBITDA margin reached 39.7%. Diluted EPS rose to €2.44 from €2.14. There were no non-GAAP adjustments, so reported and adjusted figures are identical. The effective tax rate actually rose to 23.0% from 22.0%, which means the profit beat was not tax-driven. Lower net financial expenses, helped by FX, added a modest boost. Cash generation was especially strong. Industrial free cash flow jumped 43% to €567 million, and Ferrari swung from €131 million of net industrial debt in June to €219 million of net industrial cash, even after €173 million of buybacks.
The operating detail shows how narrow the growth engine was:
- **Volume:** Shipments slipped to 3,368 units from 3,401. Mainland China, Hong Kong and Taiwan fell to 143 units from 248, which management attributed to the model changeover.
- **Pricing and mix:** Average selling price rose about 8% year over year. Management said the EBIT gain came mainly from F80-supported mix and higher personalizations.
- **Personalization:** The personalization rate climbed above 21%, up from roughly 20% earlier in the year.
- **Growth pace:** Constant-currency revenue growth eased slightly to about 10% from 11% in the second quarter.
- **Margin trend:** EBIT margin was below the second quarter's 31.2%, though up year over year.
- **Demand visibility:** The order book now extends into 2028, versus covering full-year 2027 last quarter and reaching toward end-2027 before that.
The call surfaced a real catch. Special-series cars made up about 22% of third-quarter shipments, versus roughly 13% in the first half. Management characterized that concentration as something that will normalize, which implies tougher mix comparisons into 2027. F80 deliveries are growing only modestly, at about 50 units a quarter. Fourth-quarter results will carry higher marketing and event spending plus rising depreciation as new models enter production. FX remains a €150-200 million full-year headwind even after hedges. Management also declined to give any 2027 color, holding to the "smooth and linear" Capital Markets Day trajectory. Bears have legitimate ammunition on whether third-quarter mix is a peak rather than a run rate.
The catalyst list is still substantial:
- **Luce:** First deliveries begin in the fourth quarter, and 2027 allocation is fully spoken for.
- **New launches:** Two more models debut before year-end.
- **Capacity:** A new paint shop nearing completion should support personalization, and carbon-fiber supply is no longer a constraint.
- **FX and costs:** The USD/EUR assumption improved to about 1.15 blended, with rolling hedges carrying benefit into 2027. Lower F1 costs tied to a second-place ranking also help.
The upgraded guidance reflects these factors. Revenue is now about €7.65 billion versus €7.60 billion. Adjusted EBITDA is at least €3.00 billion at a 39.2% margin, and adjusted EBIT is at least €2.285 billion at 29.8%. Adjusted diluted EPS is at least €9.85, up from €9.68, and industrial free cash flow is up to €1.65 billion. With €1.496 billion of industrial FCF already generated through nine months, the cash target looks conservative. The raise moved guidance closer to Street estimates rather than decisively beyond them, which tempers how much upside it signals.
Investor expectations cooled heading into the print. Earnings Whispers sentiment moved from a slightly positive 0.07 to a modestly negative -0.10. That is a meaningful turn, not a collapse. Price action tells a similar story of fading enthusiasm. Shares at $403.09 were up 3.4% since the open after the July report and sat 9.2% above the 200-day moving average. However, they were 7.8% below the $437.15 52-week high set August 21 and only 5.7% above the quarter's low. In short, the stock gave back much of its August run. Sequential-growth and momentum trend readings remain positive, while the AVWAP trend is negative, consistent with a stock that has drifted lower within an intact uptrend.
The bottom line is that Ferrari delivered a high-quality beat in cash flow and margins, with demand visibility that keeps lengthening. Still, the quarter leaned heavily on a special-series concentration management itself expects to fade. Falling volumes, softness in Greater China and silence on 2027 leave the debate centered on mix sustainability. Near-term execution, by contrast, remains strong.
Read our earnings preview for Ferrari N.V.: https://www.earningswhispers.com/article/RACE/21507
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-26 | |
| Oct-19 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 |
