Driven Brands Must Prove Take 5 Slowdown And Oil Costs Have Bottomed
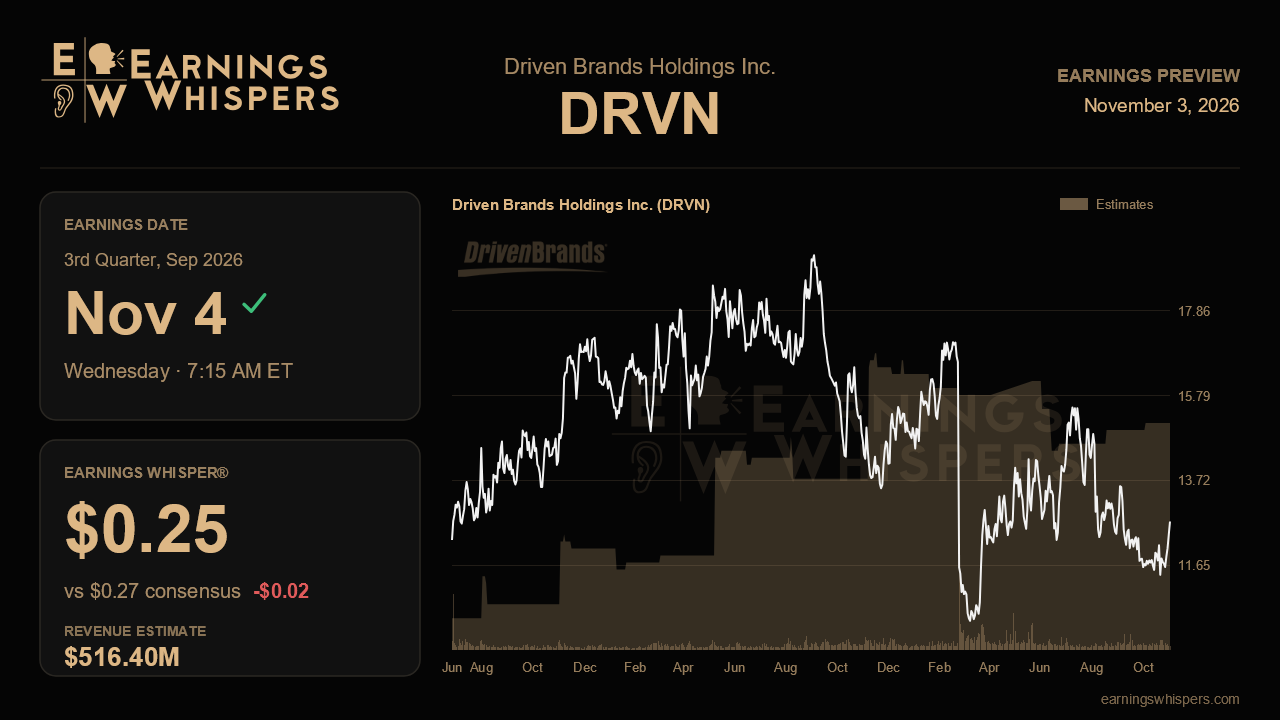
Driven Brands enters its third-quarter report with a balance sheet that keeps getting healthier and an operating story that keeps getting harder to tell. Last quarter, management reaffirmed every guidance range but quietly steered adjusted EBITDA toward the low end of its $430 million to $460 million target. Meanwhile, Take 5, the oil change chain that has carried the growth narrative, posted its weakest same-store sales gain in at least a year. The November 4 release, due before the open, is the first real test of whether that low-end framing was a cautious floor or the start of a longer slide.
The Street expects earnings of $0.27 per share on revenue of $516.4 million. That revenue figure implies a 3.6% decline from the $535.7 million reported a year ago, and the EPS estimate sits well below last year's $0.32. In other words, analysts are bracing for contraction, not just a pause. The Earnings Whisper of $0.25 sits a couple of cents under consensus, a modest but telling signal that the more skeptical crowd expects a slight shortfall rather than a cushion. There is also a curious disconnect in the full-year numbers. Management still guides to non-GAAP EPS of $1.15 to $1.25, yet consensus of $1.23 sits near the top of that range, even though the company itself flagged EBITDA tracking toward the bottom of its outlook. Either the Street is leaning on lower interest expense from debt paydown to bridge the gap, or full-year estimates have room to drift lower if this quarter disappoints.
Take 5 is the swing factor. Same-store sales growth has slid from 6.8% in the year-ago third quarter to 4.5% in the first quarter and 3.6% in the second, while its EBITDA margin fell about 70 basis points on store-level inflation, erasing the expansion posted just one quarter earlier. Management responded with its first corporate price increases late in the second quarter to offset base-oil costs that rose with renewed Middle East conflict. This report should show whether that pricing is sticking without denting traffic, particularly among lower-income customers that management expects to stay under pressure through the second half. A stabilization in comps alongside steadier margins would validate the plan. Another step down in both would suggest pricing is not keeping pace with costs. The continued rise in non-oil-change services, now about 30% of Take 5 sales, is the cleanest offset to watch, since attach sales lift ticket size without relying on more visits.
Secondary issues carry real weight too. Auto Glass Now saw its comp cool sharply to 2.6% and absorbed a roughly $4 million out-of-period charge, so a cleaner quarter there would ease worries about lingering accounting cleanup. Restatement costs are now expected at the top of the $35 million to $45 million range, and the Board's rejection of an activist acquisition proposal from ADW leaves a strategic question hanging. On the positive side, net leverage reached 3.1x, within sight of the 3.0x year-end goal, and the franchise brands continue to throw off roughly 59% EBITDA margins, which keeps the $125 million to $145 million free cash flow target credible.
The market has already rendered a harsh preliminary verdict. Shares have fallen 11.1% since the last report, trailing the S&P 500 by nearly 9 points, and at $12.72 they sit below the 200-day moving average and in the lower half of a post-earnings range that has shifted down from the prior quarter. Bearish sentiment has climbed to 64.8% from 42.7% heading into last quarter. That pessimism lowers the bar somewhat, but it does not rescue a weak print. The central question is simple: if Take 5 comps and margins stabilize under new pricing, the low-end guidance looks like a floor, and the deleveraging story can reassert itself. If they slip again, the reaffirmed ranges may not survive the fourth quarter.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Oct-29 | |
| Sep-15 | |
| Sep-08 | |
| Aug-17 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Aug-03 | |
| Jul-30 | |
| Jul-29 | |
| Jul-03 | |
| Jun-11 | |
| Jun-11 |
