Thomson Reuters Misses On Headline Numbers, But 10% Organic Growth And AI Traction Shift The Debate To Margins
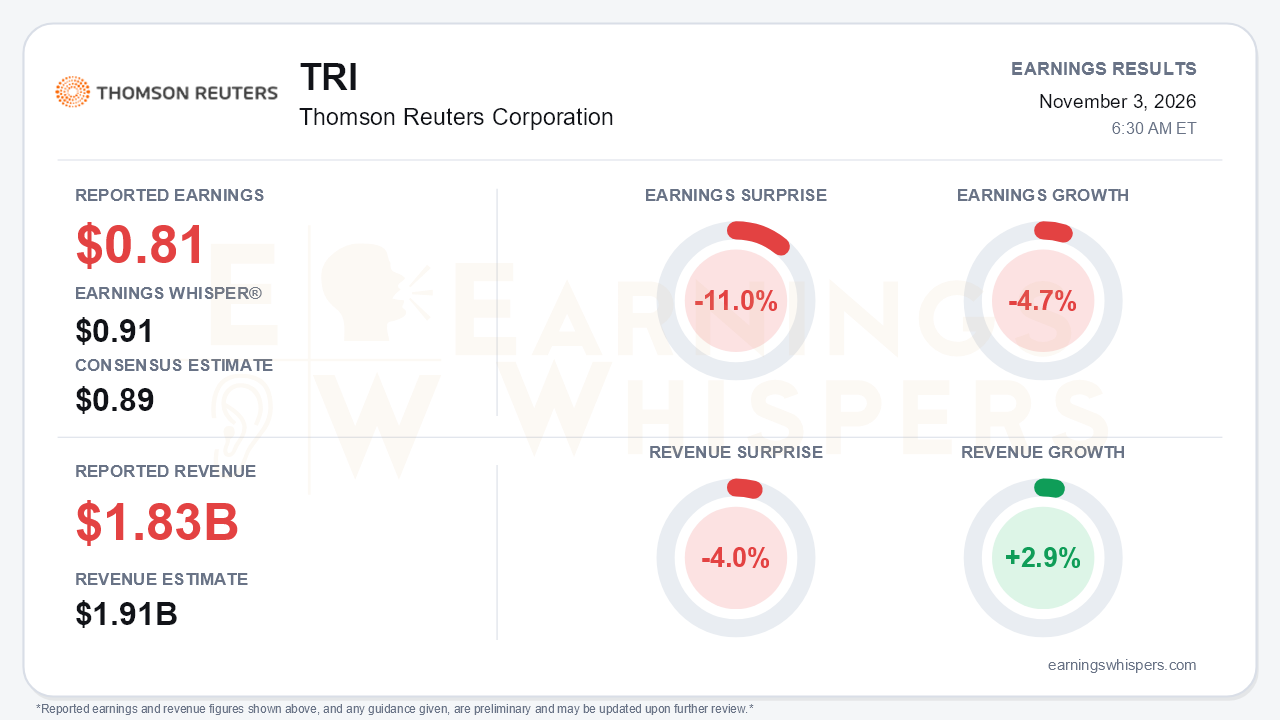
Thomson Reuters (TSX: TRI) reported third-quarter adjusted earnings of $0.81 per share on revenue of $1.833 billion. Both figures fell short. Consensus was $0.89 and the Earnings Whisper number was $0.91, so the quarter missed by 11.0%. Revenue came in 4.0% below the $1.91 billion consensus. On Earnings Whispers' basis, earnings fell 4.7% year over year and revenue grew 2.9%.
Those numbers sit awkwardly beside the company's own presentation. On a restated continuing-operations basis, Thomson Reuters reported 10% revenue growth and 10% organic growth, the fastest pace of the year. Adjusted EPS rose 14% from a restated $0.71. The gap appears to reflect differing comparison bases after the Global Print business moved to discontinued operations, and investors should weigh the miss with that distinction in mind. That is the central tension: a headline miss alongside the strongest underlying top-line quarter in over a year.
The quality of the beat-versus-miss debate deserves scrutiny on both sides.
- **IFRS results were weaker.** Diluted EPS fell to $0.78 from $0.94 and operating profit dropped 22%. Much of that decline traces to a prior-year gain on the Elite stake sale, but higher software amortization also contributed.
- **Margins slipped.** Adjusted EBITDA margin eased 30 basis points to 35.5%. The bigger concern sits inside the Big 3 segments, where margin fell 140 basis points to 40.3%. Legal Professionals dropped 240 basis points to 46.6%, which management tied on the call to $22 million of severance, rising LLM costs and dilution from the Noetica acquisition. Management did say Q3 margin beat its own Q2-guided ~36% on a like-for-like basis.
- **Cash flow weakened.** Free cash flow fell to $408 million from $526 million on working capital and cash taxes.
- **Reuters flattered the total.** The segment grew 12% with a 440-basis-point margin gain, but roughly $19 million of that came from lumpy generative AI content licensing. Excluding it, Reuters grew about 7%.
The operating trajectory beneath that is genuinely improving. Total organic growth climbed to 10% from 8% in the first two quarters and 7% in Q4 2025. Tax, Audit & Accounting rebounded to 10% from 8% after second-quarter go-to-market problems. GenAI-enabled ACV kept stepping up, from 28% to 30% to 32% and now 34%. Management's tone on product was the clear upgrade. Active users of next-gen CoCounsel Legal rose 60% month over month in September, and NPS is more than double the prior best. An agentic CoCounsel for Tax, Audit & Accounting launched in October. The proprietary Thomson LLM moved from benchmarks to a Skadden sovereign-AI design partnership, a potential new licensing stream. Pagero's live French e-invoicing mandate, with about 50 more expected over three years, adds a multi-year Corporates tailwind.
Bears have legitimate ammunition on the forward picture, however.
- **The guidance raise is mostly mechanical.** Full-year organic growth moved to 8.5%-9.0% largely because print was reclassified, while Big 3 guidance was left unchanged.
- **Fourth-quarter growth slows.** Organic growth is guided to about 8%, as Reuters goes flat and Corporates transactions moderate.
- **Legal is cooling.** Growth slipped to 9%, with government at 4% and international softer.
- **The margin framework softened.** Management plans to reinvest part of 2027 operating leverage, walking back the February commitment of roughly 100 basis points of annual expansion. The CFO acknowledged ~41% was achievable but said the company is choosing to invest.
- **Costs are rising.** Capex intensity rises to 8.5%-9% of revenue, and net interest expense moves to the top of its range after a $2 billion note issuance that lifted leverage to 1.0x. Management described an active M&A pipeline that includes material deals.
The market setup is more complicated than the surprise implies. Investor sentiment improved notably into the report, rising from -0.30 to -0.11. It remains negative but is far less pessimistic. The stock has gained 11.1% since the open after the August report and closed the pre-report snapshot at $122.24. That price was 26.5% above the 200-day moving average and only 2% below the inter-earnings high of $124.69 set October 26. The run was remarkably swift, as shares bottomed at $92.57 on September 29 and rallied 32% in under a month. Earnings Whispers trend readings are mostly positive, though sequential growth remains a negative signal. That fits a quarter in which growth peaks before a guided fourth-quarter slowdown.
The bottom line is that Thomson Reuters delivered a quarter that reads better operationally than its headline miss suggests. Organic growth accelerated and AI product adoption is gaining real traction. But the stock entered the report near its highs after a sharp rebound, and the call introduced fresh questions around margin expansion, a decelerating fourth quarter and heavier investment spending. The growth story is credible; the debate now shifts to how much margin investors must surrender to fund it.
Read our earnings preview for Thomson Reuters Corporation: https://www.earningswhispers.com/article/TRI/21523
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 8 hours | |
| 10 hours | |
| 14 hours | |
| Oct-26 | |
| Oct-22 | |
| Oct-19 | |
| Oct-14 | |
| Oct-01 | |
| Sep-29 | |
| Sep-14 | |
| Sep-14 | |
| Sep-10 | |
| Sep-03 | |
| Sep-03 | |
| Sep-02 |
