AMG Heads Into Q3 Needing Alternatives Momentum To Justify A Twice-Raised 40% Growth Target
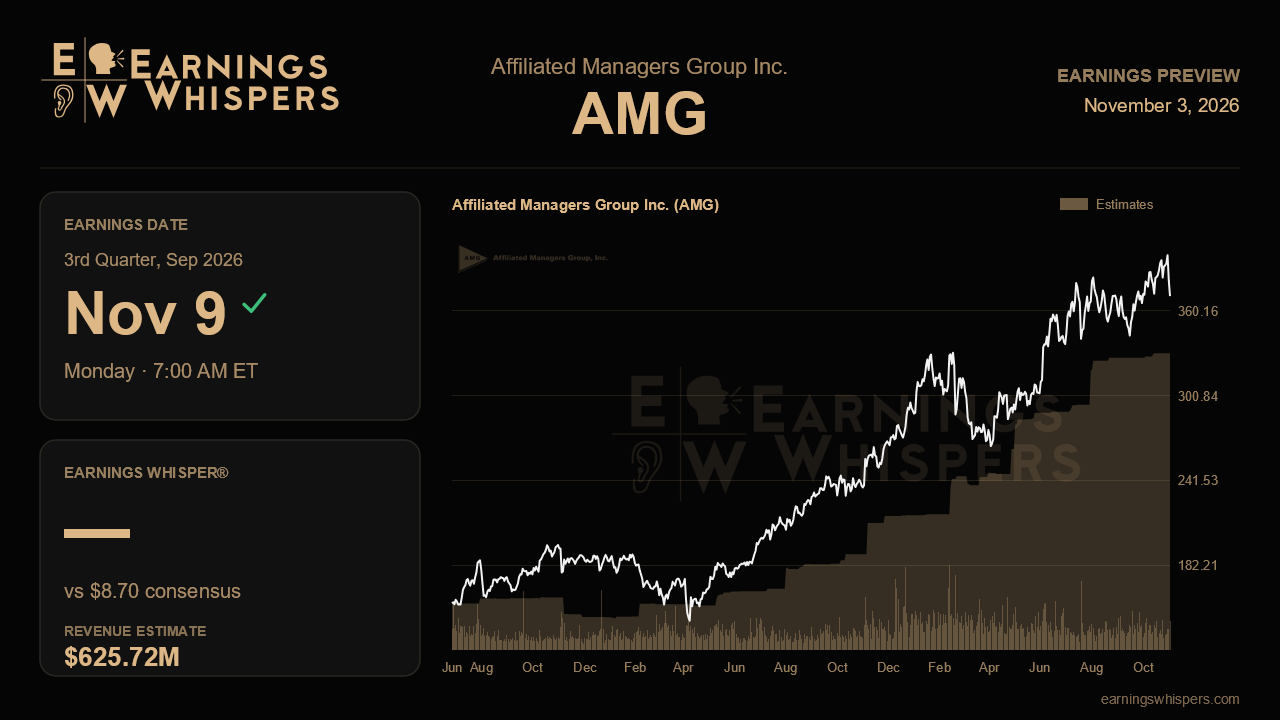
Affiliated Managers Group has spent the past year steadily ratcheting up its ambitions, and the third-quarter report due before the open on November 9 is the first real test of the latest step. Management lifted its full-year 2026 earnings growth outlook to roughly 40% on the last call, up from more than 30% a quarter earlier, while boosting planned buybacks to about $600 million. That kind of escalation earns credibility only if the next print keeps pace, and the Street is now pricing in exactly that.
Consensus calls for earnings of $8.70 per share on revenue of $625.7 million. That represents growth of about 42.6% in EPS and 18.5% in revenue from the year-ago quarter's $6.10 and $528.0 million, a genuinely strong expansion rather than a modest one. Sequentially, the bar is less dramatic: EPS would rise from $8.29 last quarter even as revenue dips slightly from $640.7 million. That gap tells the story. Shrinking share count from aggressive repurchases and a richer earnings mix are doing much of the lifting, so the quarter is as much about quality of earnings as top-line volume. Management's own guide framed third-quarter adjusted EBITDA at $315 million to $325 million, with recurring fee-related earnings expected to climb to $315 million from $299 million. Notably, that range assumed markets down 2% quarter-to-date as of late July. With the S&P 500 up since the last report, a landing at or above the top of that EBITDA range would be the cleanest validation of the raised annual target.
The operating question that matters most is whether the alternatives engine keeps humming. Alternatives now generate more than 60% of earnings, up from roughly half eighteen months ago, and management has openly pointed toward 70%. Record alternative inflows of $29 billion last quarter pushed the trailing twelve-month total to about $100 billion across secondaries, infrastructure, absolute return and tax-aware strategies. Another quarter of strong alts gathering, ideally broad-based rather than concentrated in a single affiliate, would confirm that the mix shift is structural. Given heightened scrutiny on the durability of tax-aware strategies and the AQR relationship, any slowdown there would draw attention quickly.
The counterweight is long-only equity, where outflows worsened to $14 billion last quarter from $9 billion. That business is now only about 35% of earnings, and management argues the trend is improving over the medium term. A stabilization would let headline flows, which fell to $13 billion from a record $22 billion, rebound toward earlier levels. A further deterioration would not derail the thesis but would make the alternatives growth carry a heavier burden. Performance fees, a seasonally light $10 million last quarter, are another swing factor that could help or hurt the EPS print relative to consensus.
The deal pipeline is the newer catalyst worth tracking. Management flagged a meaningful pickup in new investment opportunities late in the second quarter, extending into the third, including sizable transactions. Evidence of an announced affiliate investment, or concrete detail on timing and capital allocation between deals and buybacks, would show the pipeline commentary was more than optimism.
Sentiment has warmed noticeably, with bullish readings rising to 15.9% from 2.8% ahead of last quarter, yet the stock has done little with it, gaining 1.8% versus 2.2% for the S&P 500. At $370.39, shares sit comfortably above the 200-day average near $333 but well off the post-earnings high of $400.13. That suggests investors are giving credit for momentum without fully paying for it. The report's verdict will hinge on one thing: whether alternatives growth and recurring fee earnings are strong enough to keep the 40% growth target looking conservative rather than stretched.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-02 | |
| Oct-12 | |
| Sep-23 | |
| Aug-12 | |
| Aug-11 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-24 | |
| Jul-22 | |
| May-13 | |
| May-06 | |
| May-02 | |
| May-01 |
