ADT Misses Earnings Expectations, But Thrive's $10 Cash Offer Now Drives The Stock More Than The Quarter
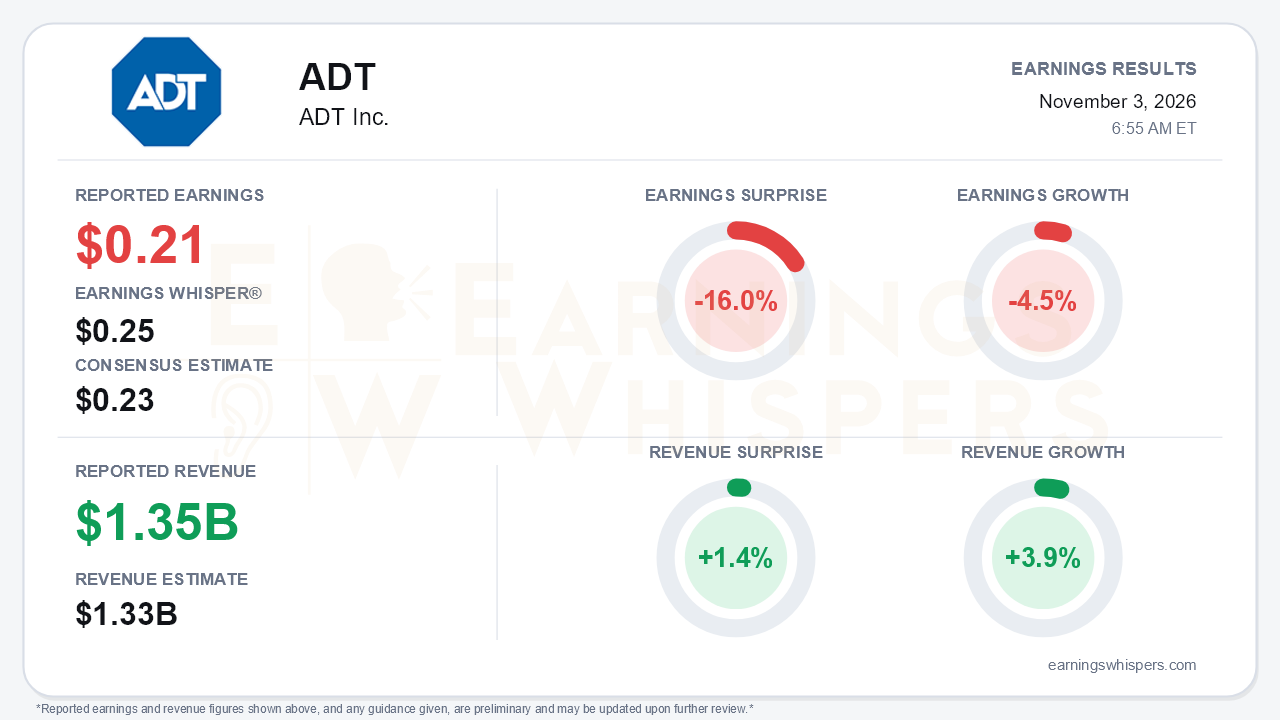
ADT Inc. reported third-quarter earnings of $0.21 per share on revenue of $1.349 billion. That missed the $0.23 consensus and the $0.25 Earnings Whisper number, a 16.0% shortfall. Earnings fell 4.5% from a year earlier, while revenue beat the $1.33 billion consensus by 1.4% and grew 3.9%. The company's own presentation reads more favorably than the normalized figure. ADT reported GAAP diluted EPS from continuing operations of $0.20, up 18%, and adjusted EPS of $0.24, up 4%. The bigger issue is that the quarter has been largely overtaken by events. Five days before the release, ADT agreed to be acquired by Thrive Holdings for $10.00 per share in cash. It then withdrew guidance and took no questions on the call. For a stock trading at $9.83 ahead of the report, the merger spread now matters more than the earnings print. That is the central tension.
The quality of the per-share growth deserves scrutiny. Adjusted income from continuing operations fell 6% to $176 million. Adjusted EPS rose only because the diluted share count dropped to 737 million from 828 million after aggressive buybacks earlier in the year. GAAP EPS growth was also helped by a comparison against a prior-year $12 million goodwill impairment tied to the multifamily divestiture, plus lower interest expense. Adjusted EBITDA slipped 2% to $665 million. Adjusted EBITDA margin compressed to 49% from 52% as general and administrative expenses and technology spending rose. Operating cash flow fell 8% to $440 million. Adjusted free cash flow including swaps rose just 4% to $217 million.
Beneath the headline, revenue is accelerating but the recurring base is not growing. Total revenue growth improved from 1% in the first quarter to 2% in the second and 4% in the third. Nearly all of that came from installation, product and other revenue, which jumped 32% to $265 million, after gains of 17% and 7% in the prior two quarters. The driver is ADT's shift toward outright equipment sales. That revenue carries lower margins: installation cost of revenue rose 50%, against 32% growth in the related revenue. Monitoring and related services revenue, the recurring core, declined 1% to $1.084 billion. That decline reflects lower volume, including the divested multifamily business, partly offset by higher pricing. Ending recurring monthly revenue was $360 million versus $362 million a year ago. Gross revenue attrition ticked up to 13.1% from 13.0%, with non-pay cancellations still elevated. Gross RMR additions did improve sequentially to $12.1 million on 195,000 units, from $11.9 million in the second quarter and $10.1 million in the first. Dealer and bulk volumes remained soft, however.
The cash story has lost much of its earlier momentum. Year-to-date adjusted free cash flow above $1 billion, up 46%, already exceeds full-year 2025. Quarterly growth, though, slowed to 4% from 48% in the second quarter and more than 80% in the first, as previously flagged working-capital benefits faded. Buybacks shrank to $23 million from $594 million in the first half. Current maturities of long-term debt rose to $1.24 billion, reflecting the 2027 notes. Management had earlier flagged potential 2027 cash tax and interest headwinds of $50 million to $100 million each. Those concerns now largely shift to the buyer. The withdrawn 2026 outlook, raised in the second quarter to roughly 2% revenue growth, 2% EPS growth and 30% free cash flow growth, leaves investors with no formal visibility into the fourth quarter or 2027.
The forward catalysts are now almost entirely deal-related. A go-shop period running through November 28 could surface a competing bid. The offer represents a 46% premium to the unaffected price and values ADT at roughly $15.3 billion in enterprise value. Operating initiatives continue but are secondary for public shareholders. These include ADT Partner Services installing select products for Apple Retail customers, ADT Blu's expansion to Walmart.com, and Origin AI presence sensing targeted for a 2027 commercial launch. The key risks are completion risks: stockholder approval, U.S. antitrust clearance, and Thrive's mix of equity, debt and preferred financing.
The market has repriced the stock accordingly. Shares are up 34.7% since the open following the July report. They sit 38.5% above the 200-day moving average and within 1.7% of the $10.00 high set on October 29, the deal announcement date. That high was also a 52-week high, coming less than a month after the stock hit a 52-week low of $6.03 on October 1. Investor sentiment improved meaningfully, from -0.51 to -0.10. It remains slightly negative, which is consistent with a stock whose upside is now effectively capped by the offer price.
The bottom line is that ADT's third quarter showed accelerating, lower-margin revenue growth layered on a flat-to-shrinking recurring base, softer EBITDA and decelerating cash flow. Those details would ordinarily invite debate about the earnings miss. With a $10 cash offer on the table and the stock trading just below it, the investment setup now hinges on deal completion and whether the go-shop produces a better bid. The quarter itself matters far less.
Read our earnings preview for ADT Inc.: https://www.earningswhispers.com/article/ADT/21452
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 11 hours | |
| 12 hours | |
| Nov-02 | |
| Nov-02 | |
| Oct-30 | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-28 | |
| Oct-27 | |
| Oct-26 | |
| Oct-20 | |
| Sep-14 |
