Williams Misses The Whisper On A Record Quarter As Build-Out Costs And JV Dilution Cap EPS; Reaffirmed Guidance Shifts The Burden To Power Deals
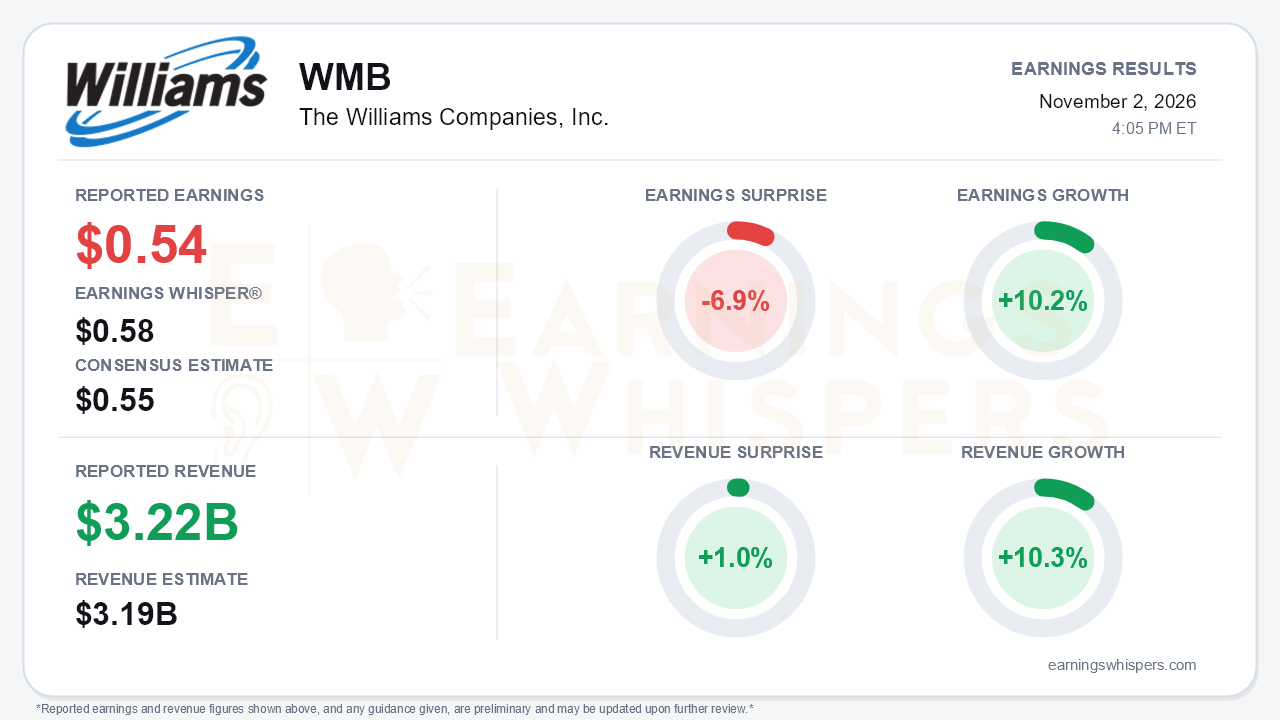
Williams (NYSE: WMB) posted record third-quarter results that still fell short of the market's bar. Adjusted EPS of $0.54 came in a penny below the $0.55 consensus and well short of the $0.58 Earnings Whisper number, a 6.9% miss. Revenue of $3.223 billion topped the $3.19 billion consensus by 1.0% and grew 10.3% year over year. Earnings grew 10.2%. Adjusted EBITDA reached a third-quarter record of $2.039 billion, up 6%, and management reaffirmed 2026 EBITDA guidance of $8.3 billion to $8.5 billion while saying it is tracking toward the upper half. That is the central tension. The asset base is growing quickly, but the cost of building and financing that growth is absorbing more of the top line before it reaches common shareholders.
The quality of the quarter deserves scrutiny in both directions. GAAP EPS of $0.56 exceeded the adjusted figure only because of an $83 million gain on the sale of a Permian gathering system, which Williams excluded from adjusted results along with $63 million of acquisition and JV formation costs. Below those one-time items, the pressure is real. Operating and administrative costs in Transmission, Power & Gulf jumped to $353 million from $290 million a year earlier, and in the West to $215 million from $150 million as Momentum Midstream was folded in. Interest expense rose to $385 million.
The financing structure is also changing what reaches common shareholders. Net income attributable to noncontrolling interests nearly doubled to $67 million from $36 million after Williams sold a $3.7 billion partial stake in a consolidated subsidiary. Diluted shares also climbed to 1.239 billion from 1.225 billion. The weaker pockets were Gas & NGL Marketing, where adjusted EBITDA fell to $4 million from $11 million, and the Other segment, which dropped to $62 million after the South Mansfield upstream sale.
Beneath the headline, the core franchise is healthy and in places improving. Transmission, Power & Gulf adjusted EBITDA rose $83 million, or 9%, on initial power-generation revenue from Socrates and higher storage revenue. Northeast G&P grew 7%, building on Q2's 8% after only 2% in Q1. The West grew 9% versus 5% in Q2. The deceleration story is at the consolidated level: 6% EBITDA growth matched Q2 but trailed Q1's 13%, and the year-to-date pace slipped to 9% from 10%. After raising guidance earlier in the year, management held both the range and growth capex steady this time. On adjusted EPS, the reaffirmed $2.35 midpoint against $1.77 earned year to date implies a fourth quarter near $0.58, the very number investors were looking for this quarter.
The call preserved a credible growth story and added specifics. Momentum closed a month early, and management said synergies are arriving well ahead of a model that originally assumed 2028. Socrates' second phase is entering service early and on budget. Management framed one to two additional power projects by year-end more concretely than in Q2, citing new hyperscaler counterparties, longer tenors and larger phased scope. Transco commercialization continued with Southeast Supply Enhancement II, which could reach 390 MMcf/d with an additional customer, and an upsized Garden Connector at 144 MMcf/d. A newly disclosed compensation framework ties pay to a 10% to 16% EBITDA growth rate through 2030 with leverage at or below 4.0x, signaling ambition well above the official 11%-plus target.
Bears have legitimate ammunition. The Third Circuit remanded NESE's New Jersey certificate, putting next-winter timing at risk, although management says the financial impact is immaterial. JV cost of capital has moved above the 6.35% Blackstone deal as Treasury yields rose. Williams also carries $5.9 billion of long-lead equipment commitments for unsanctioned projects, though these are partly cancellable or backstopped. Quarter-end leverage ticked up to 3.80x from 3.73x, capital investment excluding acquisitions more than doubled to $2.7 billion, and financing for the next power projects remains undetermined.
Investor sentiment remained positive but weakened meaningfully, falling to 0.20 from 0.36 at the prior report. That suggests enthusiasm was already cooling before the miss. Shares have gained only 2.3% since opening at $69.57 after the August report and, at $71.19, sit about 1.7% below the 200-day moving average. The Earnings Whispers trend signals are mostly positive, with sequential growth, momentum and AVWAP constructive while price trend is neutral. That mix fits a stock whose fundamentals keep advancing while its share price lags.
The bottom line is that Williams delivered an execution quarter with a disappointing earnings line. Record EBITDA, early project delivery and a sharper power pipeline support the long-term thesis. However, rising operating costs, interest expense and minority-interest leakage are diluting near-term EPS. With guidance merely reaffirmed and the stock stuck below its 200-day average, the next catalyst is clear: announcing the promised power deals on acceptable financing terms.
Read our earnings preview for The Williams Companies, Inc.: https://www.earningswhispers.com/article/WMB/21450
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Oct-27 | |
| Oct-26 | |
| Oct-13 | |
| Sep-29 | |
| Sep-23 | |
| Sep-22 | |
| Sep-11 | |
| Sep-11 | |
| Sep-09 | |
| Sep-08 |
