MPLX Edges Past Consensus But Falls Short Of The Whisper As Its Firm 2027 Distribution Promise Softens
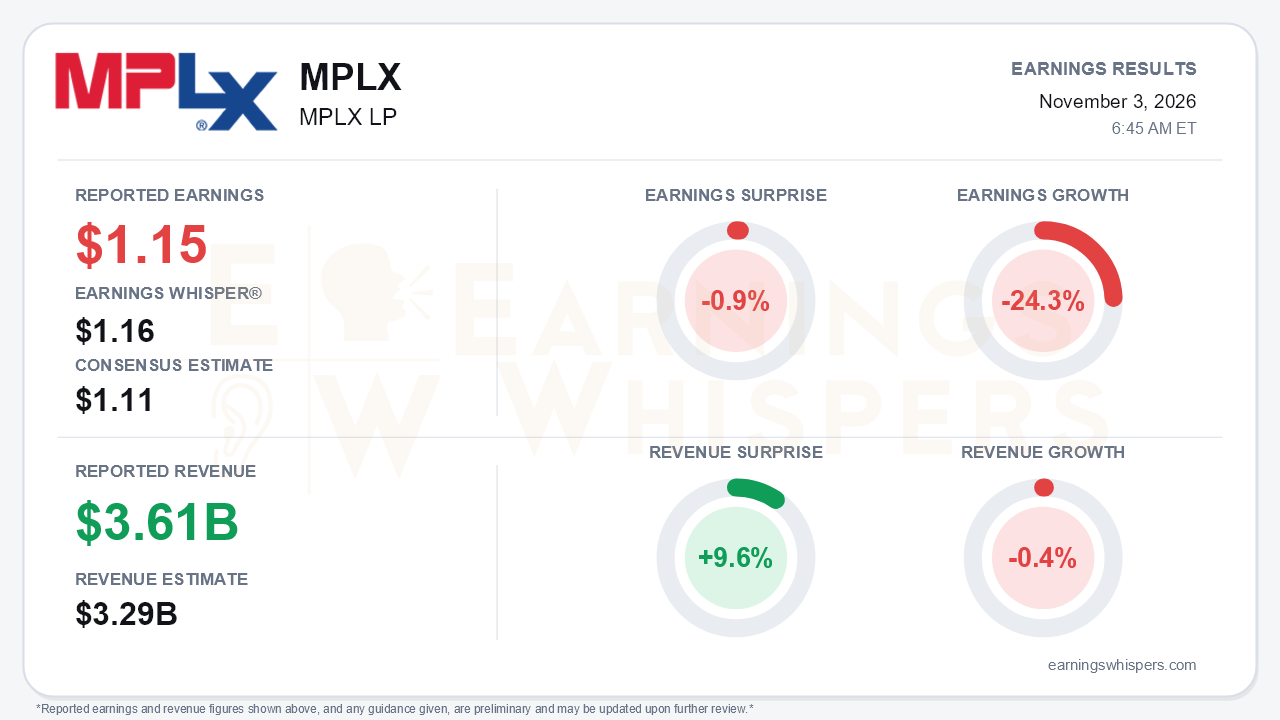
MPLX LP delivered a quarter in which the operating engine accelerated but the forward commitment weakened, and that is the central tension. The partnership reported third-quarter earnings of $1.15 per unit. That topped the $1.11 consensus but came in a penny below the $1.16 Earnings Whisper number, a 0.9% shortfall against the whisper. Revenue of $3.605 billion beat the $3.29 billion consensus by 9.6% but slipped 0.4% from a year ago. Earnings fell 24.3% year over year. Investors focused on that headline decline should know that last year's third quarter included a $484 million gain on equity method investments that did not recur. Net income attributable to MPLX fell to $1.164 billion from $1.545 billion, but the comparison flatters the prior period more than it indicts the current one.
The cash-flow metrics that drive MLP valuations tell a steadier story. Adjusted EBITDA rose 5.3% to $1.859 billion, and the call put underlying growth at roughly 7.3% excluding the divested Rockies assets. Distributable cash flow climbed to $1.537 billion from $1.468 billion, and coverage held at 1.3x. Beneath that, some lines warrant scrutiny:
- Incentive compensation, which the call tied to MPC's share price, more than doubled to $77 million and shaved about 2 points off EBITDA growth.
- Net interest costs rose to $300 million from $243 million.
- Leverage ticked up to 3.8x from 3.7x.
- Adjusted free cash flow after distributions remained negative at $645 million as growth capital jumped to $991 million from $645 million.
- Unit repurchases were halved to $50 million.
Operationally, the trajectory is clearly improving. Adjusted EBITDA has stepped up from more than $1.7 billion in the first quarter to $1.8 billion in the second and $1.9 billion in the third. The Crude Oil and Products Logistics segment added $67 million year over year, up from gains of $23 million in the second quarter and $14 million in the first. Higher rates, a 7% lift in product pipeline tariffs, and 6% terminal throughput growth drove that improvement. In Natural Gas and NGL Services, operated gathering volumes excluding divested assets rose 14%, and segment EBITDA grew about 10% ex-Rockies. Utica processing utilization jumped from 73% to 89% sequentially, and Northeast processing ran at 93% even after Harmon Creek III came online in August.
The catalyst slate also lengthened. The Solitude pipeline reached a final investment decision in under 90 days, lifting MPLX's interest in Permian long-haul gas capacity from roughly 11 to about 16 Bcf/d. Several projects are slated to start up in the fourth quarter:
- Bay Runner
- The BANGL expansion to 300 mbpd
- Blackcomb's full commercial service
The complication is the $750 million sale of logistics assets tied to MPC's St. Paul Park and Mandan refineries. The price, about 9x forecast 2027 EBITDA, is respectable, and proceeds are earmarked for Permian and Marcellus growth. Still, the sale creates a 2027 EBITDA hole that was not in the plan. Management had explicitly reaffirmed 12.5% distribution growth for 2027 on three consecutive calls. It now describes a "significant increase" that "may be impacted." The 2026 growth framing has also drifted from "stronger than 2025" to "mid-single-digit." Management still expects 2027 EBITDA growth to exceed 2026's, but bears have legitimate ammunition here.
Additional risks surfaced on the call:
- Titan II will not contribute in the fourth quarter, pushing its ramp into 2027.
- The EQT/Range consolidation creates a larger counterparty, though contracts run more than a decade.
- Management flagged roughly 20 Bcf/d of new Permian egress capacity against 7 to 8 Bcf/d of supply growth by 2030, raising overbuild concerns.
Investor sentiment remained positive but weakened modestly, slipping from 0.23 to 0.17 ahead of the report. Price action has been essentially flat. In the pre-report snapshot, shares sat at $58.94, virtually unchanged from the $58.97 open after the August report. That leaves the stock 3.0% above its 200-day moving average and 3.3% below the $60.95 52-week high set the day after last quarter's release. Shares have recovered from an October 1 low of $55.95, and the Earnings Whispers momentum and AVWAP trend readings are positive while price trend is neutral. In short, the market has been treating MPLX as a stable yield vehicle rather than rewarding the growth acceleration.
The bottom line is that MPLX's underlying business is improving faster than its headline earnings suggest, with accelerating EBITDA, rising utilization, and a deeper Permian project backlog. However, for an income-oriented investor base, the retreat from a firm 2027 12.5% distribution growth commitment matters more than a penny's miss against the whisper. Execution on the fourth-quarter start-ups and clarity on how the divestiture proceeds offset the lost EBITDA will determine whether that softened language proves to be caution or a genuine reset.
Read our earnings preview for MPLX LP: https://www.earningswhispers.com/article/MPLX/21498
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-29 | |
| Oct-27 | |
| Oct-26 | |
| Sep-23 | |
| Sep-17 | |
| Sep-17 | |
| Aug-17 | |
| Aug-17 | |
| Aug-10 | |
| Aug-06 | |
| Aug-04 | |
| Aug-04 |
