DocGo's Collapse To $0.21 Puts Cash, Margins And The HiQuity Deal On Trial
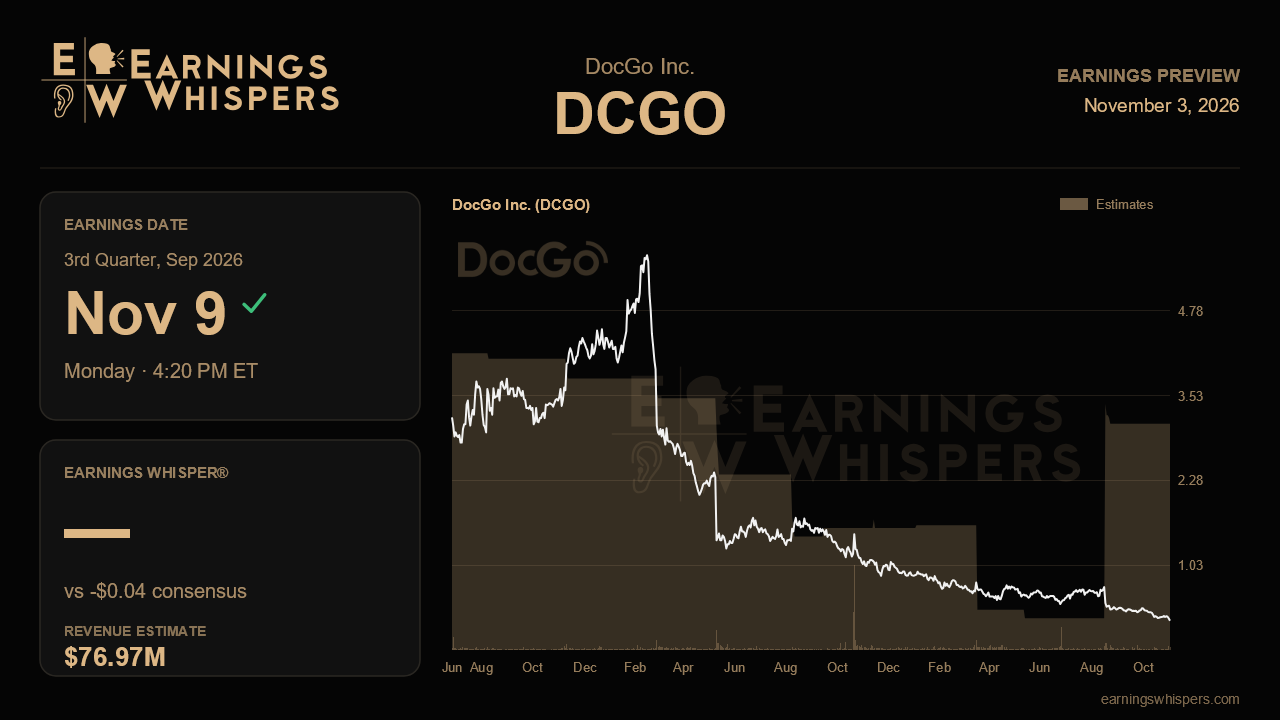
DocGo heads into its third-quarter report with a stock that has lost almost two-thirds of its value since the last update and a balance sheet that now matters more than its growth rate. The shares have dropped 62.7% since early August, trailing the S&P 500 by about 60 percentage points, and at $0.21 they sit at the very bottom of their post-earnings range and far below the 200-day moving average of $0.57. The market has punished the company harshly. Management's message, built around broad volume gains, a transformational acquisition and fresh financing, now has to stand up to a skeptical audience.
The Street's bar is modest on paper. Analysts expect a loss of $0.04 per share on revenue of about $77.0 million, against a loss of $0.11 and revenue of $70.8 million a year ago. That works out to sales growth of 8.7%, which is respectable but not spectacular, along with a sharply narrower loss. Full-year consensus of $307.9 million sits slightly above the midpoint of management's narrowed $305 million to $310 million outlook. That range has drifted steadily higher all year, from an initial $280 million to $300 million. A quarter near $77 million would keep that trajectory intact. A meaningful shortfall would be the first crack in the one metric that has consistently improved.
Profitability is where the real test lies. Last quarter management widened its adjusted EBITDA loss guidance to $17 million to $22 million, from $5 million to $10 million, about $12 million worse. The arithmetic behind that range is demanding. The first half already produced roughly $16.5 million of losses, combining $10.2 million in the first quarter and $6.3 million in the second. Reaching the guided range implies a second-half loss of only about $0.5 million to $5.5 million in total. In other words, management is effectively promising a sharp improvement starting now. A third-quarter EBITDA figure that continues the sequential climb would validate the plan. A result stuck near second-quarter levels would suggest the range is about to move again, and this year the guidance has moved in the wrong direction.
Gross margin is the hinge. Consolidated adjusted margin has slipped for four straight quarters, from 33% to 30.5%, and mobile health margins fell to 27% as SteadyMD hiring weighed on results. The company is counting on the reduction in force, which cut about $4.5 million from SG&A, and its AI efficiency programs, which carry roughly $6 million in potential savings, to do the heavy lifting. Evidence that mobile health margins have stabilized, that SteadyMD revenue recovered from its seasonal dip, and that transport margins held around 32% despite elevated fuel costs would go a long way. A pickup in organic growth from the second quarter's roughly 5% would also help ease concerns.
Then comes the balance sheet. Available cash fell to $25.2 million at midyear, and about $13 million of receivables tied to the New York City migrant program remained uncollected. Investors will want clarity on cash burn, on progress collecting that balance, and on the timing of the Perceptive Advisors financing and the HiQuity closing, which brings about $52 million of assumed debt. Any update on state approvals, customer consents or early cross-selling of in-home services into HiQuity's health-system clients will shape views of whether the deal is a growth engine or a leverage burden. The proposed CMS cut to remote patient monitoring reimbursement is a smaller but lingering risk.
Curious as it may seem, sentiment has improved to mildly bullish from clearly bearish a quarter ago, even as the stock crumbled. That gap suggests some holders see value at these levels, but the price says the market wants proof. The question this report must answer is simple: can DocGo show the margin repair and cash discipline needed to fund its expansion? Revenue in line will not be enough without a credible path to that second-half EBITDA improvement.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Sep-23 | |
| Sep-01 | |
| Aug-18 | |
| Aug-18 | |
| Aug-17 | |
| Aug-14 | |
| Aug-10 | |
| Jul-03 | |
| Jun-03 | |
| May-26 | |
| May-12 | |
| May-11 | |
| May-08 |
