Atea's Phase 3 Win Meets A Sliding Stock As Cash And C-Forward Timing Take Focus
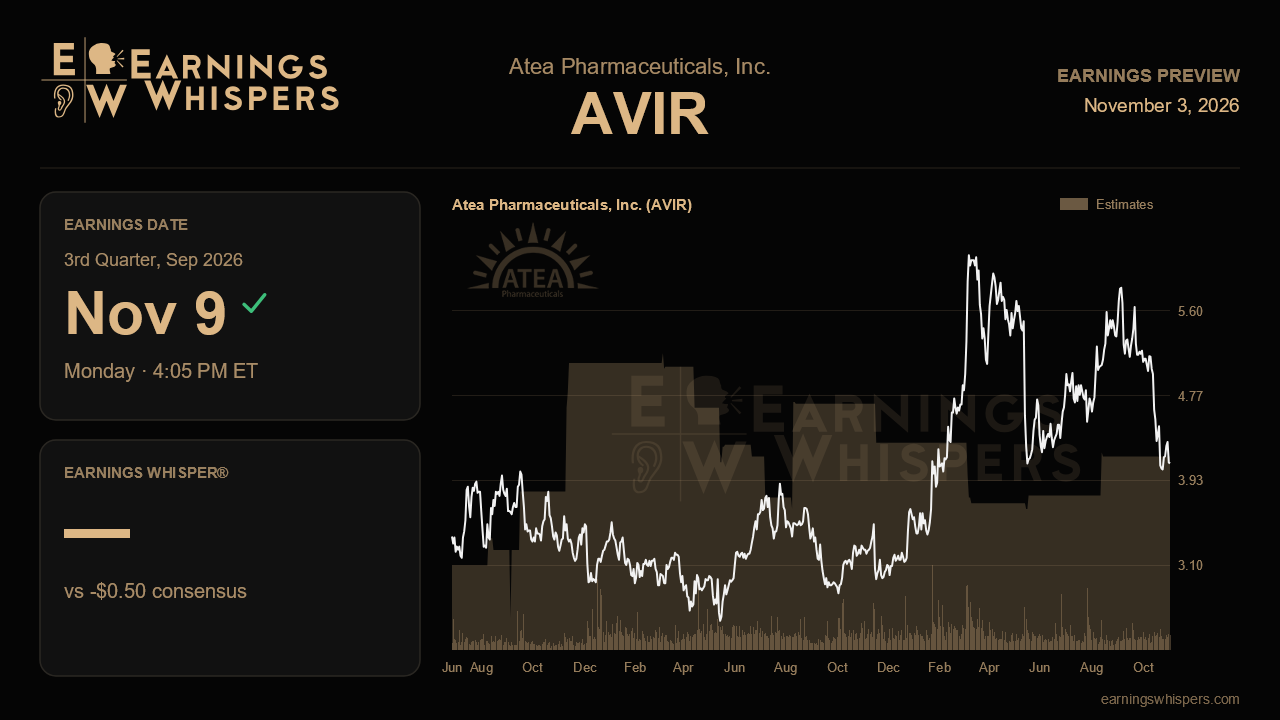
Atea Pharmaceuticals delivered the kind of pivotal trial result most small biotechs only hope for last quarter, and the stock has fallen more than 21% anyway. That disconnect is the real story heading into the company's third-quarter report after the close on November 9. With its hepatitis C combination of bemnifosbuvir and ruzasvir having cleared its first Phase 3 hurdle, the debate has moved away from whether the drug works. It now centers on whether Atea can stay on schedule and keep enough cash to reach a launch that is still nearly two years away.
The Street expects a loss of $0.50 per share. That would be about 5.7% narrower than the $0.53 loss a year ago, but meaningfully wider than the $0.41 loss reported last quarter. For a pre-revenue company, the per-share figure matters mainly as a proxy for spending. A sequential step-up in the loss would be consistent with a company running a fully enrolled second Phase 3 trial of more than 880 patients, launching a hepatitis E program and beginning to lay groundwork for an eventual commercial launch. Management has not offered formal financial guidance, so the cash balance is the cleaner test. Cash fell to $219.5 million at the end of June from $256 million in March, a quarterly drain of roughly $36 million. A burn rate in that neighborhood would support management's claim of runway through 2027. A noticeably larger draw would sharpen questions about financing ahead of a mid-2028 launch.
Operationally, the most important item is the C-Forward study, the second Phase 3 trial that stands between Atea and its planned new drug application. Its topline readout already slipped from around year-end 2026 to early first quarter 2027. That was a modest change, but it was a change. Investors should want management to restate the early 2027 timing without hedging and to confirm that the application remains on track for the second quarter of 2027. Another delay, even a short one, would push back the whole commercial calendar and stretch the cash cushion further.
CBEYOND also left some loose ends. The trial met non-inferiority against Epclusa, with 93.9% of patients cured versus 94.8%, and it did so using an eight-week regimen in non-cirrhotic patients against Epclusa's twelve weeks. However, the detailed per-protocol results and the data supporting a dual-mechanism label claim have yet to be presented. Discontinuation and loss to follow-up also exceeded 10%. Any update on scientific meeting presentations or FDA discussions would help confirm that the efficacy gap reflects real-world dropout rather than drug performance. Early progress in the AT-587 hepatitis E Phase 1 study, where the first cohort was completed quickly, would add evidence that the pipeline extends beyond a single asset.
The expectations backdrop is unusual. Sentiment has improved to about 69% bullish from 54% a quarter ago, yet the stock has lagged the S&P 500 by more than 18 percentage points. At $4.10, shares sit well below the 200-day moving average of $4.92 and close to the $3.93 low of the post-earnings range, far from the $5.90 high. The market appears to be discounting dilution risk and the long wait for revenue more than it is rewarding the clinical win. Atea's own estimate of more than $700 million in peak U.S. sales, along with research showing that 76% of high-volume prescribers are highly likely to use the drug, has not yet won over skeptics.
The central question is simple. Can Atea show that the path from a positive Phase 3 readout to approval is both on time and fully funded? A steady burn rate and reaffirmed C-Forward and NDA timelines would keep the improving narrative intact and could narrow the gap between fundamentals and the share price. Any new slippage, or vague language about funding, would suggest the market's caution has been justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-02 | |
| Sep-08 | |
| Aug-12 | |
| Aug-05 | |
| Jul-29 | |
| Jul-28 | |
| Jul-14 | |
| Jun-25 | |
| May-27 | |
| May-13 | |
| May-13 | |
| May-12 | |
| May-05 | |
| Mar-06 |
