Diversified Healthcare Trust Misses And Cuts FFO Guidance, But The Cut Is An Accounting Change While SHOP Fundamentals Improve
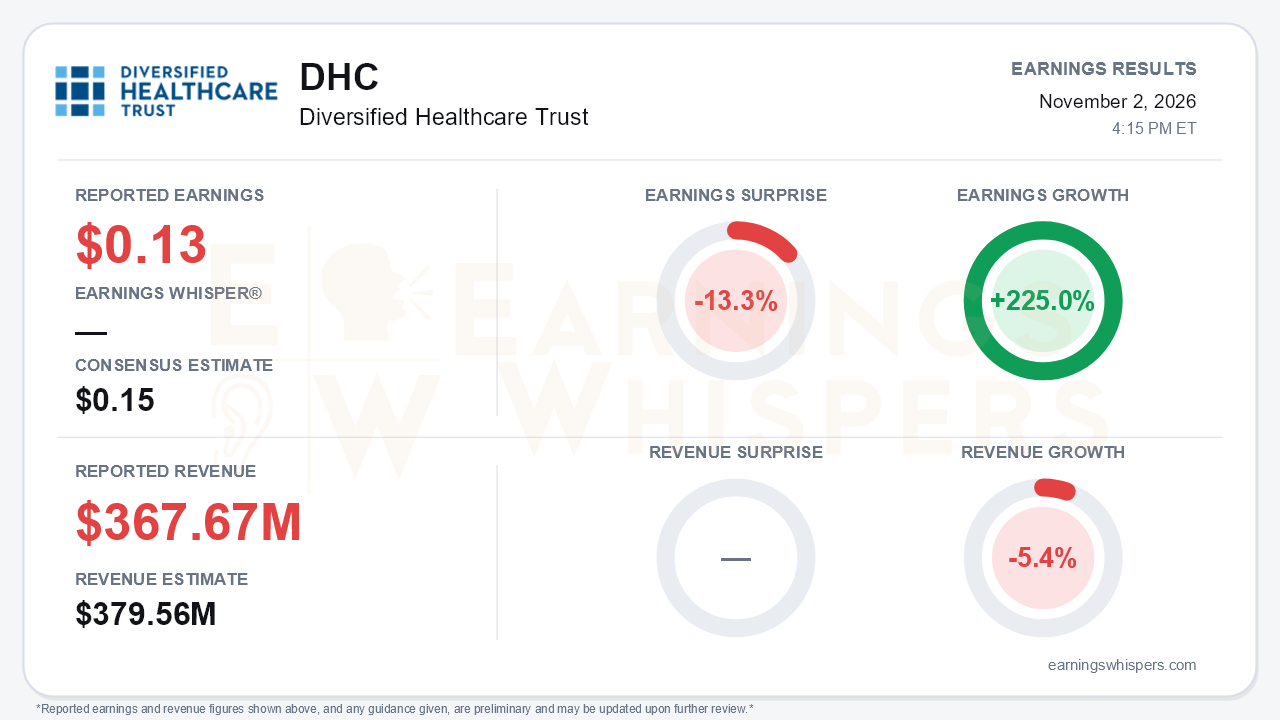
Diversified Healthcare Trust (NASDAQ: DHC) reported third-quarter normalized FFO of $0.13 per share, missing the $0.15 consensus by 13.3%. Revenue of $367.67 million fell 5.4% year over year and came in 3.1% below the $379.56 million estimate. The company also lowered full-year guidance. Taken at face value, that is a miss on both lines plus a cut. The headline misreads the quarter, though, and that is the central tension. Nearly all of the guidance reduction comes from a presentation change. DHC now includes incentive management fees in normalized FFO and adjusted EBITDA RE following SEC-driven guidance. Beneath that change, the senior housing operating portfolio (SHOP) delivered its strongest quarter of the year, and management raised its operating outlook for a second straight quarter.
The guidance math makes this plain. Normalized FFO guidance fell to $0.46-$0.52 from $0.56-$0.62. That reflects a $0.12 hit from the $29.3 million incentive-fee accrual, partly offset by a $0.02 improvement from operations. Adjusted EBITDA RE guidance dropped to $276-$291 million from $300-$315 million for the same reason. Investors should note that this accrual moves with DHC's share price, which makes it a volatile line item rather than a reflection of property performance. Year-over-year earnings growth of 225% is also hard to read cleanly. The call cited a recast prior-year figure, so the comparison is muddied by the same restatement. Still, adjusted EBITDA RE rose 28.4% to $73.4 million, which supports the view that underlying cash generation is improving.
SHOP is where the story is improving. Same-property SHOP NOI rose 50.4% year over year to $48 million, and growth has accelerated through the year:
- Q1: +13.5%
- Q2: +37.2%
- Q3: +50.4%
Margin reached 15.8%, up 470 basis points from a year ago. Occupancy climbed 130 basis points sequentially to 84.4%, the largest gain of the year. That follows a flat first quarter and a second-quarter cut to the occupancy target. Management now sees 500-600 basis points of further occupancy upside. Other raised metrics:
- SHOP same-property NOI guidance moved up to $190-$200 million, from $185-$195 million last quarter and $175-$185 million at the start of the year.
- The average monthly rate growth assumption edged up to 5.6%.
- Opex growth was trimmed to 2.3%.
- Recurring capex guidance fell $10 million at the midpoint to $90-$105 million.
Bears have legitimate ammunition. SHOP NOI fell 7.6% sequentially as the company lapped one-time benefits and absorbed roughly $1 million of nonrecurring costs plus seasonal utilities. Move-in concessions kept average monthly rate flat quarter over quarter. The SHOP revenue growth assumption slipped again, to 6.3% from 6.6%, well below the original 8.0%. That suggests occupancy gains are partly being bought with pricing. The medical office and life science segment is clearly weakening:
- Total occupancy dropped to 88.4% from 92.2%.
- Same-property cash NOI fell 1.6%.
- A Fremont life science tenant paying $2.2 million in annual rent leaves at the end of November.
Reported leverage rose to 8.2x including incentive fees, or 7.4x excluding them, compared with 7.1x in the second quarter. That matters with $500 million of notes due in February 2028.
The catalyst list grew meaningfully:
- **Ensign lease:** A 15-year triple-net lease with Ensign Group on seven Colorado skilled nursing facilities started October 1. It carries about $8 million of first-year rent, compared with $5.1 million of trailing NOI, or about $3.5 million after capex. Management estimates an 80 basis point lift to pro forma SHOP margin.
- **Management agreements:** New agreements across 76 legacy SHOP communities take effect January 1, 2027, with about $2 million of annual savings.
- **Conversion program:** The skilled nursing wing conversion program expanded to 13 communities and about 356 units, up from 6 communities and 150 units, targeting mid-teens returns with 2027 starts.
- **Operator change:** Six Georgia communities are moving to a new regional manager.
- **Medical office dispositions:** Sales aim to remove about $2.8 million of annual negative NOI.
The market had not been rewarding the story before the report. Shares at $7.74 were down 11.0% from the $8.70 open after the August report. They sat essentially on the 200-day moving average of $7.77. Investor sentiment moved more decisively, swinging from slightly negative (-0.09) to modestly positive (+0.18). That suggests expectations were rebuilding even as the stock drifted. The Earnings Whispers trend readings are mixed: momentum is positive while AVWAP remains negative. That fits a stock caught between improving fundamentals and lingering skepticism.
The bottom line is that DHC's miss and guidance cut are mostly optics. Operationally, guidance moved up, and the SHOP turnaround is gaining traction through occupancy, margin, capex discipline and a growing list of asset-level actions. The quality concerns are real, however. Flat pricing amid concessions, a deteriorating medical office segment and higher reported leverage mean the improvement is concentrated in one segment. With shares parked at the 200-day average after a quarter of declines, the next test is whether occupancy gains can translate into rate growth without further concessions.
Read our earnings preview for Diversified Healthcare Trust: https://www.earningswhispers.com/article/DHC/21385
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-12 | |
| Oct-08 | |
| Oct-06 | |
| Oct-06 | |
| Sep-21 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-09 | |
| Jul-06 | |
| Jun-01 |
