McEwen Must Show Gold Bar Recovery Fix As Shares Sit Near Post-Earnings Lows
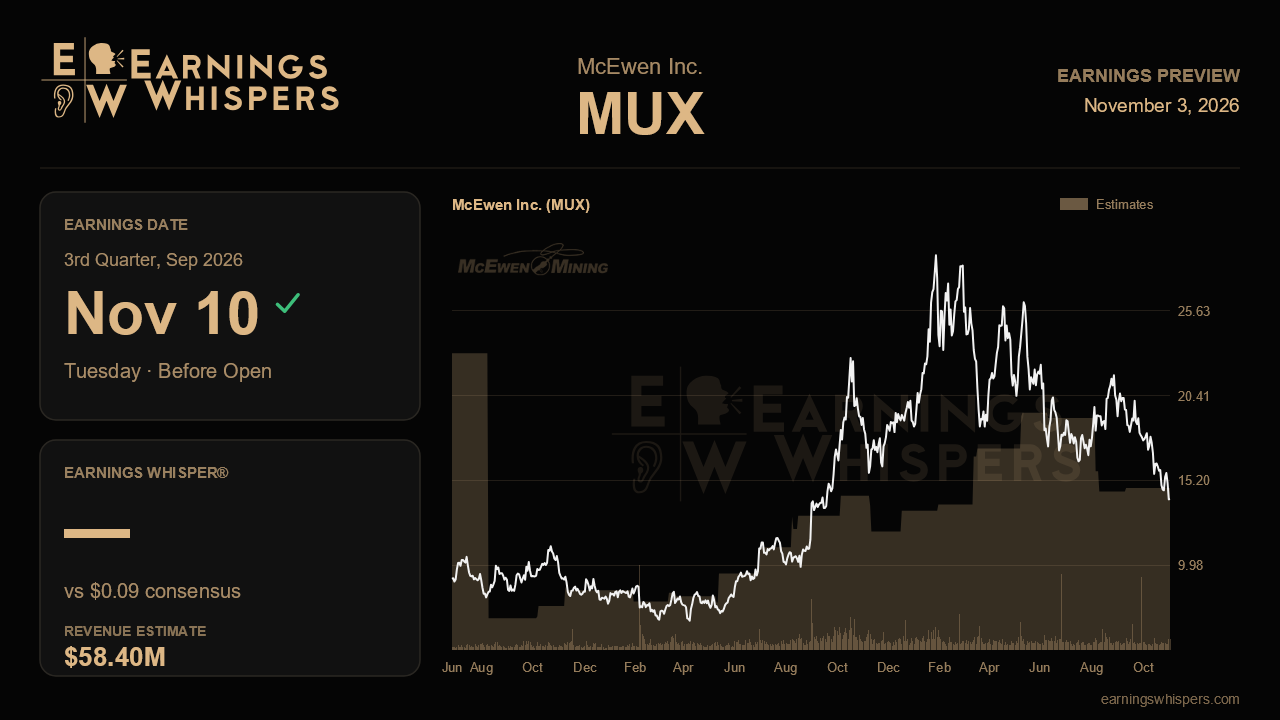
McEwen enters its third-quarter report with an awkward split personality. The long-dated Los Azules copper project keeps checking boxes, while the gold mines that pay today's bills stumbled badly last quarter. Management opened its previous call by conceding the quarter was not what it wanted, citing production below plan and costs it considered unacceptably high. The November 10 release, due before the open, is the first chance to see whether that admission marked the bottom of a rough patch or the start of a longer slog.
The Street expects earnings of $0.09 per share on revenue of $58.4 million. That compares with a $0.01 loss a year ago, which explains the eye-catching expected EPS growth of roughly 1,000%. That figure says more about a near-zero base than about a breakout. Revenue is projected to rise about 15.6% from $50.5 million but to slip slightly from last quarter's $59.2 million, and the EPS estimate sits below the prior quarter's $0.14. In other words, analysts are already modeling a modest sequential step back. That seems a sensible acknowledgment that the Gold Bar problems did not disappear when the calendar turned.
The core issue is metallurgy, not geology alone. Gold Bar ran into more carbonaceous, preg-robbing ore than expected, material that soaks up dissolved gold and drags down recoveries. That forced a downward revision to the mine's full-year production outlook and pushed all-in sustaining costs higher as a largely fixed cost base was spread across fewer ounces. Management said sequencing and blending changes were underway. This report should show whether those changes are working. Stabilizing or improving recoveries, better reconciliation between modeled and mined grades, and production tracking the revised guidance rather than undershooting it again would validate that fix. Another shortfall, or a second guidance trim, would turn what management framed as an execution lapse into a recurring credibility problem. Costs deserve equal scrutiny. Management flagged that each $1 per gallon move in diesel shifts AISC by roughly $100 an ounce, so energy costs are a meaningful swing factor on top of the volume issue.
On the copper side, the bar is about continuity. Engineering for the Los Azules final investment decision work program was about 27% complete at June and was slated to finish in the fourth quarter, so an update showing that pace holding would be reassuring. Investors should also want concrete progress on the roughly $4 billion financing package. That includes Societe Generale's work as exclusive debt advisor, the enhanced Finnish export credit proposal tied to Metso, IFC's arranger role and the equity layer, which includes a McEwen Copper IPO targeted for later this year. Any slippage in IPO timing would matter because it is a key piece of the funding plan. Updates on the new royalty and possible portfolio spin-out, and on the resumption of San Jose dividends expected next year, are secondary but supportive.
The market has delivered its verdict on last quarter in blunt terms. Shares have fallen 25.5% since the prior report, trailing the S&P 500 by more than 23 percentage points. At $14.05, the stock trades well below its 200-day moving average near $20.77 and only a few percent above its post-earnings low of $13.58, a far cry from the prior quarter's $16 to $26 range. Sentiment has also soured, with bearish readings climbing to 52% from 44% heading into the last report. That pessimism lowers the hurdle somewhat, but a stock sitting near its lows can also break lower if the gold story fails to steady.
Ultimately, this quarter turns on Gold Bar. If recoveries improve and costs stop climbing, the market may start crediting the Los Azules progress again. If the carbonaceous ore problem persists, copper optionality alone may not be enough to repair confidence in near-term execution.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-02 | |
| Oct-12 | |
| Oct-09 | |
| Sep-17 | |
| Sep-10 | |
| Sep-10 | |
| Aug-27 | |
| Aug-24 | |
| Aug-10 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Jul-30 |
