Icahn Enterprises: CVR Windfall And A Refinery Deal Lift NAV $865 Million, But A $522 Million Hedge Loss Keeps Holdco Liquidity Under Pressure
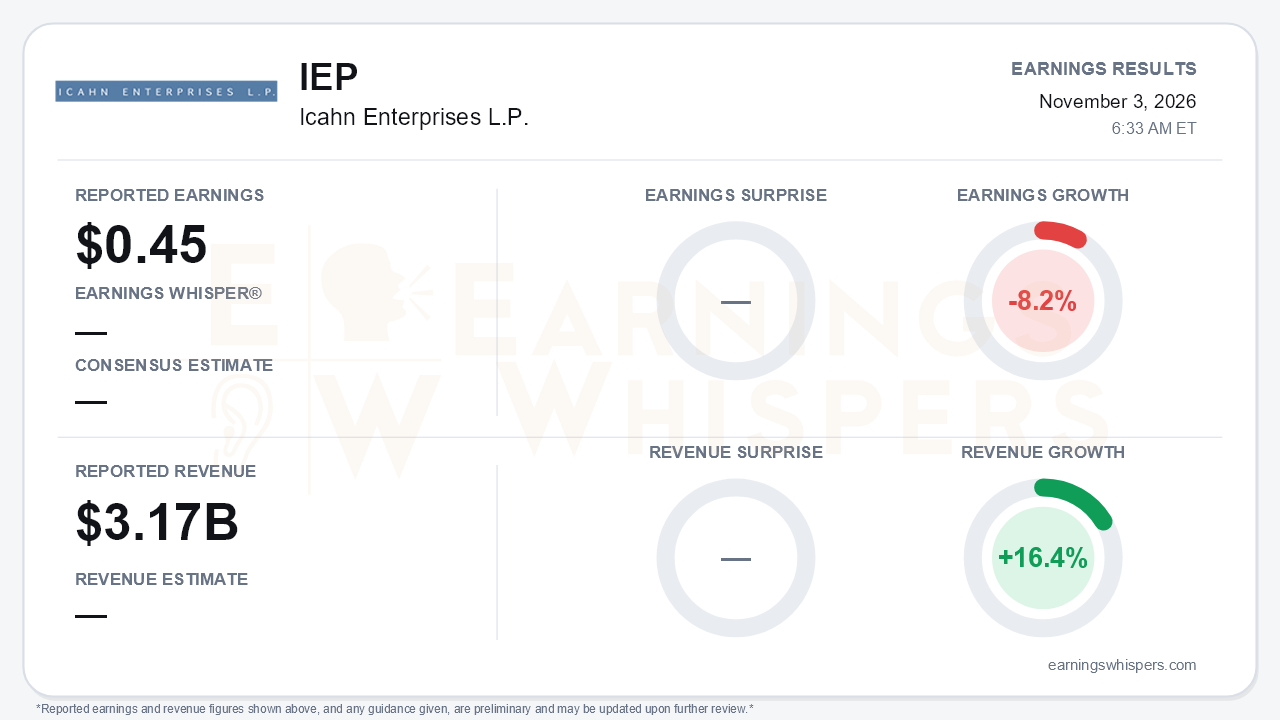
Icahn Enterprises (NASDAQ: IEP) delivered a quarter in which the value of what it owns rose sharply while the cash and flexibility of the holding company kept shrinking. On Earnings Whispers' normalized basis, IEP earned $0.45 per unit on revenue of $3.171 billion. That figure was down 8.2% from a year ago, while revenue grew 16.4%. There was no consensus or Whisper figure to measure the result against. The GAAP picture is far harsher: a net loss attributable to IEP of $225 million, or $0.31 per unit, against net income of $287 million, or $0.49, in the year-ago quarter. The gap between the two measures is the quarter's story in miniature. Mark-to-market swings, hedge losses and one-time gains dominate reported results, and the real development happened outside the income statement. Indicative net asset value rose $865 million in the quarter to roughly $3.5 billion. Nearly all of that came from a $1.7 billion gain in the value of IEP's stake in CVR Energy (CVI), which is not captured in earnings.
The quality of the quarter deserves scrutiny from both directions. The investment funds lost 31.3% including refining hedges, producing a $522 million loss attributable to IEP. That is the main reason Adjusted EBITDA attributable to IEP widened to a $214 million loss, from a $134 million loss in Q2 and positive $75 million a year ago, though the year-ago figure was recast under a revised methodology. GAAP results also absorbed a $165 million impairment, with goodwill falling sharply since year-end. On the other side, they were cushioned by a roughly $210 million gain on disposition of assets, largely the $215 million pre-tax gain on the Pep Boys sale, and a $223 million favorable revaluation of the RFS liability. Strip those offsetting items away, and the operating core is clearly CVR. Energy segment adjusted EBITDA reached $404 million, up from $102 million in Q2, negative $5 million in Q1 and $98 million a year ago. Record mid-continent crack spreads and a 100% small refiner waiver at Wynnewood drove the gain.
That creates an awkward irony. IEP's funds were hedged against the same refining strength that made CVR so valuable, so the holding company effectively lost on one side of the trade what it gained on the other. Even excluding hedges, the funds fell 5.5%. Their top holding, Sentry, dropped 34%. Meanwhile, net long exposure ex-hedges was raised to 57% from 23% in Q2, a far more aggressive posture heading into the fourth quarter. Elsewhere the improvements were real but small: food packaging adjusted EBITDA turned positive year over year after several quarters of declines, real estate gained $11 million, and the pharma trial expanded to four active sites. Automotive revenue fell $175 million on the Pep Boys exit.
The forward catalyst is CVR's $4.2 billion acquisition of two refineries and a marketing platform from Marathon Petroleum. The price is under 3.5 times management's 2026 EBITDA estimate. CVR says the deal lifts nine-month EBITDA from about $900 million to roughly $2.0 billion pro forma, with per-share earnings accretion above 105%, before $75 million of targeted synergies. Management's tone turned noticeably more assertive, calling the deal "transformative" and "highly accretive." IEP said NAV rose roughly another $585 million in October. Those are management's projections, and integrating an acquisition of this size carries real execution risk. IEP has also committed a $500 million backstop to a CVI equity raise, which it expects not to need, alongside a CVI secondary transaction intended partly to provide liquidity to IEP itself.
That liquidity need is why bears still have legitimate ammunition. Holdco cash plus fund investment has declined every quarter, from $3.5 billion at the end of 2025 to $2.3 billion now. The fund stake alone shrank to about $1.4 billion from roughly $2.0 billion in Q2. Subsidiary cash and revolver availability fell to $582 million from $1.4 billion. Holding company debt still stands at $4.4 billion against $921 million of holdco cash, and the May 2027 notes have yet to be addressed. The $0.50 distribution was maintained, but it defaults to payment in units. Units outstanding have climbed from 637 million at year-end to 757 million, and equity attributable to IEP fell to $746 million from $1.94 billion. No formal guidance was offered.
Sentiment data and a current price were unavailable for this review. For reference, the units opened at $7.56 after the August report, just above a 200-day moving average now at $7.41. That is a modest starting point for a quarter that delivered a large NAV gain.
The bottom line is that IEP's value story has become, more than ever, a CVR story. The refinery deal and record cracks have meaningfully rebuilt NAV. However, the hedge losses, a shrinking fund base, falling subsidiary liquidity and a looming 2027 maturity mean the holding company has not yet turned asset value into financial flexibility. How the CVI equity transactions and the note refinancing unfold will matter more than any single quarter's earnings figure.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-27 | |
| Sep-21 | |
| Aug-20 | |
| Aug-17 | |
| Aug-14 | |
| Aug-14 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Jul-23 | |
| Jul-23 |
