New Mountain Finance Covers Its Dividend Again, But NAV Erosion And Weaker Income Quality Overshadow An In-Line Quarter
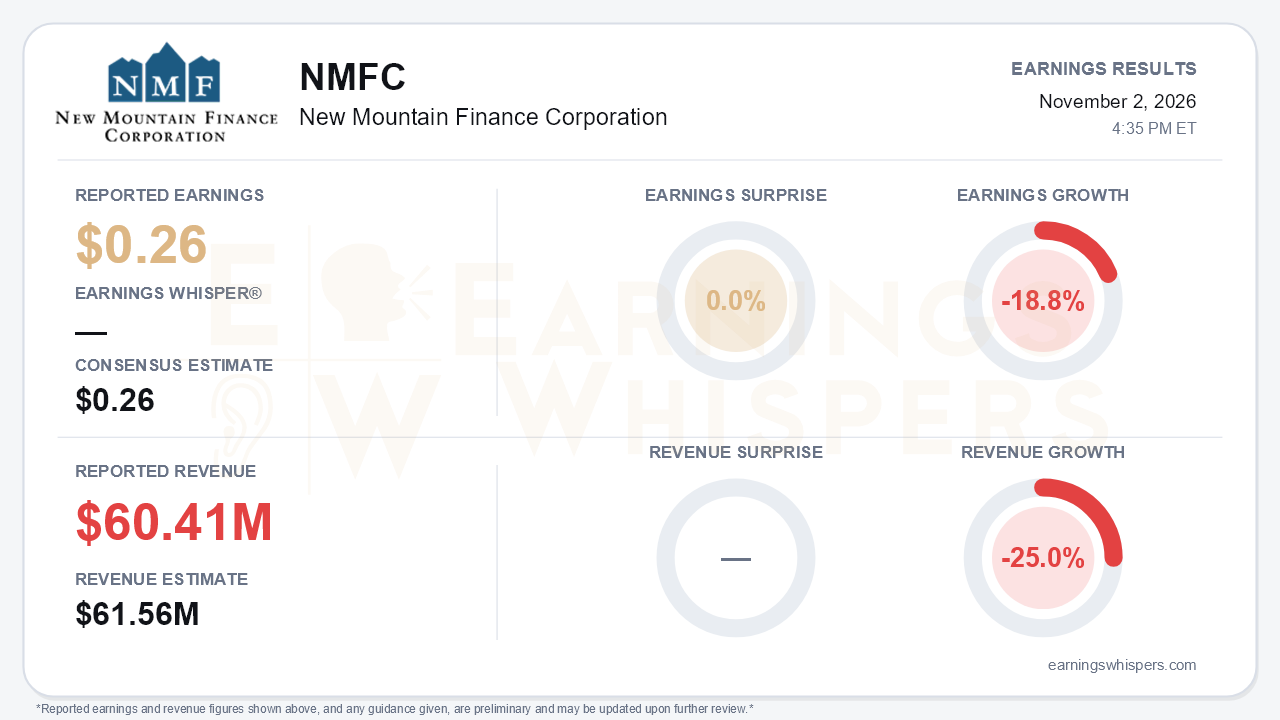
New Mountain Finance Corporation (NASDAQ: NMFC) delivered exactly what consensus expected on the headline. Adjusted net investment income was $0.26 per share, matching the $0.26 estimate and covering the newly reset $0.25 quarterly distribution for a second straight quarter. Nearly everything beneath that line moved the wrong way. Earnings fell 18.8% year over year. Total investment income of $60.41 million missed consensus by 1.9% and declined 25.0% from a year ago. Net asset value per share slid $0.22 to $10.67, a much steeper drop than the $0.03 decline in the second quarter. That is the central tension: dividend coverage held, but the asset base, credit profile and income quality supporting that coverage all weakened.
The quality of the in-line result deserves scrutiny. GAAP net investment income was $0.25, with the extra penny coming from adding back $0.6 million of accelerated deferred financing costs. Management and incentive fee waivers of $1.4 million also helped, though they were far smaller than the $4.5 million waived a year earlier. GAAP earnings were just $0.04 per share after $20.0 million of net realized and unrealized losses. Year to date, the company shows a net decrease in net assets from operations of $0.31 per share. NAV has now fallen from $11.52 at year-end 2025. According to the call, roughly $0.12 of the third-quarter decline reflected market discount rates and about $0.10 came from credit marks on Insight Software, Decadental and RLG.
The call made clear that the second-quarter narrative of stabilization did not play out. Non-accruals rose to 1.8% from 1.5%. The green-rated share of the portfolio fell to 86% from 88%, extending a steady slide from 95% at the end of 2025. Yellow-rated names climbed to 11.7% from 10.2%, which management tied to stress in older vintages. Income quality also deteriorated. Payment-in-kind income at origination rose to 15% of income from 13%. Modified PIK, where loans shift from cash pay to PIK, jumped to 5% from 3%. The green-rated share of PIK income dropped to 81% from 89%. A BDC leaning more heavily on non-cash income while its marks soften is not a combination income investors want to see.
The portfolio is also shrinking. Originations were just $10.3 million against $35.8 million of repayments and $8.1 million of sales. That compares with roughly $73 million of originations in the second quarter and $117 million in the first. The number of portfolio companies fell to 110 from 113. Management's tone shifted noticeably. Last quarter it spoke of more activity and equity exits within a quarter or two. This quarter it cited a roughly 28% year-to-date decline in industry direct-lending volume, stressed patience and announced no monetization. Total investment income has now stepped down from $77 million in the fourth quarter of 2025 to $69 million, $61 million and $60 million.
There are genuine offsets. The portfolio's weighted average yield rose to about 12%. The forward curve now prices rate increases rather than cuts, a tailwind for a loan book that is 88% floating rate. New deals are pricing at SOFR plus 475 to the 600s, with lower leverage and tighter documentation. On the balance sheet:
- The $150 million private placement covers 2027 maturities.
- Floating-rate liabilities reached 77%, above the 75% target.
- Post-quarter repayments from Thorne and Mercer Advisors cut pro forma leverage to 1.09x.
- The early fourth-quarter exit from Convey should trim non-accruals.
Management also pointed to double-digit earnings growth at Benevis, Unitec and Novus as groundwork for eventual equity exits. Bears, however, will note that no buybacks occurred this quarter. That is despite shares trading at roughly two-thirds of NAV and $79.5 million remaining under the extended authorization.
The market setup reflects that skepticism. Shares at $7.11 are down 3.0% since the opening after the August report and sit 7.2% below the 200-day moving average of $7.67. The annualized dividend yield is 14.2%, a level that signals doubt about durability. Investor sentiment remains clearly negative but improved from -0.65 to -0.50. Expectations were low enough that an in-line print and a covered dividend registered as modest relief. The Earnings Whispers trend readings are largely neutral, with the AVWAP trend still negative, consistent with a stock that has stabilized without regaining traction.
The bottom line is that NMFC protected its dividend but did not protect its book value. Rising rates, wider spreads and a cleaner liability structure give management real tools. Still, the quarter's direction of travel was negative: falling NAV, more non-accruals, heavier PIK reliance and a shrinking portfolio. Until monetizations materialize and credit migration stops, the deep discount to NAV looks more like a reflection of earned skepticism than an obvious mispricing.
Read our earnings preview for New Mountain Finance Corporation: https://www.earningswhispers.com/article/NMFC/21414
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-26 | |
| Oct-05 | |
| Sep-16 | |
| Sep-09 | |
| Sep-04 | |
| Sep-03 | |
| Sep-02 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-23 |
