Innoviz Must Show Its Robotaxi Ramp Is Real As Shares Sink Toward Lows
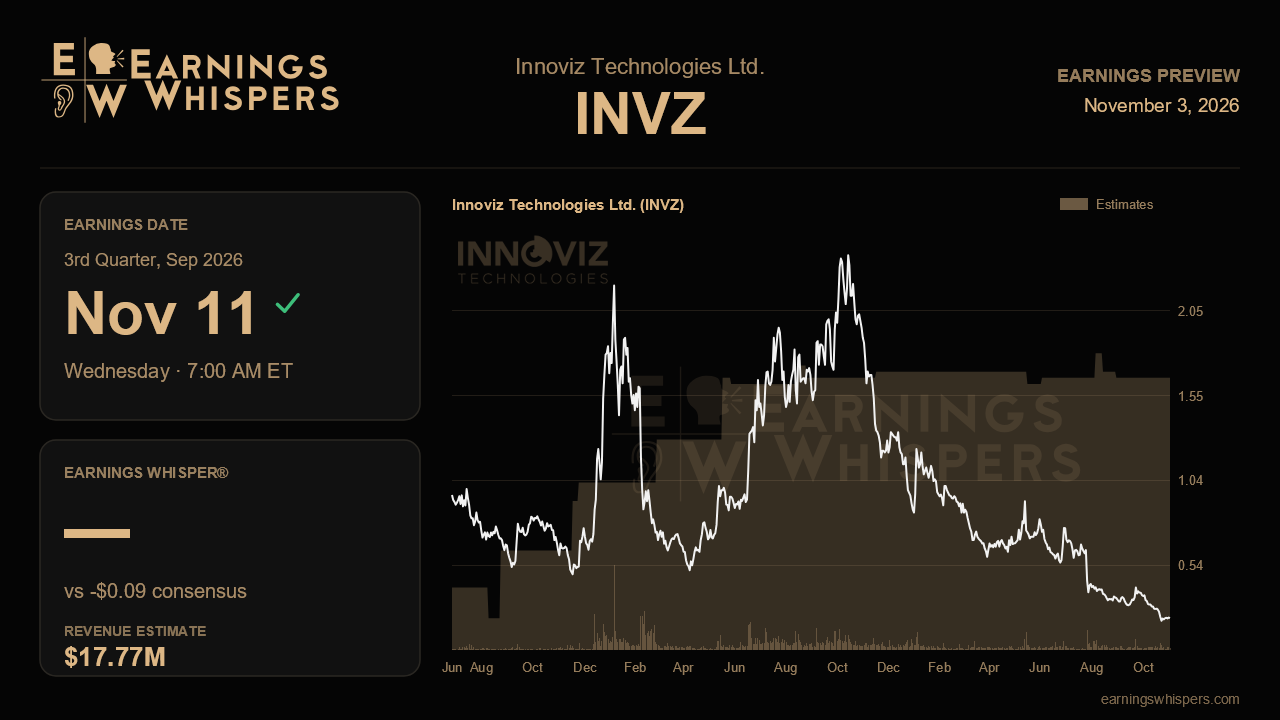
Innoviz heads into its third-quarter report with a striking disconnect between its story and its stock. Management has spent the past year describing a business crossing important thresholds: record revenue, the first sustained positive gross margins, a named Level 4 trucking win with Daimler Trucks and Torc, and a full-year 2026 outlook that it has continued to stand behind. Yet the shares have roughly halved since the last report, falling 49% while the S&P 500 slipped about 3%. The November 11 release, due before the open, has to answer whether the market is mispricing a real ramp or correctly sensing that the ramp is running late.
The Street's bar for the quarter is modest. Consensus calls for revenue of about $17.8 million, up roughly 16% from $15.3 million a year ago but slightly below the $18.1 million reported last quarter. The expected loss of 9 cents a share would be a penny wider than both the prior quarter and the year-ago period. In other words, analysts are not modeling sequential acceleration this quarter, which matters because the company's own narrative points to a back-half-weighted year. Innoviz has reaffirmed 2026 revenue guidance of $67 million to $73 million, and the full-year consensus of about $69.6 million sits just under the midpoint. That is a vote of reasonable confidence, but a flat third quarter would leave a heavier lift for the fourth.
The most important operating driver is the Volkswagen ID.Buzz robotaxi program. Management said series production, with nine lidars per vehicle, would support fleets in six cities during the second half of 2026, and it expected overall production volumes to rise three to four times this year. This report is the first real window into that second-half ramp. Evidence of rising unit shipments, firmer delivery schedules or commentary that fleet deployments are on track would validate the guidance. Any suggestion that vehicle timing has slipped into 2027 would challenge the core of the growth case, regardless of whether the quarter technically meets consensus.
Margins and engineering revenue are the second test. Innoviz reached a 23% gross margin in 2025 after running negative the year before, but management repeatedly warned that quarterly results would swing with the timing of non-recurring engineering payments and product mix. A dip tied to NRE timing would be tolerable; a decline driven by early production costs on new programs would be more concerning. The company entered 2026 with roughly $111 million in NRE payment plans, and updates on that pipeline, along with progress on the Level 3 development work with a top-five passenger carmaker targeting a 2027 start, will indicate whether future production revenue is genuinely being locked in. Management previously called the timing of that conversion hard to predict, so any concrete step would carry weight. The Innoviz 3 sensor, with its smaller footprint and lower cost, and the non-automotive security business, which management hoped could reach up to 10% of revenue this year, offer secondary signs of diversification.
Cash is the uncomfortable backdrop. The company launched a $75 million at-the-market equity program last year, and selling stock near 23 cents is far more dilutive than it was at prior-quarter levels above 80 cents. The shares trade well below their 200-day average of 61 cents and sit just above the post-earnings low of 21 cents. Curiously, sentiment has improved, moving from mildly bearish before the last report to mildly bullish now, suggesting some investors see the selloff as overdone.
Ultimately, this report turns on one question: can Innoviz show that its 2026 production ramp is arriving on schedule with enough margin and cash discipline to fund it? Reaffirmed guidance backed by visible robotaxi volume would go a long way toward repairing credibility. Hedged timing would confirm the market's skepticism.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Oct-28 | |
| Oct-22 | |
| Sep-17 | |
| Aug-31 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-30 | |
| Jul-28 | |
| Jul-21 | |
| Jul-16 | |
| Jul-14 | |
| Jul-08 | |
| Jul-07 |
