RUM Group's First Quake AI Quarter Puts Its Doubled Revenue Guidance And Cash Burn On Trial
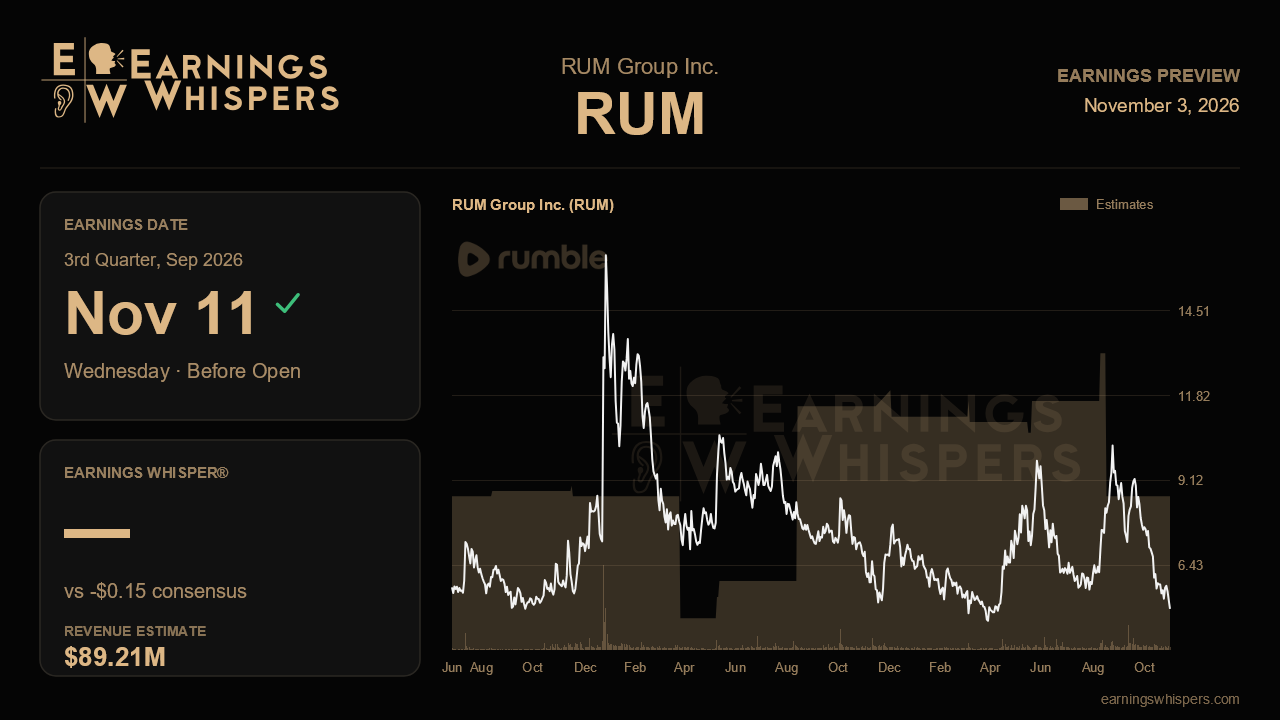
For years, the stock behind the Rumble video platform traded on promises. When RUM Group reports before the bell on November 11, it will finally have to show what the newly combined company looks like on paper. This is the first full quarter that includes Quake AI, the cloud and GPU business formed after the Northern Data acquisition closed in mid-June. It is also the first quarter measured against formal guidance, and the first with separate Rumble Video and Quake AI segment results. That is a lot of new disclosure arriving at once, and a stock that has been sliding into the report.
The Street expects revenue of about $89.2 million, up roughly 260% from $24.8 million a year ago and more than double the record $40.4 million posted last quarter. Management guided to $87 million to $93 million, so consensus sits comfortably inside the range, just below the $90 million midpoint. In practical terms, analysts have accepted the company's math without stretching it. Anything near the top of the range would show the integration is running ahead of plan, while a print near the low end would raise questions about how much of the acquired GPU fleet is actually generating revenue. On the bottom line, analysts see a loss of $0.15 per share, matching last quarter but nearly double the $0.08 loss a year ago. Revenue scale is arriving faster than profitability, and investors already know that.
The new segment reporting matters more than the headline numbers. Last quarter management said GPU utilization had climbed above 85%, up from 62% in December 2025. It also pointed to a multi-year agreement with Together AI for NVIDIA B300 systems as proof that an independent provider can win marquee customers and secure scarce chip allocation. Segment margins for Quake AI will help show whether that utilization turns into attractive economics or simply rented capacity at thin spreads. Any update on when the Together AI deployment begins contributing, and whether other customers have signed, would give some substance to management's claim that 250 megawatts of unmonetized power could support a run rate above $3 billion by 2027. For now, that figure is an ambition, not a contract.
The risk side is just as clear. Liquidity has fallen every quarter, from $306.4 million a year earlier to $220.5 million at the end of June. Investing outflows of about $47 million in the second quarter hinted at a heavy capital spending cycle still to come. Last quarter's $80.3 million net loss was inflated by $28.3 million of deal costs, so a cleaner quarter should look better. Higher depreciation, however, will keep GAAP results deep in the red. Further progress on adjusted EBITDA, which improved to a $16.6 million loss last quarter, would show operating leverage is real. A sharper cash drawdown without a funding plan would undercut it. The legacy video business also deserves attention as headline user metrics are retired, since its ad recovery remains a late-2026 and 2027 story.
The market has not given the company the benefit of the doubt. Shares are down nearly 16% since the last report, about 13 points worse than the S&P 500. At $5.05, they sit right at the post-earnings low of $5.02, well below the 200-day moving average near $6.71 and less than half the $10.60 peak reached after last quarter's call. Sentiment has cooled too, with bullish readings easing to 12.5% from 20.1%.
That skepticism sets a clear test. Hitting the guidance range is the minimum. What could change the conversation is evidence that Quake AI earns real margins on its capacity, and that the company can pay for the next leg of GPU buildout without straining its balance sheet. If both points hold up, the transformation story stays intact. If either falls short, the deep discount to recent highs may turn out to be justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Oct-28 | |
| Oct-07 | |
| Oct-06 | |
| Oct-05 | |
| Oct-05 | |
| Sep-30 | |
| Sep-29 | |
| Sep-14 | |
| Sep-14 | |
| Sep-14 | |
| Sep-14 | |
| Sep-14 | |
| Sep-14 | |
| Sep-10 |
