Regal Rexnord Beats And Raises On Accelerating Orders, But Refunds, Tax And IPS Plant Problems Cloud The Quality Of The Quarter
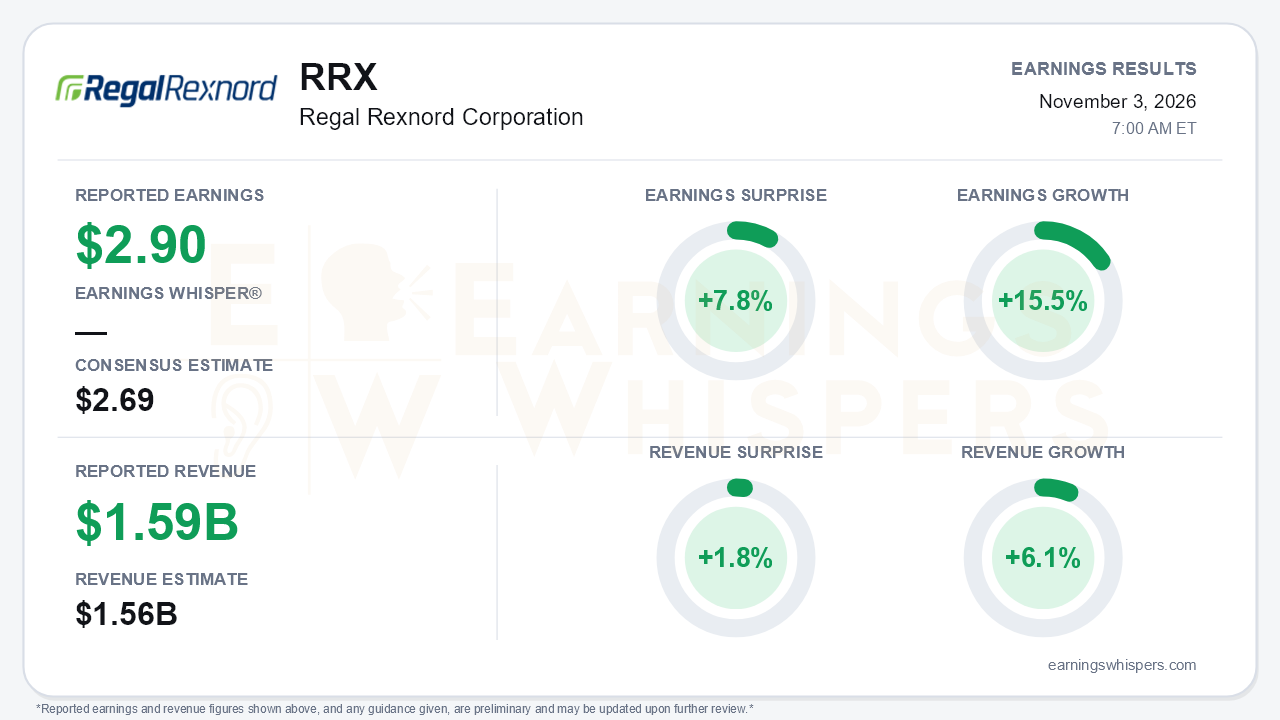
Regal Rexnord delivered a clean-looking beat for the third quarter. Adjusted earnings of $2.90 per share topped the $2.69 consensus by 7.8% and grew 15.5% year over year. Revenue of $1.588 billion beat the $1.56 billion estimate by 1.8% and rose 6.1%. The company also lifted the midpoint of its full-year adjusted EPS guidance to $10.75 from $10.60. The central tension is that demand is clearly accelerating while margins and execution are moving the other way. Much of the upside came from below the operating line rather than from the core business.
The quality of the beat deserves scrutiny. Adjusted EPS included an $0.18 net benefit from IEEPA tariff refunds. Excluding that item, earnings were $2.72, up 8.4% and only fractionally above consensus. On a GAAP basis, the company swung to a $0.19 per-share loss from a $1.20 profit a year earlier. The swing reflected a $119 million goodwill impairment tied mainly to the autonomous mobile solutions business, which is now being shopped. Adjusted EBITDA rose 4% to $351 million, but margin slipped to 22.1% from 22.7%. Gross margin excluding refunds fell about 80 basis points as price-cost turned into a bigger headwind. The full-year EPS raise is also not an operating upgrade: EBITDA dollar guidance was essentially unchanged, and the increase rests on lower depreciation and a structurally lower tax rate, now about 20.8% versus 21.5%. Meanwhile, the full-year adjusted EBITDA margin outlook excluding refunds has drifted down to roughly 21.2%, from 22.5% at the start of the year.
The top-line story is genuinely improving. Organic growth has stepped up from 1.6% in the first quarter to 3.3% in the second and 6.1% in the third. Daily orders rose 6%, or 13% excluding data centers. October orders accelerated to 24% growth. Automation & Motion Control grew 25% organically, helped by data center sales that more than quadrupled. Management now expects mid-teens growth for the segment, up from low double digits. Power Efficiency Solutions saw commercial HVAC orders surge on new data center air-moving products, and its margin outlook was raised about 70 basis points. The weak spot is Industrial Powertrain Solutions. Sales there fell 1.8% organically despite record orders, because plant throughput, material planning and supply-chain failures left a past-due backlog. Plant consolidations have been paused, recovery is expected to take a couple of quarters, and the segment's growth and margin outlook were cut for a second straight quarter.
The data center opportunity cuts both ways. E-Pod revenue for 2026 was pulled forward to $65 million from $15 million, a $113 million switchgear order was booked in October, and switchgear sales are tracking about $200 million. Yet the 2027 E-Pod framing now sits near $550 million, below the roughly $700 million implied earlier in the year. Project phasing also pushed AMC orders down 4.9% in the quarter. New CEO Aamir Paul has launched a comprehensive portfolio review with outside advisors, raising the possibility of further divestitures. He also signaled possible changes to talent, structure and cost. That is a credible catalyst, but it adds execution risk during a transition. On the balance sheet, net leverage improved to 2.9x. Nine-month free cash flow of $345 million, however, trails last year's $752 million, and the full-year target was already trimmed to $600 million last quarter.
The market had been bracing for trouble. Shares closed at $160.93 ahead of the report, down 16.6% from the open after the August release. That leaves them about 15% below the 200-day moving average and 18% below the inter-earnings high set on that same August day. The stock bounced 11% off its October 22 low of $144.52 heading into the print. Investor sentiment edged up but remains essentially neutral, signaling little conviction either way. Price and AVWAP trend readings are still negative.
The bottom line is that Regal Rexnord's quarter strengthened the growth narrative while weakening confidence in earnings quality. Accelerating orders, data center momentum and a portfolio reshaping give bulls a story the depressed share price does not reflect. Bears, however, have legitimate ammunition. The beat leaned on tariff refunds, the guidance raise leaned on tax and depreciation, IPS execution keeps slipping, and the margin outlook has eroded all year. The next few quarters will hinge on whether the new CEO can convert record backlog into deliveries without further margin compromise.
Read our earnings preview for Regal Rexnord Corporation: https://www.earningswhispers.com/article/RRX/21508
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| 15 hours | |
| 16 hours | |
| Oct-26 | |
| Oct-21 | |
| Oct-05 | |
| Sep-23 | |
| Sep-17 | |
| Sep-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-27 | |
| Jul-21 | |
| Jul-10 |
