Douglas Dynamics Posts Record Quarter But Falls Short Of Elevated Whisper As Cash Burn And Solutions Softness Temper A Narrow Guidance Raise
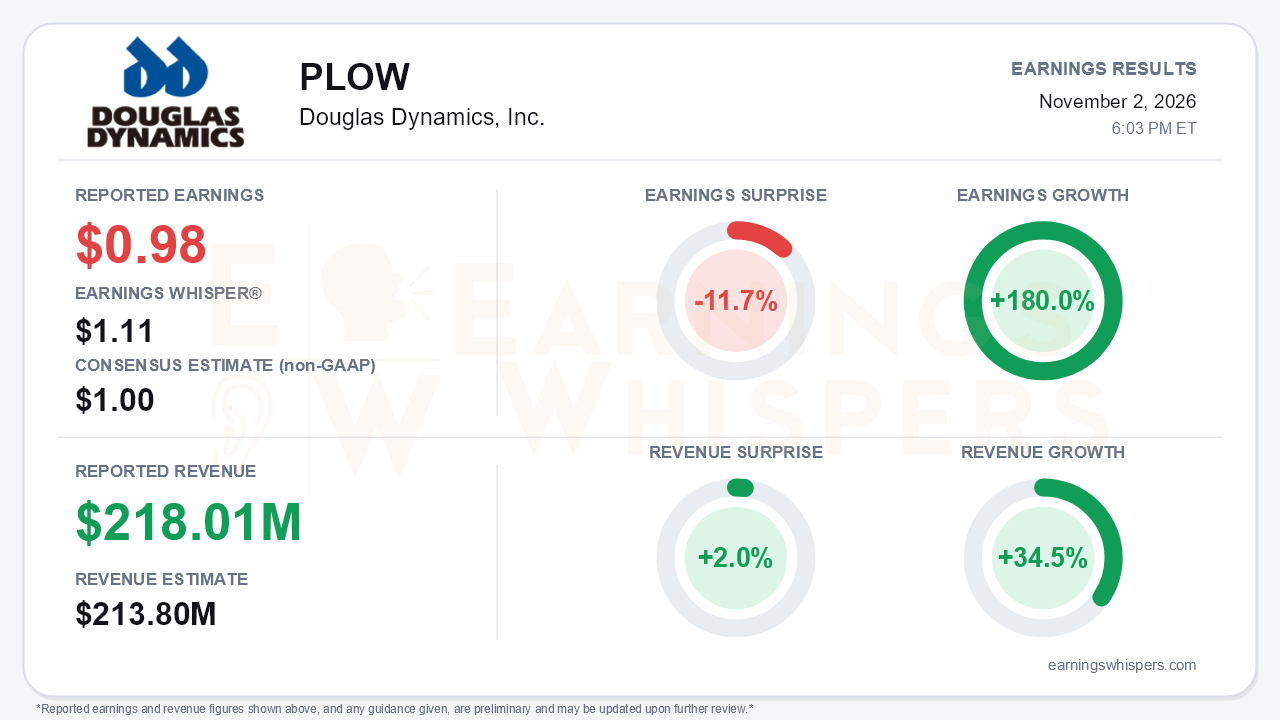
Douglas Dynamics delivered the best third quarter in its history and still missed what investors wanted. Adjusted EPS of $0.98 fell short of the $1.00 consensus and the $1.11 Earnings Whisper number, a miss of 11.7%. Revenue of $218.01 million beat the $213.8 million consensus by 2.0%. Earnings grew 180.0% year over year and revenue grew 34.5%, and GAAP diluted EPS rose to $0.89 from $0.33. That is the central tension. The operating results were strong in absolute terms, but they were not strong enough to clear an expectations bar that had risen with each guidance increase this year. The quarter also exposed a cash and working-capital strain that the headline growth obscures.
The quality of the growth deserves scrutiny. Nearly all of the improvement came from Work Truck Attachments. Segment sales jumped 78% to $121.5 million, and adjusted EBITDA margin expanded 945 basis points to 24.8%. Part of that gain reflects timing rather than a pure step-up in demand. Pre-season shipments split roughly 50/50 between the second and third quarters, compared with 60/40 in 2025, so revenue shifted into Q3. The year-over-year comparison was also flattered by the addition of Venco Venturo. Even so, the demand signals were real. Year-to-date parts and accessories shipments have already exceeded the 2025 annual record, and the nine-month Attachments margin of 23.6% has reached management's mid-20s target. Consolidated adjusted EBITDA rose 89% to $37.9 million, and margin widened to 17.4% from 12.4%.
The weaker half of the business went the other way. Work Truck Solutions grew sales just 3% to a record $96.5 million. Adjusted EBITDA, however, fell to $7.8 million from $9.6 million, and margin slipped to 8.1% from 10.2%, as inconsistent commercial demand offset steady municipal strength. On the call, the full-year outlook for Solutions was reframed as roughly flat, a retreat from earlier expectations for top-line growth. Fleet demand remains subdued. Consolidated SG&A rose about 19%, with legal costs among the pressures. The new Ohio upfit facility and the Henderson Iowa logistics site are expected to open around year-end. These are capacity bets on municipal demand that have yet to show up in segment profitability.
Cash is where bears have the most legitimate ammunition. Year-to-date free cash flow was negative $58.7 million, compared with negative $29.3 million a year earlier and negative $32.5 million at midyear. Receivables climbed to $217.8 million from $97.6 million at year-end, and short-term borrowings rose to $96 million. Liquidity dropped to $34 million from $69.4 million at Q2. Some of this is seasonal: dealers pay for pre-season orders as winter unfolds. Still, the pattern makes the fourth quarter's weather sensitivity more consequential than usual.
Guidance moved up for the third time this year, but the increase was noticeably smaller. Management raised only the low ends of its ranges:
- Net sales to $770–805 million
- Adjusted EBITDA to $123–135 million
- Adjusted EPS to $3.00–3.40
With $2.56 of adjusted EPS already booked through nine months, the range implies a fourth quarter that the call framed as roughly flat on EBITDA against a snowy Q4 2025 comparison. The guidance also assumes average snowfall. Looking further out, management offered an early view that 2027 could replicate 2026 under average snow, but it cautioned that record P&A volumes are unlikely to repeat. Catalysts include a sidewalk machine developed with John Deere, with order-taking expected in 2027, growing traction in pusher plows, more smaller commercial fleet orders, and a busier M&A pipeline.
The market setup is more complicated than the record results imply. Investor sentiment improved modestly, moving from -0.06 to +0.04. That shift takes sentiment from slightly negative to slightly positive, not to enthusiasm. The shares, at $39.87, are essentially unchanged (-0.3%) since the open after the August report and sit 7.4% below the 200-day moving average of $43.04. The Earnings Whispers trend readings are mixed: momentum is positive while price and AVWAP trends remain negative. The stock has not rewarded the string of guidance raises, which suggests investors were already discounting peak-cycle Attachments margins and weather risk.
The bottom line is that Douglas Dynamics executed exceptionally in Attachments and has effectively pulled its 2027 earnings ambitions into 2026. The miss against the whisper, the low-end-only guidance raise, softening Solutions profitability, and a sharp drop in liquidity all argue that the easy upside has been captured. From here, the fourth quarter's snowfall and the conversion of a swollen receivables balance into cash will matter more than another record headline.
Read our earnings preview for Douglas Dynamics, Inc.: https://www.earningswhispers.com/article/PLOW/21422
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-20 | |
| Sep-04 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-21 | |
| Jun-05 | |
| May-04 | |
| May-04 | |
| Apr-21 | |
| Mar-02 |
