UMH Properties Matches FFO Estimates As Operating Momentum Builds, But Guidance Stays Flat And Leverage Climbs
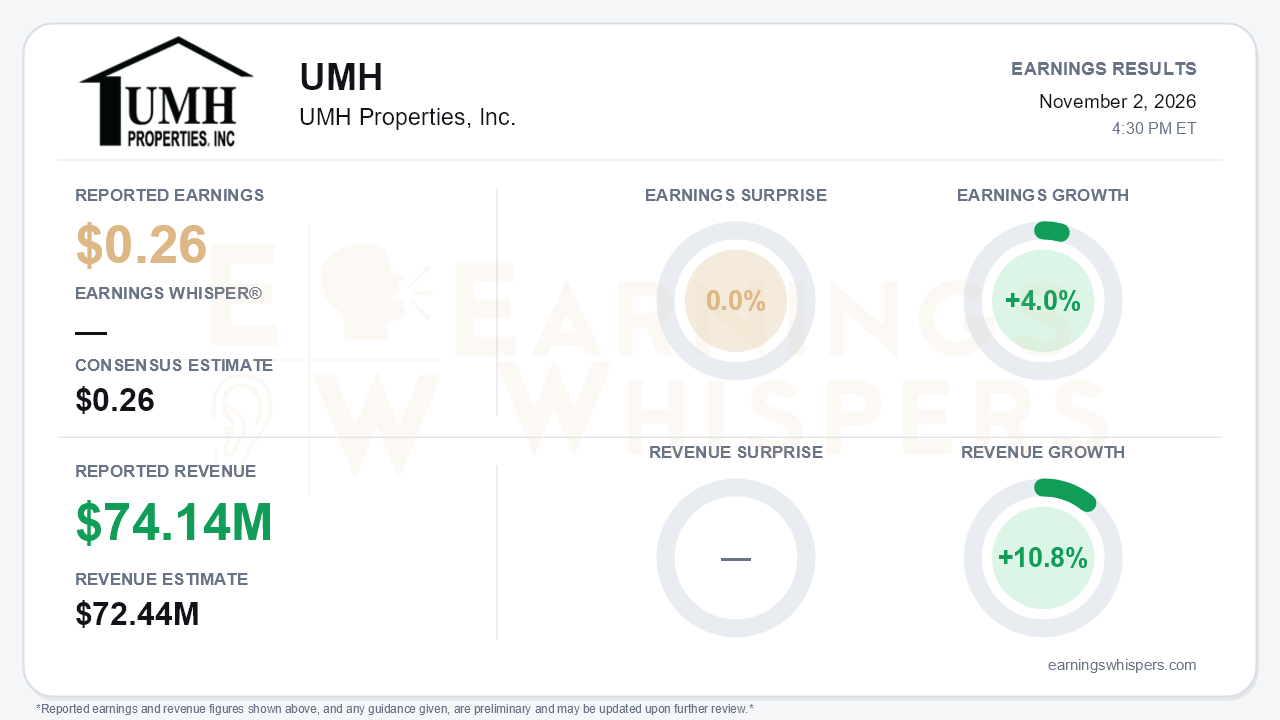
UMH Properties delivered a quarter whose operations improved faster than its earnings outlook. Normalized FFO of $0.26 per share matched the consensus estimate exactly and rose 4.0% year over year. Revenue of $74.14 million beat expectations by 2.3% and grew 10.8%. The operating detail was stronger than an in-line print usually implies: same-property NOI growth accelerated for a third straight quarter, and home sales set another record. Yet management only tightened full-year guidance around the same $1.01 midpoint it has held all year. That is the central tension. The business is gaining momentum, but more of that momentum is being absorbed by thinner sales margins, higher financing costs and a heavier balance sheet before it reaches per-share earnings.
The GAAP picture is noisier. UMH swung to a net loss attributable to common shareholders of $2.1 million, or $0.02 per share, from net income of $0.05 a year earlier. Two items drove most of that swing. Marketable securities lost $3.6 million in fair value during the quarter, against a $1.6 million gain a year ago. Depreciation also rose to $18.5 million from $16.8 million as the asset base grew. Neither item affects FFO, and normalized FFO excluded another $795,000 of one-time legal fees and employee transition pay. Nine-month normalized FFO of $0.74 compares with $0.71 last year, and this was the third consecutive quarter of sequential per-share growth, from $0.23 in Q1 to $0.25 in Q2 to $0.26 in Q3.
The call showed clear operating acceleration:
- **Same-property NOI:** Growth reached roughly 10%, up from 9% in Q2 and 7.1% in Q1.
- **Expenses:** Same-property operating expense growth eased to 5.4% from about 7% and 8% in the prior two quarters.
- **Expense ratio:** The same-property expense ratio improved to 38.9% from 39.8%.
- **Home sales:** Sales hit a record $12.8 million, up 29%, compared with $11.5 million (+10%) in Q2 and $7.1 million in Q1. October added about $3.5 million in closings, with $7 million pending.
- **Rental homes:** About 600 have been added year to date at roughly 95% occupancy, keeping the 800-unit target in reach.
The quality of that growth deserves scrutiny, though. Home-sale gross margin fell to 31% from about 37% a year ago. Management attributed the decline to manufacturer price increases and early expansion-phase sales carrying 20–25% margins. Site rent increases slowed to 4.4% from the 5% cited earlier in the year. The occupancy data also needs careful reading. The release highlighted same-property occupancy rising 30 basis points to 88.8%. On the call, however, overall occupancy was cited at 88.4%, versus 89% referenced in Q2, and quarterly unit gains slowed to 68 from 97 in Q2 and 184 in Q1. Both statements can be true because they measure different portfolios. Still, the pace of filling homes is decelerating even as UMH points to 3,100 vacant lots as its organic growth engine.
Management's tone was its most bullish yet. CEO Samuel Landy called the company "more optimistic than ever before." The call cast the Road to Housing Act as the most significant beneficial change for the industry since 1968, citing two-story HUD homes and Title I loans with 3% down payments. Management also highlighted:
- an October 22 executive order allowing rent payment history to count toward loan qualification;
- a Micron plant near Woodland Manor, with expansion construction expected in 2027;
- possible refinancing of about $110 million of resident loans through third-party lenders, which would convert those loans to cash.
These are credible catalysts, but they remain largely prospective, and UMH is already spending on its sales platform ahead of implementation.
Bears have legitimate ammunition on the balance sheet. Net debt to EBITDA climbed to 5.9x from 5.4x at year-end, and management expects leverage to rise further. Fixed-rate debt fell to 87.5% of the total from 99% in Q1. Loans payable reached $128 million, up from $27.7 million at December 31 and $66 million last quarter. About $74 million of refinancing is planned at low-6% rates, replacing debt in the high-4% range. Management said the stock price is unsuitable for common equity issuance and that preferred stock is less attractive at current prices. That narrows UMH's funding options just as its development opportunities expand.
Investor sentiment remained negative but improved modestly, rising to -0.24 from -0.33 ahead of the report. The stock has gone essentially nowhere: at $15.27, shares are down 1.2% from the open after the August report and sit about 1.3% below their 200-day moving average of $15.47. The Earnings Whispers trend readings are mixed. Sequential growth and momentum are positive, while price and AVWAP remain negative, consistent with improving operations that have not yet translated into share-price traction.
The bottom line is that UMH's operating engine is clearly strengthening, with accelerating NOI, record home sales and easing expense pressure. However, the full-year outlook has not moved, and the costs of that growth are rising. Q4 home sales are expected to fall below the Q3 record. The implied fourth-quarter guidance midpoint of $0.27 requires continued execution while sales margins compress and debt costs reset higher. Until the regulatory tailwinds show up in occupancy gains and per-share guidance rather than in management commentary, the stock's sideways trading looks like a reasonable reflection of a story that is improving but not yet accelerating where it counts.
Read our earnings preview for UMH Properties, Inc.: https://www.earningswhispers.com/article/UMH/21439
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-01 | |
| Oct-01 | |
| Sep-29 | |
| Sep-15 | |
| Sep-14 | |
| Aug-31 | |
| Aug-17 | |
| Aug-14 | |
| Aug-12 | |
| Aug-05 | |
| Aug-05 |
