Pinnacle West's Modest Q3 Beat Hides A Step-Change: TSMC Contract And Doubled Sales Outlook Reset The Growth Story, But Financing Costs Rise
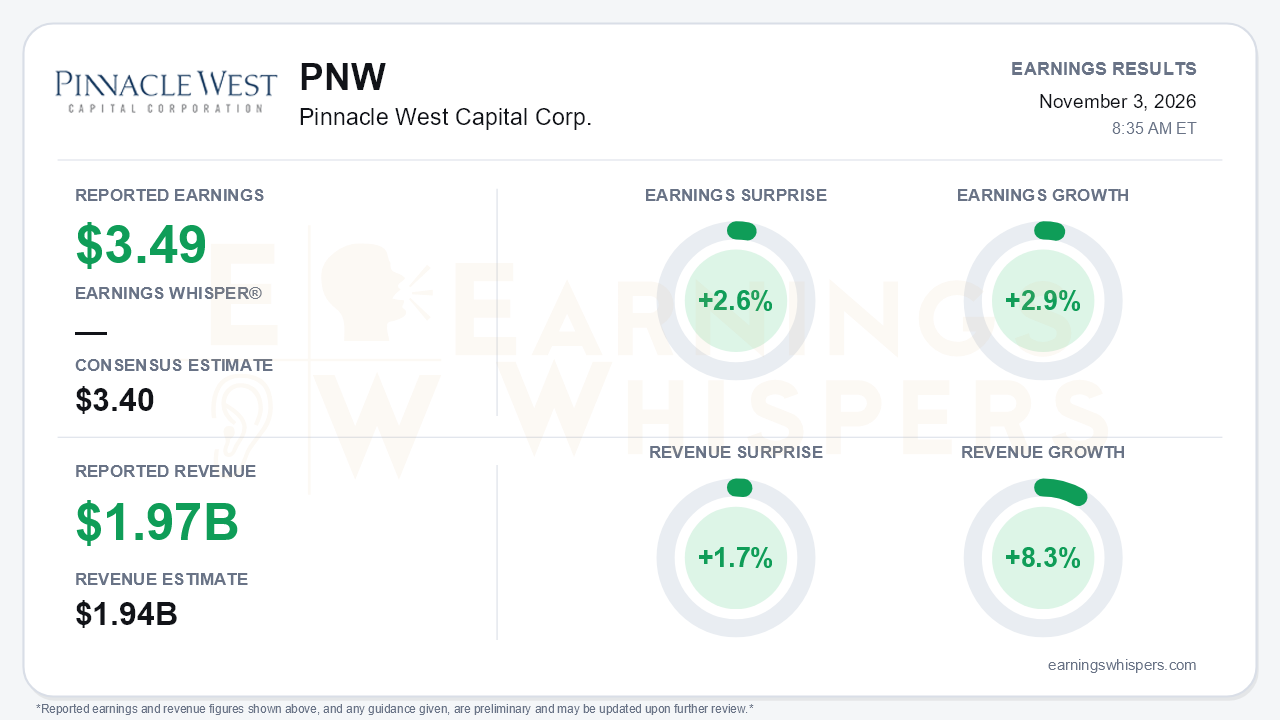
Pinnacle West Capital (NYSE: PNW) reported third-quarter earnings of $3.49 per share, beating the $3.40 consensus by 2.6% and growing 2.9% year over year. Revenue of $1.973 billion topped the $1.94 billion consensus by 1.7% and rose 8.3%. Taken alone, the headline is a routine utility beat. The guidance and the conference call were not routine. Management raised 2026 EPS guidance by a full $0.50, to $5.05-$5.25 from $4.55-$4.75, and lifted its long-term sales growth outlook. It also executed its first large-load direct pricing contract, with TSMC. The quarter's small earnings beat understates how much the investment setup changed.
The quality of the beat deserves some scrutiny. Net income attributable to common shareholders rose about $21 million to $434.2 million. The company credited higher customer sales and usage, favorable weather and customer growth. Cooling degree days were up 3% in a substantially warmer-than-normal quarter. Part of the revenue gain was pass-through rather than margin: fuel and purchased power rose about $102 million, more than half of the roughly $152 million increase in revenue. Below the operating line, depreciation and amortization climbed to $242.5 million from $224.6 million. Interest charges rose to $138.8 million from $125.2 million, and other income fell to $4.6 million from $12.5 million. Diluted shares increased to 124.3 million from 122.0 million, so equity issuance diluted the per-share gain. That helps explain why EPS growth lagged net income growth. Operations and maintenance expense edged lower, a sign of cost discipline.
The underlying demand story is the real development. Weather-normalized sales grew 9.5%, driven by 14.5% growth in commercial and industrial sales and 4.5% growth in residential sales. That follows growth of 9.6% in the second quarter and 9.4% in the first, compared with about 5% for all of 2025. Management finally put that run-rate into guidance:
- 2026 weather-normalized sales growth was raised to 8-10% from the 4-6% range held through the second quarter.
- Sales growth through 2030 was lifted to 8-10% from 5-7%.
- Committed large-load demand rose to 5.8 GW from 4.5 GW, not counting roughly 20 GW of uncommitted queue.
Customers set an all-time peak of 9,166 MW on August 2, against last year's 8,648 MW peak, and surpassed the old record a dozen times. Management's tone shifted from describing results as solid earlier in the year to openly expansionary.
The TSMC agreement is the headline catalyst. It is a 25-year contract for roughly 1.88 GW at full build-out, with upfront capital contributions and credit support. It will be filed with the Arizona Corporation Commission, and the framework is meant to be replicated with other queue customers. That structure matters because it eases external financing needs and could narrow the roughly 200-basis-point gap between EPS growth and rate-base growth. It also gives substance to the company's "growth should pay for growth" pledge. Separately, the newly filed Integrated Resource Plan calls for about 15 GW of new resources and 2.6 GW of incremental transmission by 2041. Roughly 40% of that is expected to be APS-owned, with the rest subject to competitive procurement.
Bears still have legitimate ammunition:
- **Financing costs:** Management described a significantly rising interest-rate environment, and interest and D&A continue to climb.
- **Dilution:** The company has issued about $920 million through its at-the-market program year to date, and more equity may be needed as capital spending expands.
- **Regulatory lag:** The current historical test year dates to mid-2021. A rate case decision with a formula rate is expected in December, but the run-rate benefit does not arrive until 2029.
- **Normalization:** Management expects some 2026 residential strength, which was partly weather-driven behavior, to normalize. October weather was milder.
- **Fourth-quarter math:** The raised guidance midpoint of $5.15 sits slightly below the $5.20 already earned through nine months, implying a seasonally soft fourth quarter.
- **Deferred specifics:** Updated capital spending, financing and long-term EPS targets will not come until February.
Investors appeared to be leaning into the story before the report. Earnings Whispers sentiment moved from slightly negative (-0.04) to slightly positive (+0.05), a modest improvement rather than a surge in enthusiasm. Shares closed at $105.95 the day before the release, up 6.5% from the $99.50 open after the August report. That price was 5.5% above the 200-day moving average and just 1.7% below the inter-earnings high of $107.75 set October 30. The stock had rallied 17.4% from its September 25 low of $90.27. The Earnings Whispers price, momentum and AVWAP trend signals are positive. The stock therefore entered the report near the top of its range, leaving less room for a reflexive relief move.
The bottom line is that Pinnacle West's quarter was a modest beat paired with a major forward revision. The TSMC contract, a near-doubling of the long-term sales growth outlook and the guidance raise turn Arizona's load growth from a promise into contracted, financeable demand. The open question is conversion. Rising rates, ongoing dilution, regulatory lag and a pending rate case will determine how much of that sales growth reaches per-share earnings. February's long-term outlook should be the next real test.
Read our earnings preview for Pinnacle West Capital Corp.: https://www.earningswhispers.com/article/PNW/21506
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| 9 hours | |
| 15 hours | |
| 15 hours | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-26 | |
| Oct-21 | |
| Oct-02 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 |
