Pershing Square Misses On Revenue By 25%, But The Call Leans On AUM Growth And Howard Hughes Execution
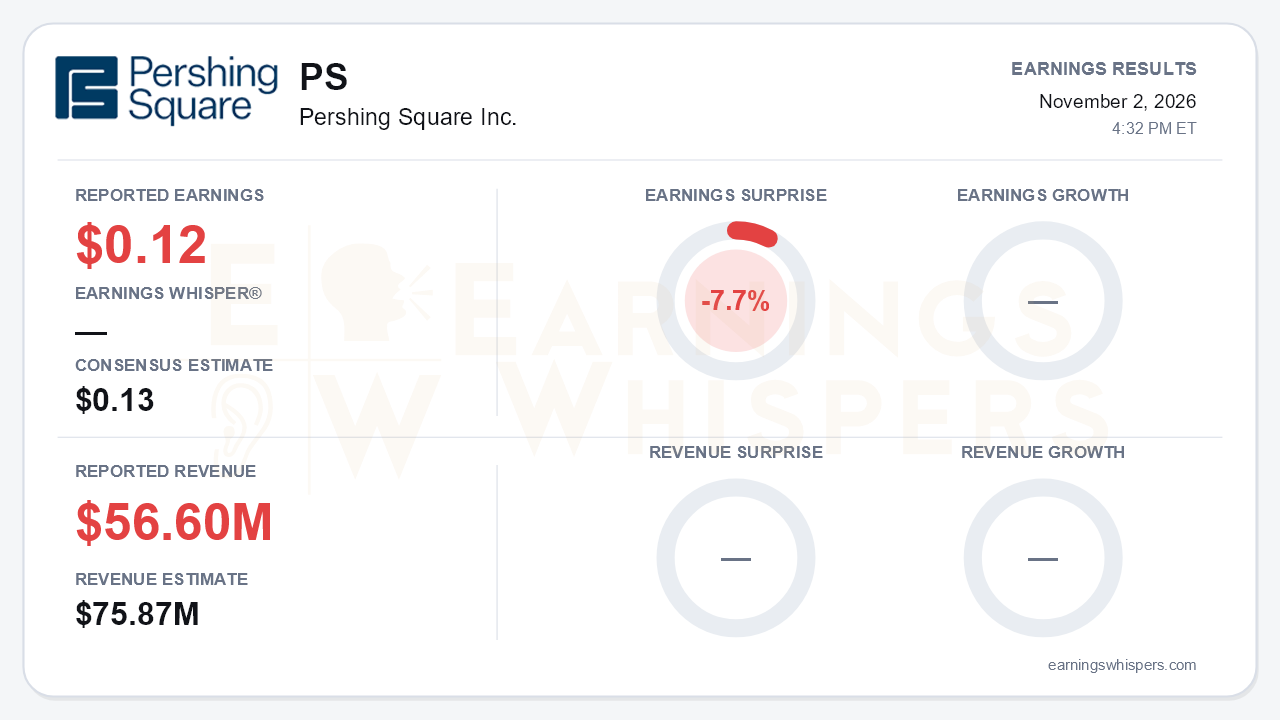
Pershing Square Inc. (NYSE: PS) delivered a soft third quarter. It earned $0.12 per share against a $0.13 consensus, a 7.7% miss. The bigger problem was revenue of $56.6 million, which fell 25.4% short of the $75.87 million analysts expected. A revenue shortfall that size at a fee-driven asset manager is not a rounding error. The company offered almost nothing to explain it. That is the central tension of the report: the numbers disappointed, yet management's message on the call was more confident than three months ago, built on asset growth and strategic moves that have not yet reached the income statement.
The quality of the disclosure deserves scrutiny. The press release contained no financial detail at all. It pointed investors to an external presentation and shareholder letter, and its only quantitative item was the $0.103 per-share dividend paid October 20. That payout absorbs most of the quarter's $0.12 in earnings. Year-over-year growth comparisons were not available, so it is not possible to say whether earnings or revenue accelerated or decelerated. The call was a less formal Q&A with fewer financial disclosures and no formal guidance. For a quarter with a 25% revenue miss, the scarce explanation is a legitimate concern in its own right.
The operating story was steadier. Fee-paying assets under management reached $24 billion, up from roughly $23 billion cited on the second-quarter call. Management said about $1 billion of that gain came from investment performance alone after the end of September. That timing matters: the gain arrived after the quarter closed, so it supports the fee base going forward rather than the results just reported.
The more substantive change was at Howard Hughes, where the asset-light real estate concept moved from idea to execution:
- A financial advisor has been hired.
- Transactions are underway to sell 80% to 90% equity stakes in real estate assets to pension funds and family offices.
- Howard Hughes would keep fee and incentive-fee streams on those assets.
- Freed-up capital would be redirected into the Vantage insurance platform, where management targets returns on equity above 20%.
Management argued each recycled dollar is worth roughly twice its face value. On that basis it rejected a buyback, even with Howard Hughes stock just under $80 against an estimated net asset value in the low $100s. The stock was in the mid-$60s at the time of the prior call.
The list of catalysts is long but mostly forward-dated:
- Management cited a Treasury framing that puts resolution of Fannie Mae and Freddie Mac ownership in 2027-2028. It pegged total value near $500 billion and said Pershing Square owns roughly 10% of each.
- PSUS is weighing a dividend to narrow its persistent discount to NAV, a concrete step after management called that discount "absurd" last quarter.
- Commentary on holdings was more upbeat. Management cited Amazon's 40%-plus cloud growth outlook, Azure possibly topping 50% next quarter, Alcon bought at about 17 times earnings with mid-teens EPS growth expected, and Brookfield's 24% to 25% EPS growth targets.
Bears have ammunition as well:
- Several initiatives promised last quarter went silent. There was no timing update on the Pershing Square Ventures launch, which had been targeted for fall or year-end.
- There was no progress report on the investment-grade leverage plan for PSUS.
- SPARC still has no deal.
- The PSUS dividend remains only under study.
- Midterm elections, possible Supreme Court involvement in shareholder litigation, and political shifts add uncertainty to the Fannie/Freddie timeline.
- Portfolio holdings sold off despite strong hyperscaler earnings, amid concerns about robotaxi competition for Uber and about Netflix's content and pricing power.
Investor sentiment moved decisively the other way. It slid from a modestly positive 0.17 at the prior report to -0.10 now, a meaningful swing into negative territory. That cooling sits against a stock that has run hard. Shares are up 25.5% since the open following the August report, and at $46.62 they sit about 39% above the 200-day moving average of $33.51. Investors entered this print with substantial gains to protect. Sequential growth readings remain positive, while the AVWAP trend is negative, a reminder that recent buyers are not uniformly in the money.
The bottom line is that Pershing Square missed on both lines, with a revenue gap large enough to demand an explanation the company did not provide. The call preserved a credible growth narrative: rising AUM, an actionable Howard Hughes capital-recycling plan, and potential upside from Fannie and Freddie. Much of that value, however, is either post-quarter or years away, and several earlier commitments went unaddressed. With the stock extended well above its long-term average and sentiment turning negative, the setup is more complicated than the strategic optimism suggests. The next report needs to show that the asset growth is turning into fee revenue.
Read our earnings preview for Pershing Square Inc.: https://www.earningswhispers.com/article/PS/21425
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Oct-29 | |
| Oct-26 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Oct-13 | |
| Oct-13 | |
| Oct-12 |
