Expro Misses And Trims Q4 EBITDA Again, Leaving A Higher Cash-Flow Target As The Main Offset
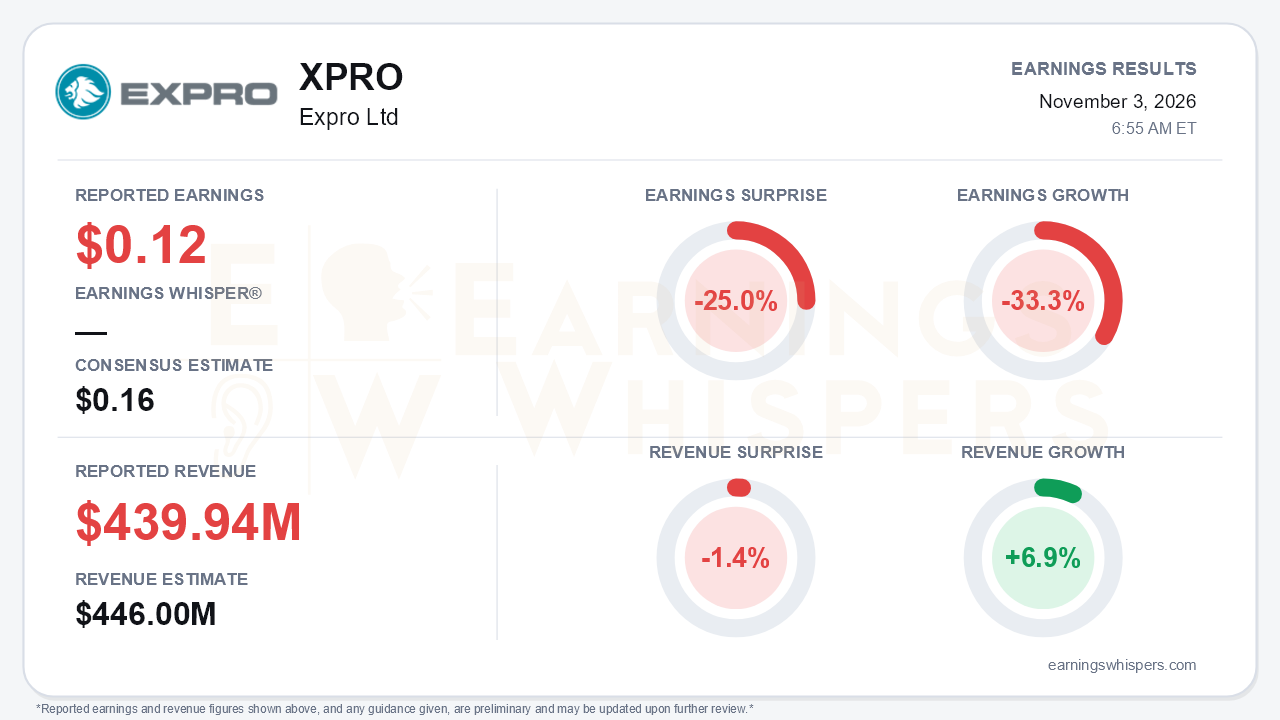
Expro delivered the sequential rebound it promised but missed expectations, and it lowered its fourth-quarter outlook for the second straight time. Earnings Whispers normalized EPS came in at $0.12, below the $0.16 consensus, a 25.0% miss. Revenue of $439.94 million fell 1.4% short of the $446.0 million estimate. Earnings fell 33.3% from a year ago even as revenue grew 6.9%, and that gap is the story of the quarter. Expro is adding revenue, much of it through the Enhanced Drilling acquisition, but it is not yet converting that revenue into higher profits. Management also cut its fourth-quarter adjusted EBITDA expectation by about $20 million. That undermines the second-half margin ramp the bull case has relied on.
The per-share figures need some untangling. On a GAAP basis, Expro lost $5.2 million, or $0.05 per share. A year earlier it earned $0.12 per share on a GAAP basis. Merger and integration costs rose to $10.0 million and severance to $8.8 million, together adding $0.17 per share. The company's own adjusted EPS of $0.19 also adds back $0.07 of stock-based compensation, which accounts for most of the difference from the $0.12 normalized figure. Whichever measure investors use, the year-over-year trend is weaker:
- **Adjusted EBITDA** was $91.2 million, down from $94.0 million in the year-ago quarter, despite higher revenue.
- **Adjusted EBITDA margin** slipped to 20.7% from about 23%.
- **Gross margin** fell to 10% from 13%.
Sequentially, the picture looks much better. Revenue rose 12% from $393 million in the second quarter, and adjusted EBITDA climbed 20% from $76 million.
The segment results show where the improvement is coming from and where it is missing:
- **North and Latin America** drove the gain. Revenue rose 20% sequentially and segment EBITDA margin widened to 23% from 20%, helped by Enhanced Drilling and well construction work in the U.S., Brazil and Suriname.
- **Europe and Sub-Saharan Africa** grew revenue 17%, but its margin slipped to 26% because less high-margin project work was performed. That margin was 32% a year ago.
- **The newly combined Asia, Middle East and North Africa region** was flat at a 30% margin. Revenue dipped because of weaker well flow management in Saudi Arabia.
The business mix also shifted. Well construction rose to 42% of revenue from 35% in the second quarter, while well management revenue edged lower. In practice, the acquisition is masking a broadly static base business.
The conference call sharpened the credibility question. The fourth-quarter cut was blamed on two things:
- loop currents and hurricane disruption that delayed high-margin U.S. Gulf subsea work;
- a schedule change that pushed well intervention work in Colombia into 2027.
Those are the same North and Latin America drivers management had cited on earlier calls as fourth-quarter ramp contributors. On the second-quarter call, management targeted a second-half margin above 24% and a fourth-quarter margin above 26%. Those targets have now been moderated. That followed the earlier EBITDA cut tied to the Middle East, where expected 2026 growth never materialized. Full-year adjusted EBITDA guidance now stands at $330-$340 million, down from $355-$365 million. Management insists the deferred work stays in backlog with its value intact and still expects a record fourth quarter. Even so, a third quarter that landed in the lower half of guidance and a second straight reduction give bears legitimate ammunition.
Cash flow and the 2027 outlook are the offsets:
- **2026 cash flow:** Full-year adjusted free cash flow guidance rose to $140-$150 million, helped by better collections and working-capital discipline. However, third-quarter adjusted free cash flow of $52 million was actually slightly below the second quarter's $56 million.
- **2027 framework:** Management's first look calls for mid-teens adjusted EBITDA growth and more than 20% adjusted free cash flow growth.
- **Enhanced Drilling:** The acquisition began its first managed-pressure drilling operations in West Africa.
- **Buybacks:** Year-to-date repurchases total roughly $52 million, and the board authorized a new $100 million program.
The 2027 outlook carries caveats. Management acknowledged less visibility into 2027 customer programs than it would typically have in November. A Barclays analyst noted on the call that the outlook is largely explained by the deferred work plus a full year of Enhanced Drilling, which implies little organic growth. The balance sheet has also changed. Revolver borrowings rose to $259 million, liquidity fell to $260 million from $492 million, and Expro moved to $87 million of net debt from $121 million of net cash at the end of the second quarter.
Investors were already skeptical going into the report. Earnings Whispers sentiment remained negative and weakened modestly, to -0.31 from -0.23. The shares closed at $15.87 the day before the report:
- essentially unchanged, up 1.1%, from the opening price after the July report;
- 3.8% below the 200-day moving average of $16.50;
- 17.5% below the August 20 high of $19.23, which was also a 52-week high.
In short, the market had already given back an enthusiastic summer rally before this report added another reason for caution.
The bottom line is that Expro produced a real sequential improvement, but missed on both EPS and revenue, and the fourth-quarter EBITDA cut weakens the margin-ramp narrative a second time. Rising cash-flow guidance, buybacks and an upbeat 2027 framework keep a credible story alive. That story now leans heavily on deferred work and acquired growth, so investors will want to see the base business expand before giving management's forecasts full credit.
Read our earnings preview for Expro Ltd: https://www.earningswhispers.com/article/XPRO/21533
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-22 | |
| Jul-28 | |
| Jul-28 | |
| Jul-28 | |
| Jul-23 | |
| Jul-14 | |
| Jun-04 | |
| Jun-04 | |
| May-05 | |
| May-05 | |
| Apr-14 | |
| Apr-01 |
