Vitesse Energy Matches EPS Consensus As DJ Deal Lifts Guidance, But Leverage, Free Cash Flow And Hedges Complicate The Quarter
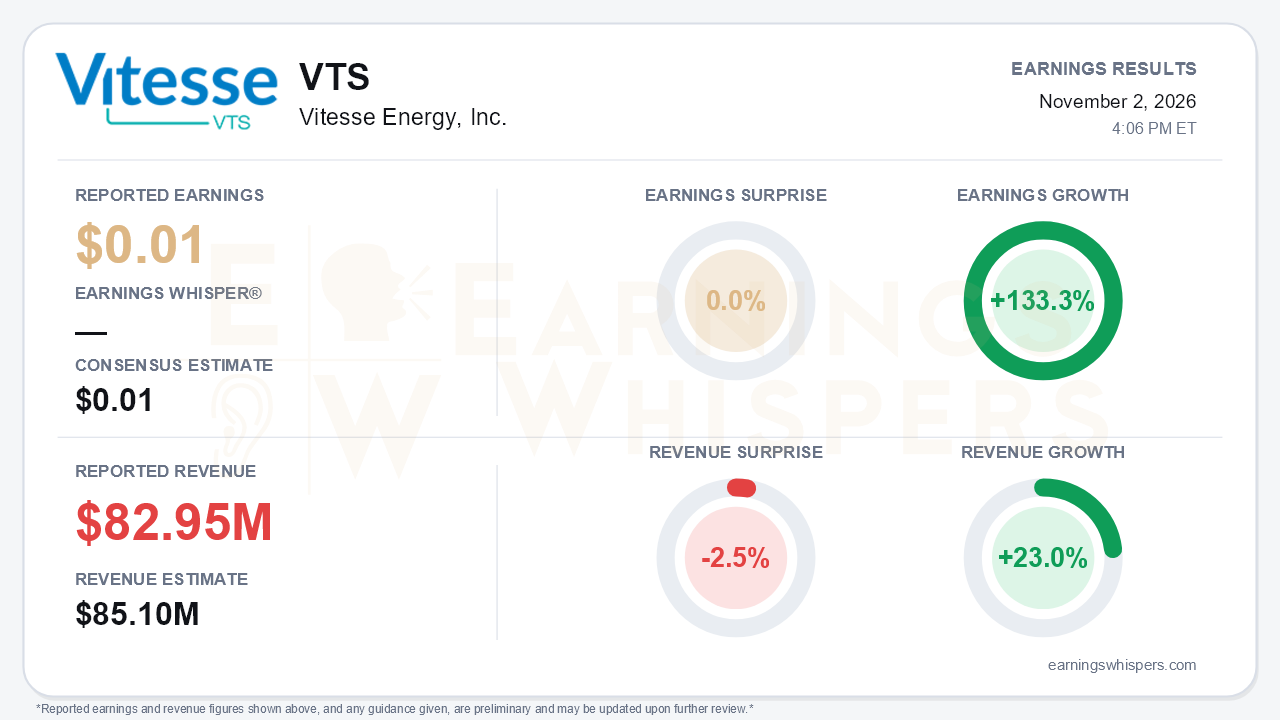
Vitesse Energy delivered a quarter where the headline numbers hide a business in transition. The non-operated oil producer reported earnings of $0.01 per share, exactly in line with the $0.01 consensus, while earnings grew 133.3% from a year ago. Revenue of $82.95 million rose 23.0% year over year but missed the $85.1 million consensus by 2.5%. The more important story is the trade Vitesse just made. It closed a revolver-funded DJ Basin acquisition and raised its activity outlook, and in exchange it accepted higher leverage, thinner free cash flow and a stretched balance sheet. That is the central tension of the report.
The quality of the quarter deserves scrutiny. On a GAAP basis, Vitesse lost $36.4 million, or $0.86 per share. Most of that came from a $46.6 million non-cash unrealized loss on commodity derivatives. Adjusted net income was a modest $2.5 million. The hedge book did more than create accounting noise. Vitesse also posted a realized hedging loss of nearly $12 million. Its unhedged oil price was $82.56 per barrel, but the hedged realization was only $68.33. The 23% revenue growth was entirely price-driven. Oil prices before hedging rose 38% from a year ago, while daily production fell 7% to 16,824 Boe per day and oil volumes dropped 14%. Unit costs also moved the wrong way. Lease operating expense rose 12% to $12.42 per Boe, and production taxes per Boe climbed 30%.
The sequential picture shows similar pressure. Production slipped from 17,354 Boe per day in the second quarter. Management attributed part of the decline to back-to-back mechanical failures on operated assets that required 24-hour workover crews, which also inflated lease operating expense. Adjusted EBITDA eased to $39.3 million from $40.2 million. Free cash flow fell to $9.4 million from $16.3 million in the second quarter and $12.0 million in the first. Meanwhile, the company again declared a $0.4375 quarterly dividend, with the call noting the payout has been maintained for 16 straight quarters. On roughly 42.8 million shares outstanding, the dividend costs about $18.7 million per quarter, well above this quarter's free cash flow.
What changed is the forward activity profile, and here the call preserved a credible growth story. Operators turned 2.0 net wells to production versus 1.7 in the second quarter, and spuds rose to 2.0 net from 1.8. Management expects wells turned to production to accelerate in the fourth quarter, when the DJ assets make their first full-quarter contribution. The Williston rig count has climbed to 38 from about 28 cited on the first-quarter call, and Vitesse holds interests in roughly half of those rigs. The 2026 production guide was narrowed to 16,600-17,200 Boe per day, lifting the midpoint. A preliminary 2027 outlook calls for flat to modestly higher production on similar capital. Management also expects maintenance capital to fall about 10% over three to four years as operators drill longer laterals. A decision on developing 60 operated Williston wells from the Lucero position is expected in the first quarter of 2027.
Bears have legitimate ammunition on the balance sheet. Net debt to trailing adjusted EBITDA rose to 1.3x, above management's own target of 1.0x or below. That compares with under 1x in the second quarter, 0.82x in the first and 0.69x at year-end 2025. Drilling and completion capex guidance rose to $80-90 million from $65-80 million, which increases spending and exposure to cost inflation, including diesel. Liquidity was $85.2 million at September 30. The call cited roughly $100 million, a figure that appears to include the October increase in the borrowing base from $275 million to $290 million. On either measure, liquidity is down from about $117 million in the second quarter and $130 million in the first. Hedging cuts both ways. The oil book now extends into 2030 at about $68 per barrel, adding cash-flow visibility, but it caps upside at current realized prices, and coverage of remaining 2026 oil fell to about 64% from roughly 70%.
Investor sentiment remained negative but improved meaningfully, rising from -0.32 to -0.21. The stock has risen 13.4% since opening at $15.20 after the August report, reaching $17.24. Even so, it still sits about 4.1% below its 200-day moving average of $17.98. The Earnings Whispers trend readings are mostly neutral, with AVWAP the notable positive. Overall, the market has rewarded the activity narrative without fully re-rating the stock.
The bottom line is that Vitesse delivered an in-line quarter with a revenue shortfall and a messy GAAP loss. Management is clearly leaning into growth, through the DJ acquisition, higher capex, rising rig activity and a constructive early 2027 view. That pivot has pushed leverage above target and squeezed free cash flow below the dividend run-rate. The fourth quarter, with the first full contribution from the DJ assets and the promised acceleration in wells turned to production, now has to show that the added debt is buying durable cash flow.
Read our earnings preview for Vitesse Energy, Inc.: https://www.earningswhispers.com/article/VTS/21447
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Oct-28 | |
| Oct-26 | |
| Oct-15 | |
| Sep-19 | |
| Sep-17 | |
| Sep-16 | |
| Aug-12 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-31 |
