CVR Energy Posts A Record Refining Quarter And Bets The Windfall On A Levered Marathon Deal
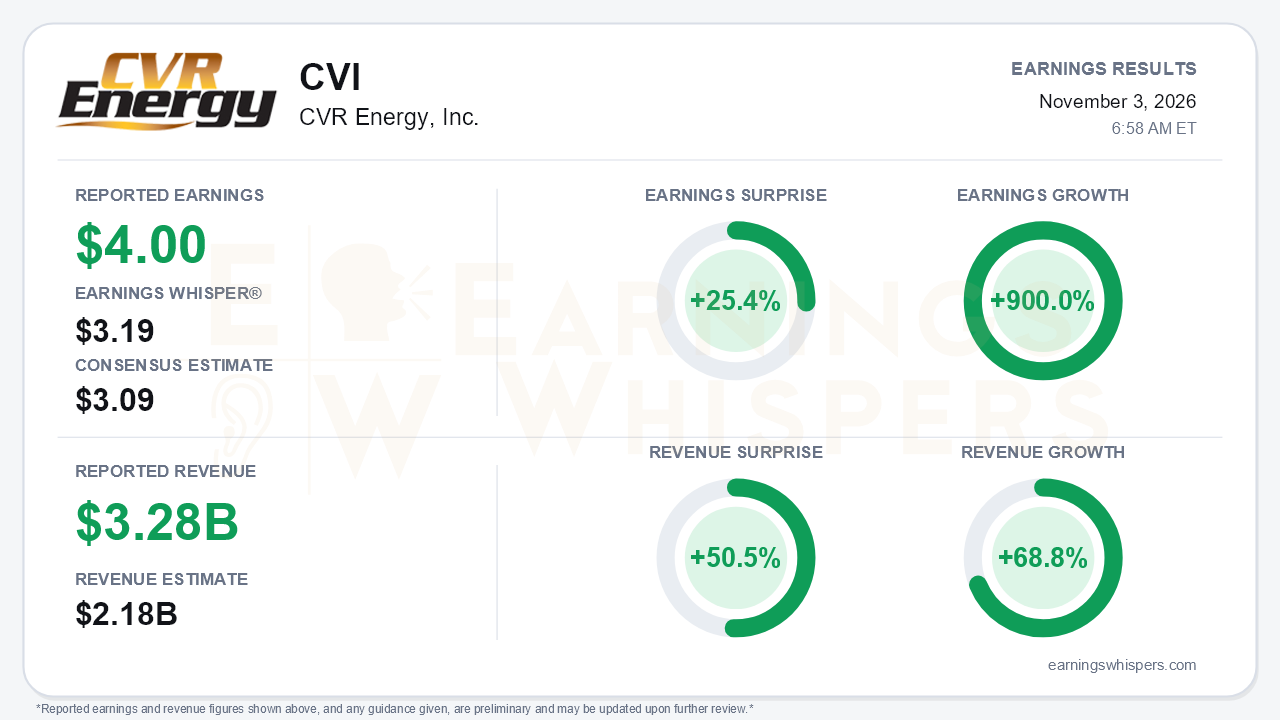
CVR Energy delivered the best quarter in its history, and the beat was large. Adjusted earnings of $4.00 per share topped the $3.09 consensus by 25.4% and cleared the $3.19 Earnings Whisper number. Revenue of $3.281 billion beat the $2.18 billion consensus by 50.5%. Year over year, earnings grew 900.0% and revenue rose 68.8%, as near-record crack spreads replaced a quarter in which adjusted EPS was just 40 cents. The more consequential news, however, arrived alongside the numbers. CVR agreed to buy Marathon Petroleum's St. Paul Park and Mandan refineries for roughly $4.2 billion. That deal turns a cash-rich refiner that had been focused on deleveraging into a levered consolidator. That is the central tension: the quarter showed what CVR earns in a peak environment, and management is using that moment to nearly double its exposure to refining.
The quality of the beat holds up better than the GAAP figure suggests. Reported EPS was $5.67, but that included a $2.36 per-share benefit from changes in the RFS obligation. Most of that came from the EPA's August decision granting Wynnewood a full 2025 small refinery exemption, which removed a $253 million liability. Adjusted results strip out that benefit and a $0.26 inventory gain, and they add back $0.95 of unrealized derivative losses. The $4.00 figure is therefore a reasonable read on operations. The operating gains were broad:
- Petroleum adjusted EBITDA reached $565 million, versus $120 million a year earlier.
- Adjusted refining margin rose to $34.97 per barrel from $12.87.
- Crude utilization hit 104.9%.
- Free cash flow was $593 million.
- Cash climbed to $1.3 billion from $511 million at year-end.
The sequential trajectory is even more striking. Consolidated adjusted EBITDA went from $37 million in the first quarter to $209 million in the second and $582 million in the third. Refining was the driver. The Group 3 2-1-1 crack rose from $21.58 to $44.91 to $68.50. Capture improved from 22% to 28% to 51% as hedge exposure stepped down and backwardation eased. Throughput rose to about 228,000 barrels per day from roughly 213,000. Fourth-quarter throughput guidance of 210,000 to 225,000 bpd sits above the prior quarter's guide. Management also extended its view that margins will stay above mid-cycle levels for the next 12 to 24 months, through 2027.
Bears still have legitimate ammunition beneath the headline:
- **Fertilizer weakened sharply.** The planned East Dubuque turnaround cut ammonia utilization to 80%. Nitrogen Fertilizer EBITDA fell to $20 million from $107 million in the second quarter, and the segment posted an $11 million net loss. CVR Partners' distribution dropped to $1.79 from $6.08.
- **RIN costs remain heavy.** Net RIN expense was $11.20 per barrel, which management sized as roughly a 16% hit to capture.
- **Hedging was costly.** Total derivative losses reached $259 million.
- **Costs crept up.** Petroleum operating expense rose to $6.15 per barrel from $5.93.
- **The margin backdrop may not last.** It rests partly on geopolitical disruptions involving Hormuz and Russia/Ukraine that could normalize.
The Marathon deal reshapes the investment case. Management pitched the acquisition at under 3.5 times 2026 estimated EBITDA. It lifts crude capacity from about 207,000 to about 384,000 bpd and adds roughly 590 branded marketing locations. Management targets about $70 million in run-rate synergies and expects more than 50% accretion to EPS and free cash flow in the first full year. Greater blending capacity should also reduce open RIN exposure. The price is the balance sheet. Through the second quarter, management reiterated a $1 billion gross debt target. Pro forma debt excluding CVR Partners will now be about $3.8 billion, which management puts at under 2 times pro forma 2026 EBITDA. Financing also includes a $2.5 billion bridge loan to be refinanced, plus equity from IEP ($500 million) and a large third-party investor. Shareholders now carry dilution, HSR clearance and integration risk ahead of a targeted year-end close.
The market had largely priced in the refining upswing before the report. Shares opened at $36.00 after the July report and closed at $55.92 on November 2, a 55.3% gain. The stock sits about 56% above its 200-day moving average of $35.80. It is nonetheless 12% below the 52-week high of $63.51 set on October 14, so the rally had already cooled into earnings. Investor sentiment, meanwhile, slipped from roughly neutral (-0.03) to modestly negative (-0.11). That suggests some unease despite the stronger price trend, plausibly tied to how much of the cycle is already in the stock. The Earnings Whispers trend signals are mostly positive, with sequential growth neutral.
The bottom line is that CVR's quarter was genuinely strong and the beat was operational rather than accounting-driven. The company now has the cash generation it lacked earlier in the year. But the story has shifted from harvesting a hot crack environment to levering up to buy more of it. If margins stay elevated through 2027, as management expects, the Marathon assets could transform per-share earnings. If they normalize, investors will be holding a far larger and more indebted refiner bought near a cyclical peak.
Read our earnings preview for CVR Energy, Inc.: https://www.earningswhispers.com/article/CVI/21471
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-02 |
Carl Icahn's CVR Energy Near Over $4 Billion Deal for Marathon Refineries
CVI
The Wall Street Journal
|
| Oct-27 | |
| Oct-26 |
