Xenia's RevPAR Growth Accelerates To 12.5% And Guidance Rises Again, But Soft Late-2027 Group Pace Is The Open Question
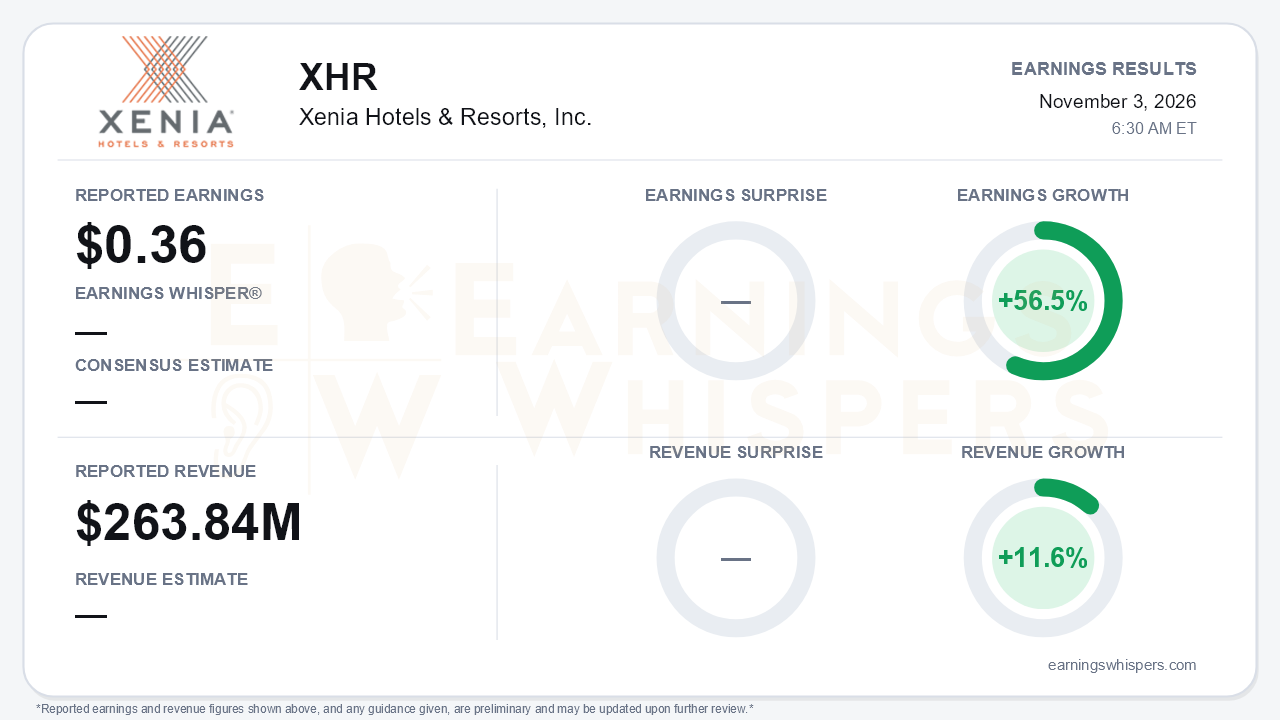
Xenia Hotels & Resorts delivered its strongest quarter of the year. Adjusted FFO came in at $0.36 per share for the third quarter, up 56.5% from a year ago, and revenue rose 11.6% to $263.84 million. No consensus estimate was available for comparison, but management said results "significantly surpassed our expectations." It backed that statement by raising full-year guidance for the third consecutive quarter. On a GAAP basis, Xenia still posted a net loss of $0.03 per share, although that was a sharp improvement from the $0.14 loss a year earlier. The central takeaway is acceleration. Same-property RevPAR rose 12.5%, up from 7.4% in the first quarter and 5.6% in the second. The open question is how much of that strength carries into 2027.
The composition of the quarter matters as much as the headline. Second-quarter growth had come almost entirely from rate. In the third quarter, growth was balanced: occupancy rose 380 basis points to 70.0%, and ADR climbed 6.4% to $264. Total RevPAR rose 12.7%, reversing the second-quarter pattern in which it lagged room revenue. Same-property food and beverage revenue jumped 15%. That operating leverage reached the bottom line. Same-property hotel EBITDA rose 29.3% to $60.2 million, and margin expanded 295 basis points to 22.9%, compared with a 65-basis-point contraction in the second quarter.
The quality of the beat still deserves some scrutiny. Last year's third quarter was soft, with a 19.9% margin, which made for an easy comparison. Management also credited an "incremental increase in leisure demand from several large events." The company quantified the cost of lapping those events at roughly $3 million of EBITDA in 2027. Expense pressure has not gone away either. Utilities rose about 14%, administrative and general costs increased 10.2%, and G&A guidance moved up $1 million on incentive compensation. Adjusted results also exclude about $1.8 million of non-recurring costs, largely tied to operator transitions and the renaming of four hotels.
The call nonetheless preserved a credible growth story built on demand rather than one-offs:
- **Corporate transient** was the biggest upside surprise. Tuesday/Wednesday RevPAR rose 14.9%, and midweek occupancy reached 76.3%. Management noted that occupancy remains roughly seven points below 2019, which leaves room for further recovery.
- **Group demand** was the strongest of the year. Group room revenue rose 16.2% on an 11% increase in room nights.
- **Recent trends** held up. September RevPAR was up 16.8%, and October was up roughly 8%.
The guidance progression captures the momentum. The full-year RevPAR midpoint has climbed from 3% initially to 8% now. Adjusted EBITDAre guidance has moved from $260 million to $281 million, and AFFO per share guidance rose to $2.08 to $2.14 from $1.96 to $2.08. Management's margin outlook flipped from an expected slight decline at the start of the year to roughly 120 basis points of expansion, helped by cost per occupied room running near 2.5% versus 3% planned.
Bears have legitimate ammunition, and it is concentrated in 2027:
- **Group pace** for 2027 is down about 4%, entirely in the second half. That half is only about one-third booked, so the figure could still change.
- **First-half group pace** is roughly flat, or slightly positive excluding about $2 million of canceled FIFA blocks.
- **Normalization:** Management expects group growth to settle after gains of 13% in 2025 and 9% so far this year.
- **Rate limits:** Xenia has limited ability to push rates on large negotiated corporate accounts.
- **Renovations** at Andaz Napa and The Ritz-Carlton, Denver begin in early December.
- **Fourth-quarter guidance** implies RevPAR growth slows to around 7%.
There are offsetting catalysts:
- **Grand Hyatt Scottsdale:** Management guided EBITDA from the low-$30 million range this year to the high $30 millions in 2027, with a low-$40 million stabilized target.
- **Balance sheet:** Leverage fell to 4.4x from 5.2x at year-end 2025, and liquidity is $661 million. Paying off the San Francisco Airport mortgage in the second quarter of 2027 would leave 28 of 29 hotels unencumbered.
The market setup is more complicated than the results imply. Shares closed at $20.99 before the report, essentially flat (+0.7%) since opening at $20.85 after the July release. The path between those points was not flat. The stock set its inter-earnings high of $21.32 the day after the prior report, slid to a low of $17.13 in mid-September, then rallied 22.5% back into this print. It now sits just 1.5% below that high and about 19% above its 200-day moving average. Investor sentiment remains negative but improved modestly, moving from -0.15 to -0.12, which suggests skepticism has eased without disappearing. Earnings Whispers momentum and AVWAP trend readings are positive, consistent with the recent recovery in price.
The bottom line is that Xenia produced a clean operating acceleration, a third straight guidance raise, and a materially stronger balance sheet, and 2026 now looks well de-risked. The debate has shifted to 2027. There, softer second-half group pace, normalizing group growth, special-event comparisons, and renovation activity will test whether strengthening corporate transient demand can carry growth. With the stock already back near its post-July high, investors are no longer paying a trough price for that test.
Read our earnings preview for Xenia Hotels & Resorts, Inc.: https://www.earningswhispers.com/article/XHR/21530
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Sep-21 | |
| Sep-10 | |
| Sep-01 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jun-18 | |
| May-15 | |
| May-02 | |
| May-01 | |
| May-01 |
