Ardelyx Hits Breakeven And Holds Its Reset Guidance, But Decelerating Growth Keeps The Stock Pinned Near Lows
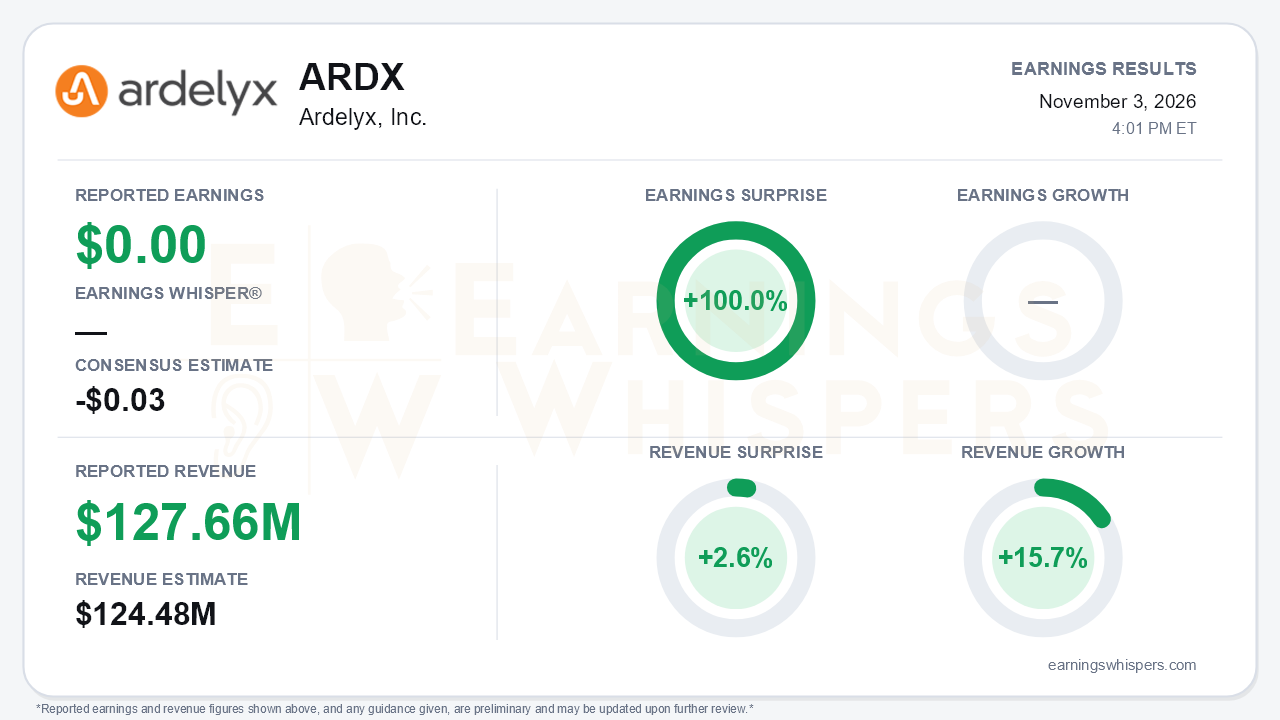
Ardelyx (NASDAQ: ARDX) delivered a cleaner quarter than its share price suggests. The company reported breakeven earnings of $0.00 per share against a consensus estimate of a $0.03 loss, a 100.0% surprise. Revenue of $127.66 million topped the $124.48 million consensus by 2.6% and grew 15.7% from a year ago. More important than the beat, management reiterated every piece of full-year guidance that it had reset three months ago. That matters for a company whose last report cut its IBSRELA outlook. The central tension is that the numbers now look stable, but growth is still clearly decelerating.
The quality of the quarter is mixed. Total product revenue rose 19% to $125.5 million. Reported total revenue grew more slowly because non-cash royalty revenue fell to $0.6 million from $4.8 million a year earlier. On a GAAP basis, the net loss narrowed only slightly, to $0.7 million from $1.0 million. Operating income actually slipped to $4.0 million from $4.7 million.
The main reason for that slippage is spending. SG&A rose to $93.9 million from $83.6 million, which the company described as deliberate investment against IBSRELA access barriers. R&D climbed to $25.2 million from $18.1 million as the ACCEL Phase 3 trial ramped. The breakeven result therefore reflects revenue outrunning a rising cost base rather than meaningful margin expansion.
The balance sheet also deserves a closer look. Cash and investments rose to $285.3 million from $264.7 million at year-end, but long-term debt grew by roughly $50 million over the same period. Inventory climbed to $157.6 million from $123.1 million.
The growth trajectory is the crux. IBSRELA revenue rose 23% to $96.3 million, driven by more writers and prescriptions. That rate continues a steady slowdown from 61% in the fourth quarter of 2025, 58% in the first quarter and 33% in the second.
Sequentially, however, IBSRELA grew from $86.2 million to $96.3 million. That is a solid step-up given the payer step edits and stricter prior authorizations management flagged last quarter as the drag on new patient starts. Through nine months, IBSRELA has generated $252.6 million. Hitting the low end of the $350–$370 million range therefore requires only about $97 million in the fourth quarter, roughly the current run rate, so the reset guide now looks conservative rather than stretched.
XPHOZAH is the weaker leg. Growth decelerated to 7% from 27% in the second quarter, and revenue fell sequentially to $29.2 million from $31.9 million. That fits the risks raised last quarter around the post-TDAPA transition, the proposed phosphorus quality measure and the company's loss in the CMS litigation. Commentary from the third-quarter conference call was not available for this review, so the analysis leans on the release and on management's prior-quarter statements.
The release did add genuine forward catalysts. Enrollment in the ACCEL trial of tenapanor for chronic idiopathic constipation finished ahead of schedule, with topline data still expected in the second half of 2027. A positive readout would broaden IBSRELA's addressable market. The USPTO will also issue a formulation patent covering both IBSRELA and XPHOZAH that runs to December 2041, which strengthens the durability argument.
Management said the $1 billion IBSRELA long-term revenue target "remains" but attached no date. Last quarter, the 2029 timing was placed under evaluation and the $750 million XPHOZAH target was withdrawn. Bears can reasonably argue that the long-range story has been softened even if the near-term guide is holding. Operating expense guidance of below $500 million was reiterated, against $384.2 million spent through nine months.
Investor expectations moved meaningfully ahead of the report. Earnings Whispers sentiment improved from -0.32 to roughly neutral at -0.004, a sizable shift from clearly negative.
The stock has not followed. Shares closed at $3.03 before the report, down 25.2% from the $4.05 open after the August release and 43.1% below the 200-day moving average of $5.32. The stock sat just 2.5% above the 52-week low of $2.96 set on October 28, deep in the bottom of its inter-earnings range. The internal trend readings are largely negative on price, momentum and AVWAP, with sequential growth the lone positive. That split mirrors the gap between improving quarter-over-quarter execution and a market still discounting decelerating year-over-year growth.
The bottom line is that Ardelyx delivered what a post-reset quarter needed to deliver. It posted a beat on both lines, reached breakeven and reiterated guidance that now looks achievable, while advancing ACCEL and extending patent coverage. What it did not do is reverse the deceleration. IBSRELA growth has slowed for a fourth straight quarter, XPHOZAH is shrinking sequentially, and the $1 billion target now comes without a timeline. With sentiment already repaired to neutral and shares near their lows, the next leg depends on whether IBSRELA's sequential gains can outlast payer friction long enough for the CIC data to matter.
Read our earnings preview for Ardelyx, Inc.: https://www.earningswhispers.com/article/ARDX/21550
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-23 | |
| Oct-20 | |
| Oct-20 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-05 | |
| Sep-30 | |
| Sep-30 |
