Alight Beats And Raises For A Third Straight Quarter, But Deepening Recurring-Revenue And Margin Erosion And Unfinished Refinancing Temper The Turnaround Story
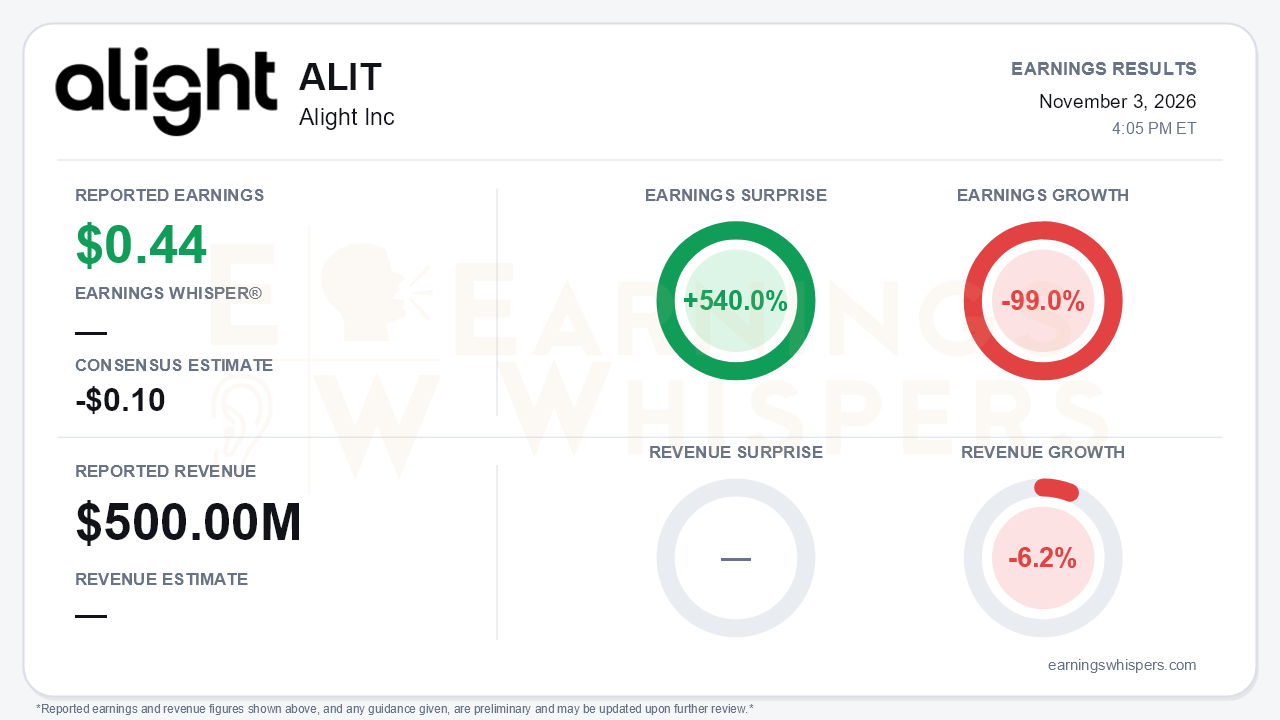
Alight delivered its third consecutive beat-and-raise, but the quarter shows a company winning back credibility while its financial base is still shrinking. Earnings Whispers puts third-quarter earnings at $0.44 per share against a consensus estimate calling for a $0.10 loss, a 540.0% surprise, even as earnings fell 99.0% year over year. Revenue fell 6.2% to $500.0 million. The per-share figures need context. The company's own adjusted diluted EPS from continuing operations was $0.66, down from $2.32. On a GAAP basis, the net loss narrowed to $1.93 per share from $40.52, but nearly all of that improvement reflects the absence of last year's $1.34 billion goodwill impairment rather than better operations. Management raised full-year guidance to $2.115-$2.125 billion in revenue and $410-$420 million in adjusted EBITDA. That is the central tension: Alight is beating its own bar by wide margins, but the business underneath is still contracting.
The quality of the beat deserves scrutiny. Revenue topped management's own $469-$479 million guide. Adjusted EBITDA of $86 million crushed the $55-$61 million outlook. Yet the year-over-year picture is weak. Adjusted EBITDA fell from $138 million, and the margin compressed to 17.2% from 25.9%. GAAP gross margin slid to 27.0% from 33.4%, hurt by lower revenue and higher compensation. SG&A rose $35 million on severance, restructuring and professional fees. Restructuring charges alone were $25 million, versus $4 million a year ago. Management acknowledged that part of the EBITDA upside was cost timing, and those deferred costs are embedded in the fourth-quarter outlook. In other words, the raise is real but smaller than the third-quarter beat would suggest. The guidance midpoint also implies a seasonally heavy fourth quarter of roughly $575 million in revenue and $133 million in adjusted EBITDA, which leaves little room for slippage.
The call showed commercial health improving while reported trends kept getting worse. On the improving side:
- Renewal retention reached the high 90s and has risen every quarter in 2026. Just a year ago, management described it as significantly below target.
- Roughly a quarter of renewals included service expansion.
- Competitive renewals were defended, and new logos were added in enterprise and leave.
- Account-executive coverage now spans relationships representing more than 95% of recurring revenue.
- Consultant sentiment and RFP activity are picking up.
On the weakening side, recurring revenue fell 6% to $458 million, steeper than the roughly 4% declines in the first and second quarters, as 2025 contract losses peak in the second half. Project revenue turned negative, down 5%, after gains of 29% and 11% earlier in the year. Margin erosion widened from about 200 basis points in the first quarter to nearly nine points now. Fee compression in a handful of accounts and a competitive pricing environment remain headwinds. Management does not expect net commercial activity to flatten in 2026 or the financial benefit of better renewals to arrive until the second half of 2027.
The forward catalysts are credible. They include:
- the Abett acquisition, which adds a benefits-intelligence and analytics layer;
- a BNY partnership for an integrated retirement solution, which positions Alight around the emerging Trump accounts opportunity;
- agentic voice AI and AI-enabled enrollment configuration that are already reducing call times;
- a new Wealth leader in Bruce Wolfe.
The balance sheet, however, gives bears legitimate ammunition. Alight disclosed confidential talks with lenders on its credit facility and walked away after failing to get satisfactory terms. That leaves the August 2028 term-loan maturity unresolved against $1.99 billion of total debt and $212 million of cash. Year-to-date free cash flow of $108 million trails last year's $151 million. Third-quarter free cash flow was only about $7 million, which management attributed to seasonality. Conversion is now framed at about 40% of EBITDA, below the 40-43% discussed in August. Tax receivable agreement payments of $136 million year to date are absorbing much of the cash. The dividend has effectively been eliminated, and there were no buybacks.
The market had already priced in deep skepticism. Shares closed at $9.88 ahead of the report, down 34.8% from the $15.15 open after the August release. The stock hit a 52-week low of $7.93 on October 19, around the time the lender talks surfaced, and has since rebounded about 25% off that low. It still sits nearly 38% below its inter-earnings high of $15.86. The reported 200-day moving average of $205.90 appears to reflect the 1-for-20 reverse split and is not a meaningful reference point. Investor sentiment was negative going in and edged lower, to -0.19 from -0.16, a modest deterioration. The Earnings Whispers trend signals are mixed, with sequential growth and AVWAP readings negative while price and momentum are neutral.
The bottom line is that Alight is executing its turnaround better than skeptics expected. Retention, coverage, guidance and management's tone have all moved in the right direction. But recurring revenue declines and margin compression are still deepening, the payoff from better renewals sits well into 2027, and an unresolved refinancing hangs over a leveraged balance sheet. The beat buys credibility, not yet a growth inflection.
Read our earnings preview for Alight Inc: https://www.earningswhispers.com/article/ALIT/21543
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-20 | |
| Oct-13 | |
| Oct-06 | |
| Oct-01 | |
| Sep-15 | |
| Sep-03 | |
| Aug-18 | |
| Aug-12 | |
| Aug-11 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 |
