RxSight Edges Past EPS Estimates, But A Revenue Miss And A Fourth Straight Unit Decline Push The Turnaround Into 2027
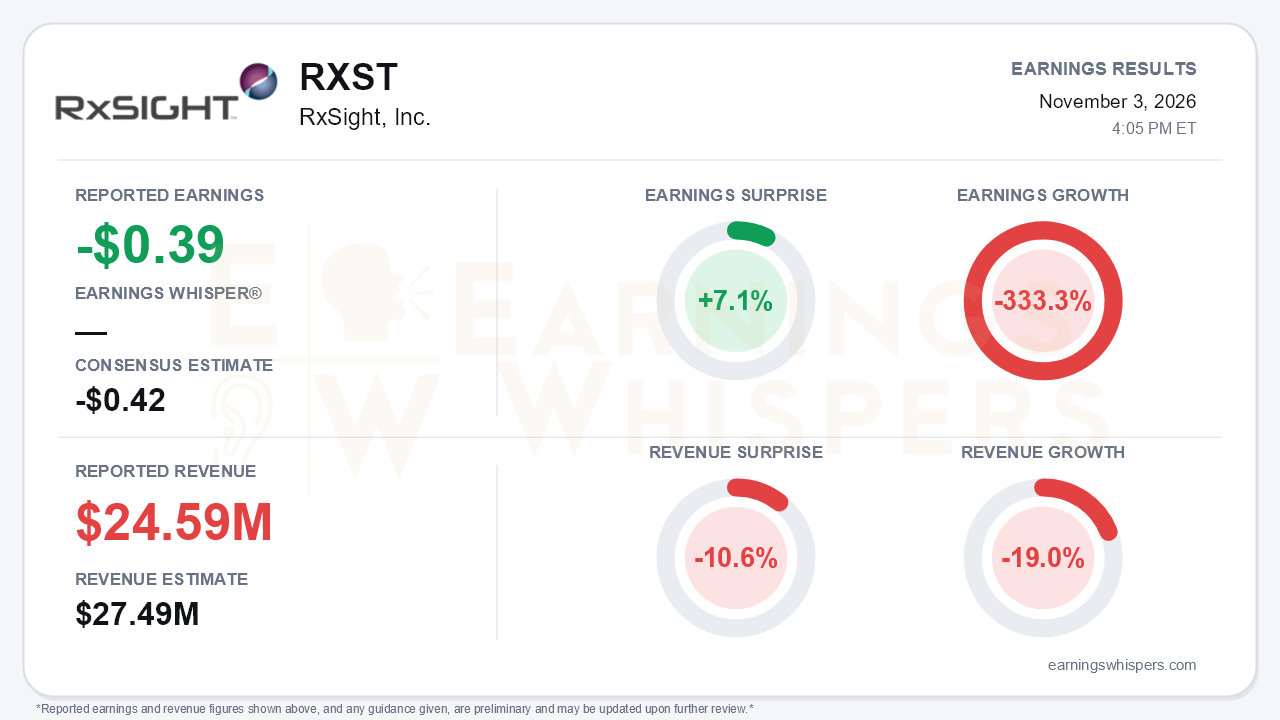
RxSight's third-quarter EPS beat is the least informative number in the report. The company lost $0.39 per share, $0.03 better than the -$0.42 consensus and a 7.1% positive surprise. Revenue of $24.59 million missed the $27.49 million consensus by 10.6% and fell 19.0% year over year. Earnings fell 333.3% from a year ago as the GAAP loss widened to $16.2 million from $9.8 million. The core Light Adjustable Lens franchise is still shrinking, and the bottom-line beat came against a bar that was already set low. That is the central tension: new CEO Aziz Mottiwala is rebuilding the commercial organization, the Alcon partnership and the cash pile, while the existing business keeps losing ground.
The quality of the quarter deserves scrutiny.
- **Revenue:** Product sales were $24.5 million. The Alcon collaboration contributed only $40,000, which management described as minimal in the program's early stages.
- **Gross margin:** Margin fell to 73.6% from 79.9% a year earlier, versus 76.1% in Q1 and 77.5% in Q4 of last year. The company blamed higher inventory reserves and higher LAL and LDD inventory costs. That leaves margin near the bottom of the 73% to 75% range management outlined on the Q2 call.
- **Inventory:** Inventory climbed to $39.6 million from $31.6 million at year-end even as unit volumes fell. That build raises the possibility of further reserve pressure.
- **Expenses:** Total costs held at $43.1 million, essentially flat, so the revenue shortfall flowed directly into a wider operating loss of $18.5 million.
- **Non-GAAP:** The adjusted net loss, which excludes stock compensation, deteriorated more sharply, to $0.21 per share from $0.04.
The call laid bare how steadily the core business has eroded:
- **LAL units:** 28,611 in Q4 of last year, then 27,472, 24,917 and 23,128 this quarter, down 11% year over year.
- **LDD placements:** Device placements, the leading indicator of future lens volume, fell to just three units sold plus one rental. That compares with 11 plus one in Q2, 20 in Q1 and 25 in Q4. Management now expects only a handful per quarter.
Management cited competitive trialing and free sampling, including from J&J's PureSee, now encroaching on the post-refractive niche. It also acknowledged self-inflicted disruption from territory remapping, sales onboarding and restructuring. The tone has shifted from Q1's talk of a turnaround taking hold to candid admissions that the company was poorly prepared for competition and faces near-term pain.
Guidance credibility has also eroded. The original $120 million to $135 million 2026 outlook was replaced in Q2 by a $140 million to $160 million range that included $30 million to $40 million of Alcon revenue, which implied base sales were cut to $110 million to $120 million. This quarter, management offered no formal 2026 guidance at all. It did say Q4 LAL revenue should return roughly to Q2 levels, implying mid-to-high single-digit sequential growth. Combined with $82.7 million in nine-month product sales, that points to full-year product revenue around the low end of the prior base range or slightly below it.
The forward catalysts are real but back-end loaded:
- **Commercial rebuild:** The U.S. sales force has nearly doubled. Taryn Conway was named Chief Commercial Officer and Frank Shields EVP of Sales and Commercial Strategy.
- **Cost structure:** Restructuring across manufacturing, G&A and international operations is expected to bring 2027 operating expenses below 2026 levels despite the added investment.
- **Pipeline and Alcon:** Next-generation LAL approval is possible as early as 2028, and 2027 guidance is expected to include pipeline and Alcon milestones.
- **International:** Overseas markets were deprioritized, after being framed as a 2027 driver earlier this year.
The balance sheet buys time. Cash and investments rose to $254.7 million from roughly $209 million in Q2. One nuance matters: as of September 30, the balance sheet carried a $50 million refund liability. Management said the 120-day period has since been completed, which it characterized on the call as locking in the $60 million upfront payment.
Investor expectations were already deteriorating before the report, and price action reflects a market that has lost patience:
- **Sentiment:** Earnings Whispers investor sentiment remained negative and weakened modestly, from -0.20 to -0.27.
- **Price:** Shares entered the report at $4.80, down 20% from the $6.00 open after the August release and nearly 25% below the 200-day moving average of $6.38.
- **Trading range:** The stock touched a 52-week low of $4.40 on October 14 and sat about 9% above that level, more than 35% below the $7.44 inter-earnings high set on September 1.
- **Trend signals:** Price and AVWAP trends are both negative, consistent with sustained selling pressure through the quarter.
The bottom line is that RxSight's EPS beat does little to change a story defined by shrinking LAL volumes, collapsing LDD placements, compressing margins and the absence of formal guidance. Bears have legitimate ammunition in a fourth straight sequential unit decline and an inventory build. Bulls can point to roughly $255 million in cash, a lower 2027 cost base, a rebuilt sales leadership team and the Alcon partnership. Until the promised Q4 rebound in LAL revenue materializes, though, the turnaround remains a 2027 thesis rather than something visible in the numbers.
Read our earnings preview for RxSight, Inc.: https://www.earningswhispers.com/article/RXST/21620
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-23 | |
| Oct-20 | |
| Oct-19 | |
| Aug-26 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Jul-26 | |
| Jul-15 | |
| Jul-06 | |
| Jul-06 | |
| Jul-02 |
