Zevra Beats As MIPLYFFA Hits A Record, But Fading EAP Revenue And Rising Spend Cloud The Quarter
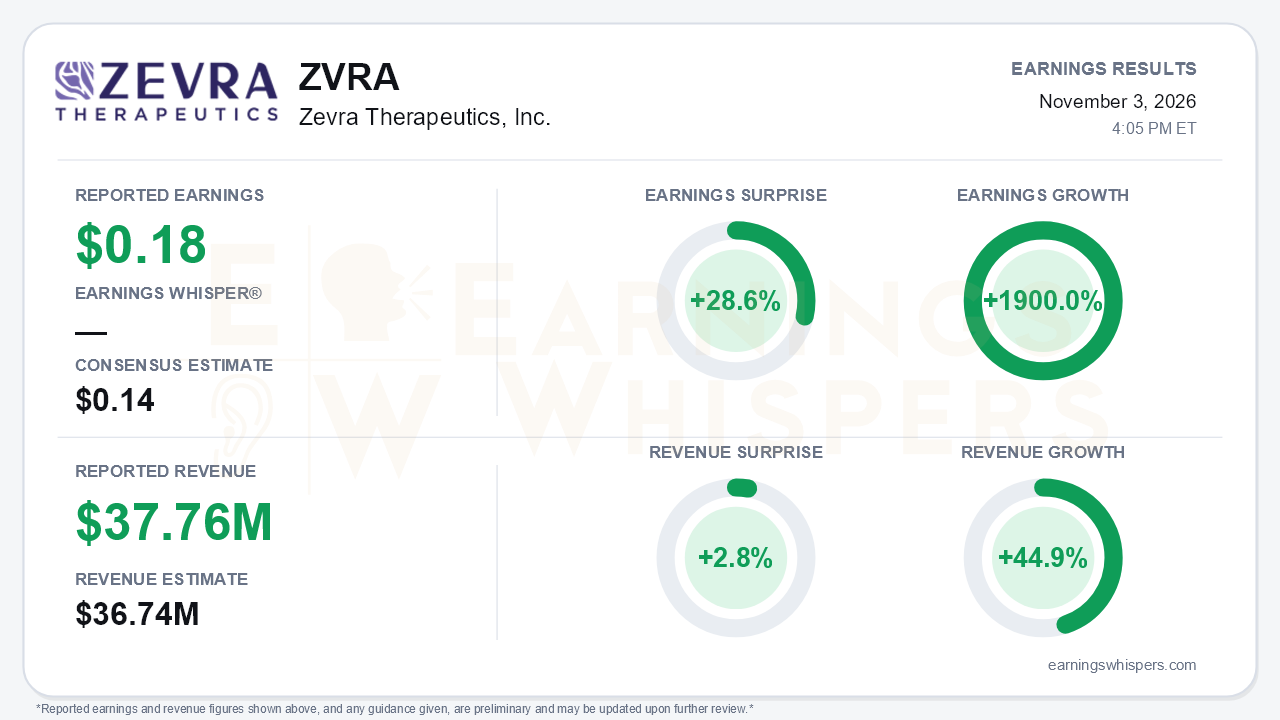
Zevra Therapeutics delivered a clean headline beat for the third quarter. On Earnings Whispers' normalized basis, it earned $0.18 per share against a $0.14 consensus, a 28.6% surprise, on revenue of $37.76 million that topped the $36.74 million estimate by 2.8%. Revenue grew 44.9% year over year and earnings rose 1900.0%, which in plain terms is a swing from a $0.5 million net loss a year ago to $19.2 million of GAAP net income. The central takeaway is that the core franchise is getting stronger while the consolidated numbers are getting noisier. U.S. MIPLYFFA net revenue reached a record $34.0 million, up 12.6% sequentially and 52% year over year. Total revenue, however, slipped from $39.7 million in Q2 because Expanded Access Program reimbursements fell to $3.6 million from $9.0 million.
The quality of the beat deserves scrutiny. GAAP diluted EPS was $0.26, well above the normalized $0.18. The gap reflects below-the-line items that flattered the bottom line. The release cites $5.1 million of non-cash income from warrant and contingent value rights fair-value adjustments, which the call analysis characterizes as roughly a $5.5 million warrant gain. Interest and other income added another $3.0 million, and the tax provision was just $0.5 million. GAAP operating income of $11.6 million is the better read on the business. That figure is a sharp improvement from $4.1 million a year earlier, but it is down from Q2 as operating expenses climbed to $24.1 million from about $21.0 million. R&D rose to $4.9 million on arimoclomol and celiprolol work. SG&A reached $19.1 million on commercial and infrastructure costs. The cash build also slowed to $10.7 million from $23.4 million last quarter, although the company is debt-free and ended with $270.9 million in cash and investments.
The operating picture underneath is more encouraging than the sequential revenue dip implies:
- **Payer coverage and refills:** Coverage held at 69%, and refill rates remain high.
- **Market size:** Management materially reframed the opportunity. After describing the diagnosed U.S. NPC population as "somewhere between 350 and 900" earlier in the year, it now says claims data indicate the diagnosed population exceeds the 300-350 estimate. On that basis, it is modestly expanding the field team into community practices.
- **Awareness:** Disease-awareness site visits rose 123% sequentially, to about 56,000.
The weak spot is new-patient flow. Zevra received 13 enrollment forms in the quarter, roughly flat with 14 in Q2 and well below 24 in Q4 2025, bringing the cumulative total to 197. Revenue growth is coming from persistence and pricing durability more than from an accelerating intake funnel. That makes the market-size argument something management still has to prove with enrollments.
The forward calendar is crowded and partly binary:
- **Pediatric label expansion:** After an FDA meeting, Zevra plans an sNDA in Q1 2027 to extend MIPLYFFA to infants under 24 months. Management sizes that group at about 5% of the addressable market.
- **Celiprolol:** DiSCOVER enrollment reached 72 patients with four confirmed events. A second Type C meeting produced a strategy to incorporate retrospective real-world data, with an FDA follow-up targeted for the first half of 2027.
- **Europe:** The CHMP re-examination, following the prior negative opinion, has convened an ad hoc expert group, and an opinion is still expected in Q4.
Bears have legitimate ammunition here. Shionogi's acquisition of IntraBio puts a larger, better-funded competitor behind Aqneursa in NPC, though management framed the deal as market-expanding. The patent term extension decision has also slipped to 2027, and EAP revenue has proven lumpy. Zevra also offers no formal guidance to anchor expectations.
The market had not been rewarding the story heading into the print. Shares closed at $10.10 on November 2, down 10.7% from the $11.31 open following the August report. The stock sat about 6% below its 200-day moving average of $10.74 and 21.7% below its September 8 inter-earnings high of $12.90. It was only 6.8% above the October 26 low of $9.46. Price and AVWAP trend readings are negative, while sequential growth is positive, which mirrors the split between a growing product line and a stock that has been sold. Investor sentiment remained negative but improved slightly, moving from -0.50 to -0.46. That is a modest thaw rather than a shift in conviction.
The bottom line is that Zevra's quarter was better than its consolidated revenue line and worse than its GAAP EPS suggest. MIPLYFFA is compounding, the balance sheet is strong, and management is making a credible case for a bigger market. Flat enrollment intake, rising spend, a softer operating line and an imminent binary EU decision keep the setup contested. With shares near the bottom of their range and sentiment still negative, the near-term debate will likely hinge on the CHMP outcome and whether enrollment forms begin to reflect the larger patient population management now describes.
Read our earnings preview for Zevra Therapeutics, Inc.: https://www.earningswhispers.com/article/ZVRA/21648
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-20 | |
| Sep-02 | |
| Aug-25 | |
| Aug-21 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Aug-03 | |
| Jul-24 | |
| Jul-24 |
