Comscore Beats Low Expectations As Cost Cuts Rebuild Margins, But Shrinking Revenue And A $19.5 Million Cash Balance Define The Setup
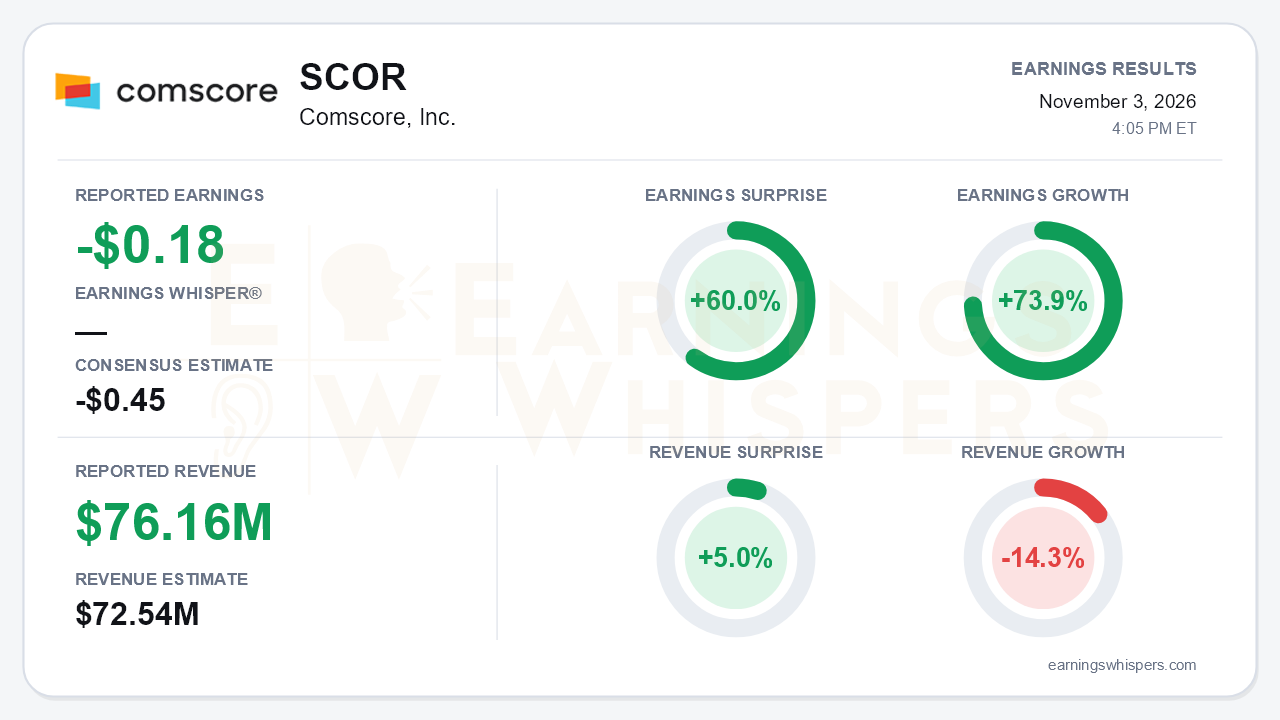
Comscore cleared a low bar in the third quarter. The company reported a loss of $0.18 per share against a consensus estimate of -$0.45, a 60.0% earnings surprise. Revenue of $76.16 million topped the $72.54 million consensus by 5.0%. On a year-over-year basis, earnings improved 73.9% as the loss narrowed, while revenue fell 14.3%. Management reaffirmed full-year guidance, which was in line with expectations. The central tension is that the cost side of the turnaround is working faster than expected, while the revenue base keeps shrinking and the balance sheet leaves little room for error.
The quality of the beat deserves scrutiny. GAAP results looked far worse than the normalized figure. Comscore posted a net loss of $65.5 million, or $4.26 per share, compared with net income of $0.5 million a year ago. That loss was driven by a $57.3 million non-cash goodwill impairment and $5.5 million of restructuring costs. Management tied the impairment partly to the decline in the stock price and market capitalization, so the write-down reflects the stock's slide as well as the realignment. Adjusted EBITDA fell to $5.8 million from $11.0 million, and the margin dropped to 7.6% from 12.4%. Part of that comparison reflects the absence of the Movies business, which contributed $9.5 million of revenue in last year's quarter. Excluding Movies, revenue declined 4.1%.
The sequential picture is where the bull case lives. On a pro forma basis, the revenue decline narrowed from 8.5% in the second quarter to 4.1% in the third. Adjusted EBITDA margin rebounded from 1.7% to 7.6%. Core operating expenses fell 8.0% year over year, compared with a 2.8% decline in the prior quarter, helped by lower compensation, data, and facilities costs. Management said most of the headcount reductions are complete and that more than $20 million of annual run-rate savings has been achieved, keeping the $20 million to $25 million target intact. A renegotiated MVPD data contract should add mid-seven-figure savings in 2027.
Demand, however, softened in places that matter.
- **Cross-Platform:** Revenue was flat at $12.2 million, compared with 20% growth a year earlier and 24% growth for fiscal 2025. That undercuts the double-digit growth for the segment that management projected at the start of the year. The call attributed the stall to platform shutdowns and shifts in open-web advertising.
- **Syndicated Audience:** Revenue fell 17%, largely because of the Movies divestiture but also because of weaker syndicated digital products.
- **Research & Insight Solutions:** Revenue fell 13.9% on lower renewals and fewer deliveries of certain custom digital products.
- **Deliberate runoff:** Management is sunsetting on-demand and other legacy lines. It also turned down an international measurement contract the company had already won.
These choices may sharpen focus, but they also narrow the revenue opportunity. The chief revenue officer role is still held on an interim basis, which leaves a gap in commercial leadership during a period of declining renewals.
Liquidity has become the issue bears will press hardest. Cash, cash equivalents, and restricted cash totaled $19.5 million, down $7.3 million since year-end. That decline came even though the company received $55.7 million in net divestiture proceeds and used most of it to retire its term loan. Management said it is seeking working-capital flexibility. Stockholders' equity has shrunk to $24.4 million, while the Series C preferred stock carries a $183.7 million liquidation preference. On the positive side, management expects $3 million to $4 million of fourth-quarter cash inflows from Movies escrow and transition-services receivables. It also set a goal of exiting 2027 with cash-flow-positive operations, an objective rather than a forecast. Early growth proof points exist but remain small:
- an AI intent-segment pilot that beat a client's best third-party data by 38%, with 25 segments rolling out to platforms this month;
- measurement work with a Top 10 creator on brand integration impact;
- progress toward commitments from strategic local TV buyers and sellers.
The market had already delivered a harsh verdict before the report. Shares closed at $3.38 on November 2. That is down 50.3% from the $6.80 open following the August report, which was also the high of the quarter. The stock sits 48.7% below its 200-day moving average and only 10.8% above the 52-week low of $3.05 set on October 27. Investor sentiment stood at a clearly negative -0.59. The Earnings Whispers trend signals are largely negative, with price, momentum, and AVWAP readings all weak. Those readings show how little credit investors were extending to the restructuring story going into the print.
The bottom line is that Comscore delivered a better-than-feared quarter and genuine sequential margin repair, which turnaround skeptics were not fully positioned for. The reaffirmed guidance, however, still calls for full-year revenue of $315 million to $325 million and a low-to-mid single-digit EBITDA margin. That is well below fiscal 2025's $357.5 million and 11.8% margin. Until cross-platform growth resumes, renewals stabilize, and the company secures the working-capital flexibility it is seeking, the cost-cutting success will compete with legitimate concerns about a shrinking business and a thin cash cushion.
Read our earnings preview for Comscore, Inc.: https://www.earningswhispers.com/article/SCOR/21623
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-30 | |
| Oct-28 | |
| Oct-26 | |
| Oct-26 | |
| Oct-21 | |
| Sep-23 | |
| Sep-22 | |
| Sep-22 | |
| Sep-03 | |
| Sep-03 | |
| Aug-21 | |
| Aug-13 |
