Kodak Beats On EPS, But Print's Reversal And Revenue Miss Show The Growth Story Losing Steam
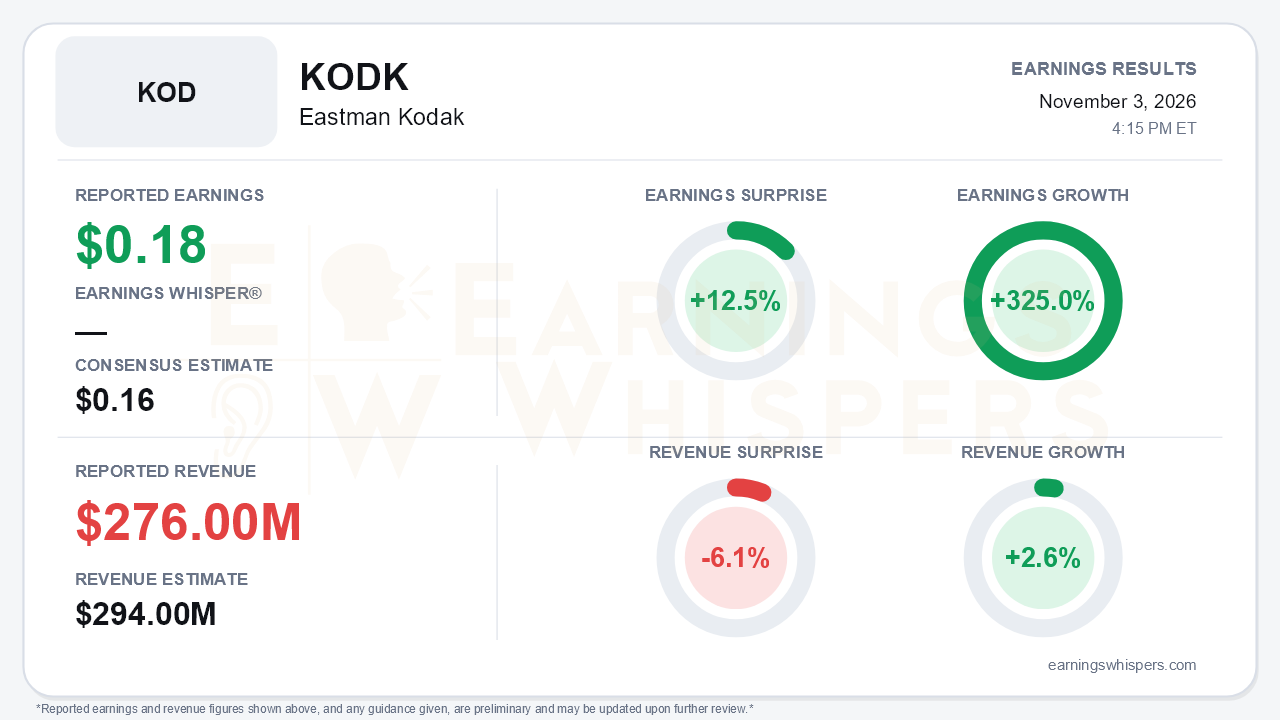
Eastman Kodak's third-quarter report beat on the bottom line and missed on the top line, and the miss tells the more important story. The company earned $0.18 per share, topping the $0.16 consensus by 12.5%. That compares with a loss of $0.08 per share attributable to common shareholders a year ago, a swing that registers as 325.0% earnings growth. Revenue of $276.0 million rose only 2.6% and fell 6.1% short of the $294.0 million consensus. After revenue grew 18% in the second quarter, the top line has decelerated sharply, and the Print business that had been a surprise contributor earlier in the year has turned back into a drag.
The beat came mostly from below the operating line. GAAP net income rose to $21 million from $13 million, but income from operations actually fell to $15 million from $19 million. SG&A climbed to $50 million from $41 million, driven largely by stock-based compensation, which rose to $8 million from $1 million, and by changes in employee benefit accruals. What carried the bottom line was interest expense, which collapsed to $3 million from $18 million after the company cut debt by roughly $400 million. Pension income of $15 million also contributed. The EPS beat reflects a cleaner capital structure more than stronger operations. That is a legitimate improvement, but it is not the same thing as operating momentum. Operational EBITDA, a non-GAAP measure, rose just $2 million year over year to $31 million and fell sequentially from $36 million.
The segment detail shows where the slowdown is coming from. Print revenue fell 7% to $165 million, a reversal from growth of 10% in the second quarter and 9% in the first. Print's operational EBITDA dropped to just $1 million from $8 million. Management blamed several factors:
- higher raw material prices and availability;
- digital substitution;
- competitive pricing;
- what it called an "uneven playing field" in Europe.
Advanced Materials & Chemicals (AM&C) remains the bright spot. Its revenue rose 21% to $99 million and its operational EBITDA increased to $21 million from $16 million. The unit now accounts for about 36% of revenue and more than half of operational EBITDA. Even here, though, momentum cooled. AM&C growth slowed from 40% in the second quarter, and revenue slipped sequentially from $105 million. Gross margin held at 26%, flat with the second quarter and up a point from a year ago, so the deceleration is a volume and mix problem rather than a pricing collapse.
The call's tone shifted accordingly. Second-quarter language about building momentum and consecutive growth across key metrics gave way to references to "challenging times" and a print business "performing as expected." Kodak again offered no formal guidance and took no questions, which leaves investors with little visibility into whether Print's decline is cyclical or structural. Silver and aluminum inflation is another live risk. It raised manufacturing costs and helped drive a $44 million year-to-date inventory build, which explains why year-to-date operating cash flow was only break-even despite a solid $25 million in the third quarter.
The forward catalysts sit almost entirely in AM&C:
- continued motion-picture film wins, including Tom Cruise's 'Digger' shot in VistaVision;
- pharma progress;
- investment in large-scale battery electrode coating capacity through a pilot facility.
The balance sheet is the clearest improvement. Unrestricted cash rose $27 million sequentially to $317 million. Net cash reached $207 million, up from $128 million at year-end. Restricted cash stood at $80 million versus $96 million at year-end, and management is pursuing further releases of collateral.
The market had already turned skeptical heading into the print. Shares closed at $8.79 before the report, down 12.3% from the $10.02 open following the August release. They sat 5.4% below the 200-day moving average and just 2.9% above the inter-earnings low of $8.54 set in mid-October. They had also given back all of an early-August run to $10.31. Investor sentiment stood at -0.04, essentially neutral with a slight negative lean, which suggests little enthusiasm was priced in. Earnings Whispers trend readings are mixed: price and AVWAP trends are negative while momentum is positive.
The bottom line is that Kodak delivered a financially healthier quarter but an operationally weaker one. Debt reduction and lower interest costs produced the EPS beat and a markedly stronger balance sheet. Meanwhile, Print's swing to decline, AM&C's sequential dip, flat-to-down operational EBITDA and a softer management tone point to fading growth. Bulls can point to AM&C's growing share of profits and a net cash position that buys time. Bears have legitimate ammunition in a revenue miss and a Print business that no longer looks stable.
Read our earnings preview for Eastman Kodak: https://www.earningswhispers.com/article/KODK/21996
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-28 | |
| Oct-28 | |
| Sep-15 | |
| Sep-12 | |
| Aug-06 | |
| Aug-05 | |
| Aug-04 | |
| Jun-13 | |
| May-15 | |
| May-12 | |
| May-11 | |
| May-07 |
