AMD's Modest Beat Gives Way To A Much Bigger 2027 Outlook, While PC Weakness And Thin Free Cash Flow Test The Story
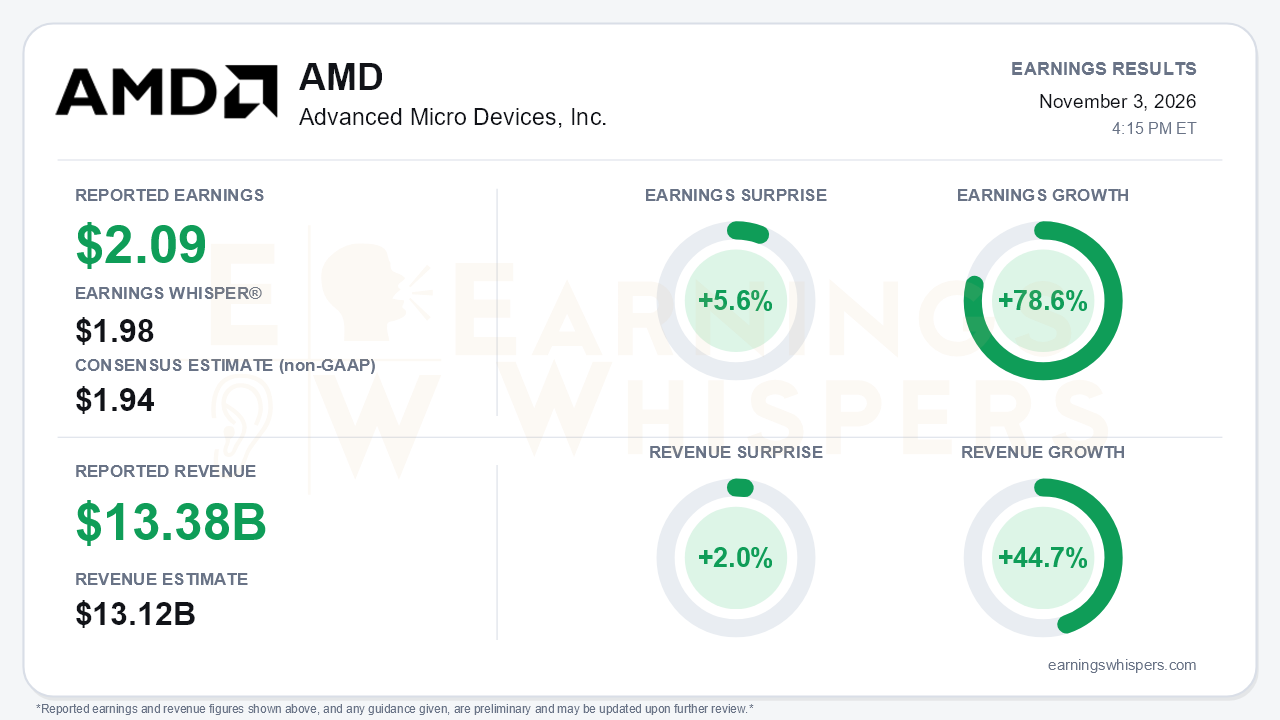
Advanced Micro Devices delivered a solid third-quarter beat, but the more important development was the size of the outlook management put behind it. Non-GAAP EPS of $2.09 topped the $1.94 consensus by 5.6% and cleared the $1.98 Earnings Whisper number. Revenue of $13.377 billion beat the $13.12 billion consensus by 2.0%. Earnings grew 78.6% year over year on 44.7% revenue growth. AMD's own non-GAAP comparison shows 74%, but either way profits are compounding much faster than sales. The forward view was stronger still: a fourth-quarter revenue guide of roughly $17 billion, plus or minus 3%, implies about 66% year-over-year growth and a 27% sequential jump. On the call, management said it now expects 2027 revenue to grow more than 80%. That is more than double its long-term model of above 35%. The quarter was a beat; the guidance is a step change.
The composition of the quarter explains why. Data Center revenue nearly doubled, rising 97% to a record $8.5 billion, and now makes up 64% of sales, up from 47% a year ago. Segment operating income climbed to $2.9 billion from $1.1 billion. Non-GAAP operating margin expanded to 29%, from 27% in Q2 and 25% in Q1, as operating expenses grew more slowly than revenue. GAAP results need context. GAAP EPS of $1.46 absorbed a roughly $1.1 billion non-cash charge from remeasuring warrants issued to customers. That charge rises with AMD's stock price, and management flagged that it will grow and carries future dilution. A large tax benefit offset much of the hit. The adjusted figures are therefore a cleaner read on operations, but investors should not dismiss the warrant structure as noise. It is a real economic cost of winning large AI customers.
The call showed management's 2027 framework rising at every recent report:
- Server revenue growth is now expected to roughly double next year, up from more than 70% on the Q2 call.
- Data center AI growth was described as faster than projected 90 days ago.
- Data center is expected to exceed 80% of 2027 revenue.
In Q3, MI450-series Helios racks began revenue shipments to Anthropic, Meta, Microsoft, OpenAI and Oracle. Venice EPYC shipments also started, with more than 240 platforms, about 20% more than Turin. Management expects data center AI revenue to surpass server CPU revenue in Q4, with Data Center up roughly 50% sequentially. Embedded accelerated for another quarter, to 29% growth. AMD also agreed to buy World Labs and Taalas, an inference-silicon specialist; the call notes render that name as Thales.
The weak spots are real, and bears have legitimate ammunition. Client growth slowed sharply to 7% year over year, from 23% in Q2, and fell 4% sequentially as memory-cost inflation hurt PC sell-through late in the quarter. Management now guides Client and Gaming down more than 20% sequentially in Q4. It is also planning for a double-digit decline in PC units in 2027, a reversal from its optimism a quarter ago. Gaming fell 40% on the console cycle. The fourth-quarter gross margin guide eased to about 55% from 56% as lower-margin AI systems become a larger share of sales, and management offered no quarterly margin visibility for 2027. Most notable is cash flow. Free cash flow dropped to $554 million, a 4% margin, from $1.6 billion in Q2 and $2.6 billion in Q1. Inventory swelled by roughly $3 billion to $11.5 billion, and capital spending stayed elevated. Total debt more than doubled to $7.1 billion after a $4.7 billion issuance. Supply still trails demand, and HBM cost inflation requires cost sharing with customers. AMD is funding a ramp, and the cash will lag the earnings.
The market setup is more complicated than the surprise implies. Shares hit a 52-week high of $658.52 on October 6. They then lost about 29% to $466.84 heading into the report, which leaves the stock down 3.6% since the opening after the August release. They sit only 6% above the September low of $440.50, though still 13.7% above the 200-day moving average. Investor sentiment remained mildly positive but slipped slightly, from 0.16 to 0.14. The trend signals are mixed: sequential growth and momentum readings are positive, while AVWAP remains negative.
The bottom line is that AMD gave investors a quarter in which the guidance matters far more than the beat. A $17 billion fourth-quarter outlook and a 2027 growth target above 80% reframe the company as a scaled AI systems supplier. The costs of that shift are also visible: a fading PC business, a slightly lower margin mix, warrant-driven GAAP volatility and dilution, and sharply weaker free cash flow. With shares well off their October peak, execution on Helios and the conversion of that inventory into cash will decide whether the larger story earns back the market's confidence.
Read our earnings preview for Advanced Micro Devices, Inc.: https://www.earningswhispers.com/article/AMD/21545
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 10 min | |
| 1 hour | |
| 2 hours | |
| 2 hours | |
| 2 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 3 hours |
